

Live now
Index readings from the same feed the Sahi terminal runs on. Open the live Implied Volatility to see this guide applied to today’s numbers.
- NIFTY — —
- BANKNIFTY — —
- SENSEX — —
What Implied Volatility Is
What is implied volatility, and what will this page not tell me?
The Price of Rain Cover
Suppose a shopkeeper sells cover against rain on the day of a fair. In a dry week the cover is cheap. If the forecast turns stormy, the same cover costs more, although nobody has yet seen a drop of rain. The price tells you how much rain the seller expects to pay for. It does not tell you whether it will rain.
An option price works the same way. The more movement the market expects in the underlying before expiry, the more the option costs. Implied volatility is that expectation, read back out of the price and written as one yearly percentage.
Seven Terms Before You Start
These words appear in the first picture, so here they are once, in a line each. Each links to its glossary entry.
- Implied volatility (IV)
- The size of move an option’s price is paying for, written as a yearly percentage. It is worked out from the price, not forecast. Higher IV means dearer options. It says how big a move is priced, never which way.
- Premium
- The price of one option, in rupees per unit. The chain prints it as the last traded price. It is the number from which implied volatility is worked out.
- At the money (ATM)
- An option whose strike is at, or nearest to, where the underlying stands. On this page the centre is the forward, not spot.
- Forward
- Where the option prices put the underlying at expiry: spot plus the cost of carrying it until then. The page reads it from the traded Call and Put prices, using put–call parity, at a fixed yearly rate of 6.5%.
- Priced move
- The move the at-the-money IV pays for, in points: spot × IV × √(days left ÷ 365). One standard deviation. Printed to expiry and per day.
- Session
- One trading day. Weekends and exchange holidays are not sessions: the market is shut and the page counts no movement on them.
- IV Percentile (IVP)
- The share of the last 252 closes of the 30-day IV that closed below today’s. Shown once 60 sessions of closes exist.
Implied volatility, written IV, is not observed. It is solved for: the pricing model is run backwards from an option’s traded price until it returns the volatility that gives that price. A reading of 11.84% means that, with this strike, this expiry and this level of the underlying, the traded prices are consistent with a yearly volatility of 11.84%. The number is easy to find on any option chain and hard to use, because nobody can see a percentage in a chart of the index.
This page therefore does two things with it. It turns the percentage into points, the unit of the index you already watch: how far the underlying can travel, by expiry and in one session, at the size the option prices are paying for. And it puts the reading next to two comparisons: the days the underlying has actually had, and the reading’s own past year. Nothing on the page says which way the price will go. IV can rise in a falling market and in a rising one, because both are movement, which is why the page never colours an IV level.
Where the Numbers Come From
- Today’s readings. The page solves IV afresh from the traded premiums of the Call and the Put at each strike, in the one-minute snapshots collected for the day. It does not read the IV stored in the files, because most day files hold a zero there. A minute whose prices do not give an IV is left out of the line, never drawn as zero.
- The other expiries. The option chains of the next live expiries are read when the page opens and then at most once a minute (3 expiries at most), and only when a new reading has arrived.
- The underlying’s daily closes. The last 20 sessions give the actual day. The page asks for about a year of daily closes, once.
- The year of 30-day IV. A file of daily closes built from NSE’s F&O closing prices (the bhavcopy). On the live page it now runs from 15 September 2025 to 16 October 2026, 270 sessions (not rebuilt by us). The Options Scanner ranks the same file.
- India VIX. For NIFTY only, read at most once a minute.
- How fresh. The chain pages re-fetch about every 5 seconds while the market is open. This page works from the one-minute archive and says the time of its newest reading in the insight row. This page does not use Open Interest at all: it reads traded premiums.
Read an IV Reading in Two Minutes
What do I read first, and in what order, to know whether option prices are dear or cheap right now?
The first time, the page opens on NIFTY, its nearest expiry and the Intraday view; after that it reopens on the view you left. The insight row, and the detail panel behind it, give four answers above every view. They are in a fixed order, and so is the way to read them: first how big a move the option prices are paying for, in points; then whether that is more or less than the days the market has really had; then where today’s level sits in its own past year; and last how the level moved today. The six steps below take about two minutes. The page places no order at any step.
Your First Five Minutes
- Start with the points, not the percentage. A figure such as 11.84% is hard to judge. The first line of the insight says what it means in index points.
- Check the time. The insight row ends with the time of the data, for example “30 Sep 2026, 11:30 am IST”. Every figure is as of that time.
- Read one level against one comparison. A level on its own is never high or low. Set it against recent days (the third line of the insight) or against its own year (the second).
- Treat the colours as changes only. A level is never green or red. Only a change carries a direction colour, and a change in IV is not a change in price.
- Nothing here is a trade or a forecast. The page measures what option prices are paying for. It does not say what the market will do.
-
Open the page and read the insight row
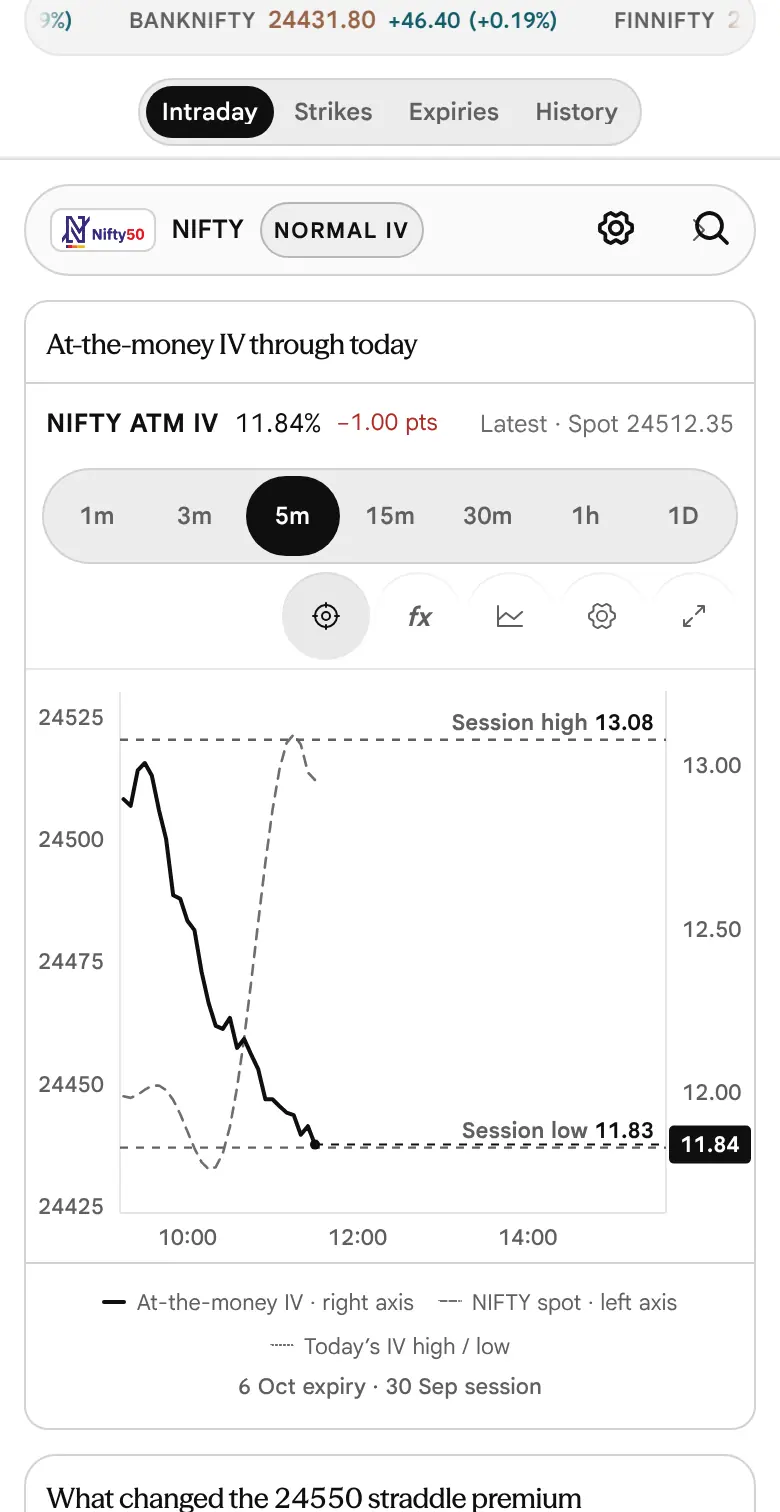
Open Implied Volatility. Under the page bar you see a thin insight row: the verdict in words, the at-the-money IV, its three small changes and one short line of the priced move. Under it the chart of the view you chose runs to the bottom of the window. On a phone the same row sits above the chart, and the Intraday and History charts fill the rest of the screen (see Reading it on a phone).

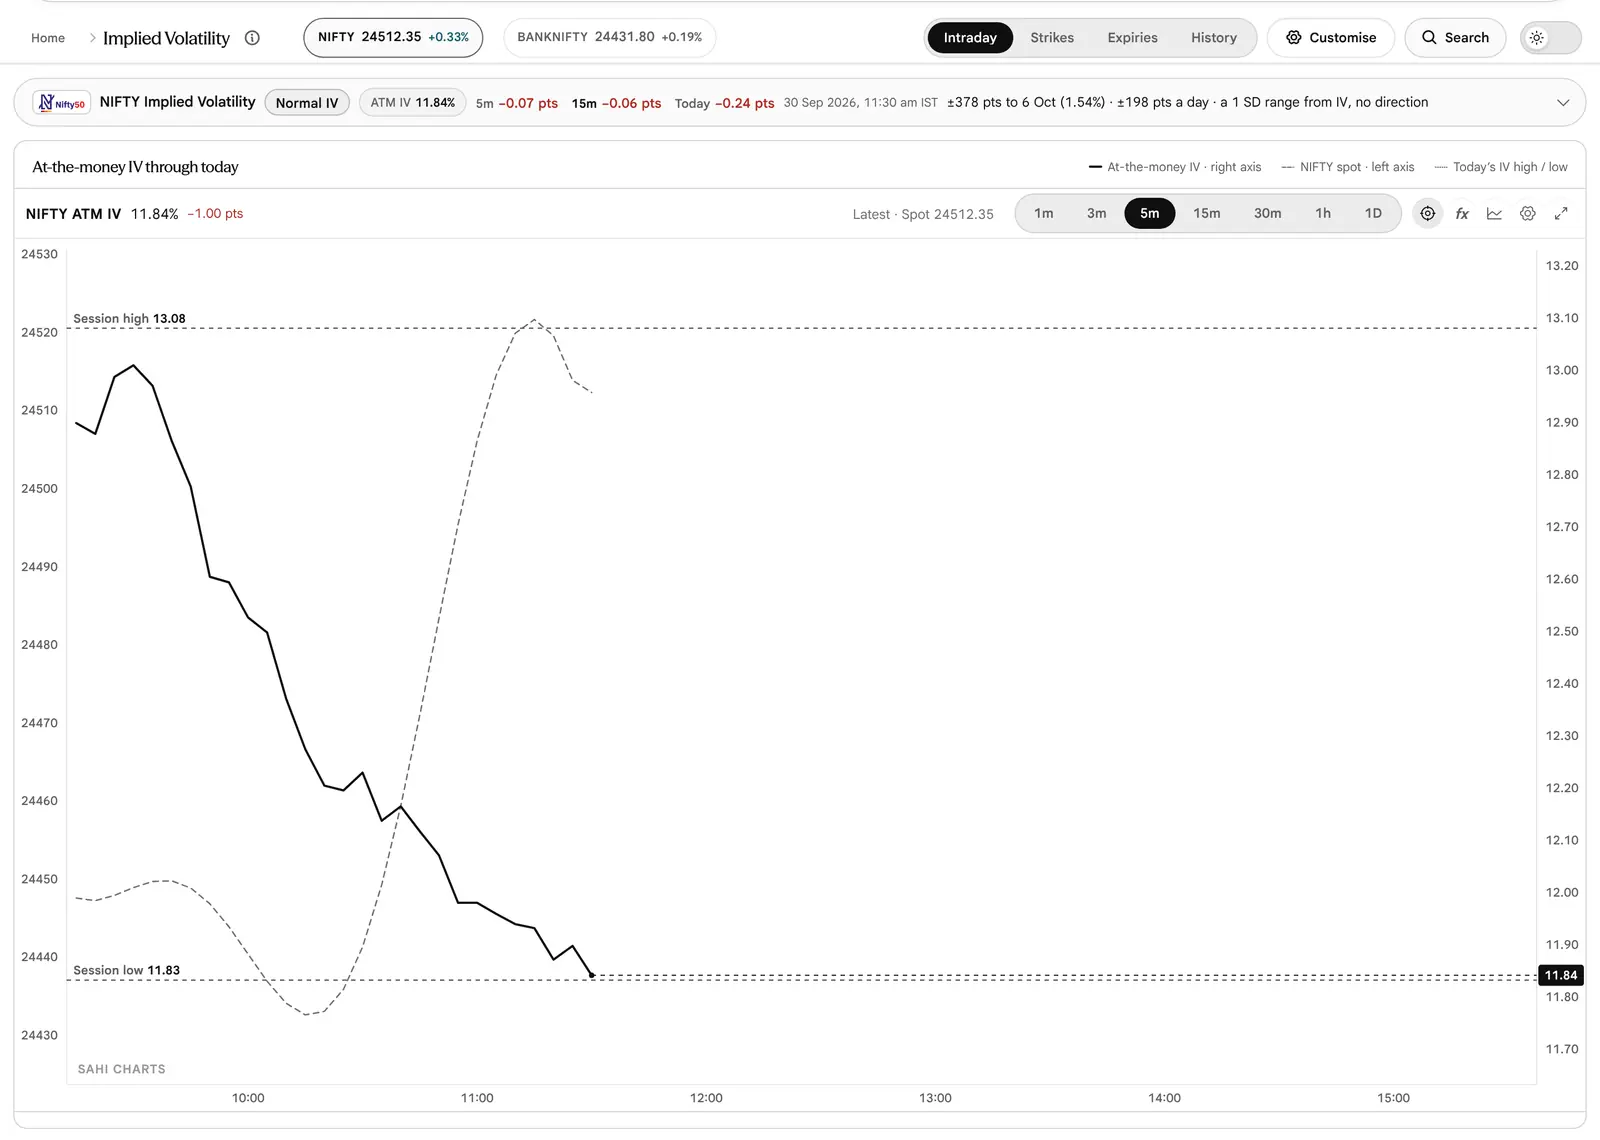
Look at: the insight row under the page bar. It carries the verdict and the changes; the answers behind it open from the arrow at the end of the row, and the chart below is the evidence. (Picture taken before the page changed on 19 October 2026: picture not retaken.) -
Open the insight: the four answers in four lines
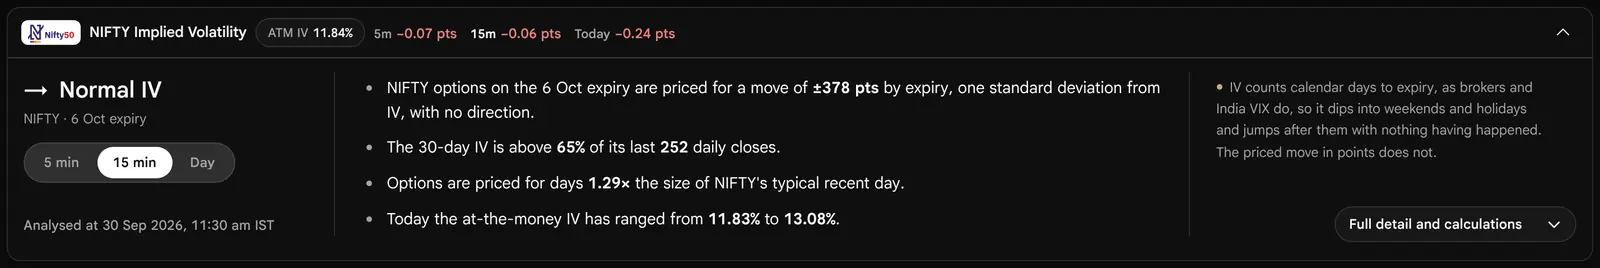

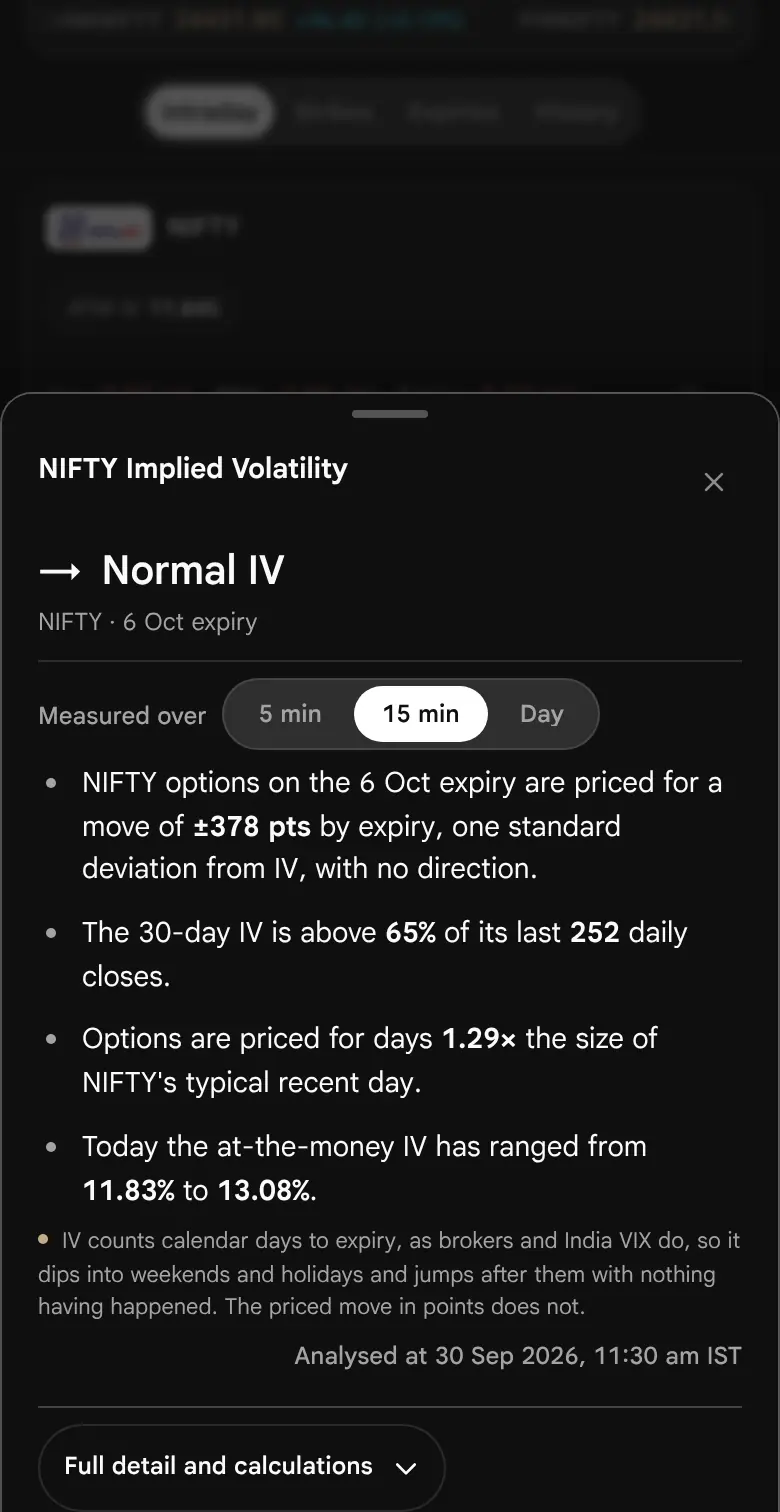
Look at: the order. Line one says how far, line two says high or low against the year, line three says dear or cheap against recent days, line four says how today ranged. The ATM IV in the chip is the percentage they are all built from. Press the arrow at the end of the insight row. The first line reads ±378 pts (1.54%) by expiry, with the range 24135 – 24890 in the detail panel. That is the move the option prices are paying for by expiry, one standard deviation either side of spot. It names no direction. The reason for this figure is in The priced move in points.
-
Read the third line: dear or cheap against recent days
The line Options are priced for days 1.29× the size of NIFTY’s typical recent day sets the priced move per day, ±198 pts, against the underlying’s actual days over the last 20 sessions, ±154 pts. Options priced for bigger days than the market has been having are dear against recent history; smaller, cheap. The rule is in Per day, and against actual days.
-
Read the second line: high or low against its own year
The line The 30-day IV is above 65% of its last 252 daily closes is the IV Percentile, IVP 65; the detail panel adds IV Rank 29. At 80 or more the verdict reads High IV, at 20 or less Low IV, and between them Normal IV. See Against its year.
-
See how it moved today
The insight row carries three small changes: 5m, 15m and Today. On the picture they read −0.07 pts, −0.06 pts and −0.24 pts. Open the insight for the verdict in words and the working behind every figure (The insight row).
-
Open the view that answers your next question
Intraday shows IV through today (its chart is titled ATM IV today). Strikes shows IV at each strike (IV by strike). Expiries puts the live expiries side by side (Compare expiries). History shows the past year (30-day IV history). A short guide to choosing is in The screen at a glance.
Which Parts to Read
New to options: read this part, then What implied volatility is, The screen, the four parts of A, Mistakes and traps and the Glossary. Already trade options: go to calendar days, the forward, the Expiries view, routines and the limits.
The Screen at a Glance
What is on the screen, and which part do I read first?
The page is one column, top to bottom, and the order is the order of reading. One part sits above every view and never changes with it: the insight row, which opens into the four answers. Under it is one card for the view you chose, which on a desktop runs to the bottom of the window. Choosing a view changes only that card.
- Page barThe four views Intraday, Strikes, Expiries and History, and Customise (on the Expiries view the expiry selector stands in its place).
- Insight rowThe verdict in words, the at-the-money IV, the 5m, 15m and Today change, one short line of the priced move, the time of the data, and an arrow that opens it.
- Four answersOpened from the arrow at the end of the row: the priced move to expiry, where the 30-day IV sits in its year, the priced day against actual days, and how today ranged. The detail panel works each one out.
- The view cardOne chart or table, with a short title: ATM IV today, IV by strike, Compare expiries or 30-day IV history. On a desktop its key sits in the card head and nothing sits under the chart; the Strikes and History views continue below with four figures, and Intraday with the straddle split.


| View | The question it answers | Where it is explained |
|---|---|---|
| Intraday | How has the IV moved today, and was it the price, the IV or time that moved the straddle? | Intraday, the straddle split |
| Strikes | Which strikes cost more in IV, and how has that changed since the open? | Strikes |
| Expiries | Which expiry is paying for the most movement each day? | Expiries |
| History | Is today’s IV high or low for the past year, and how does it compare with actual moves? | History |
Three words on the screen are worth knowing now. 1 SD is one standard deviation, the size of the priced move. ATM IV is the IV at the forward, the centre of the option prices. IVP is IV Percentile. Each is defined in the Glossary and in the part that uses it.
The question each topic answers
- What is the at-the-money IV, how is it measured, and when does the page refuse to give one?
- How many index points is the market paying for, and how is the percentage turned into them?
- Is one day of this expiry priced above or below the days the underlying has really had?
- Is today’s level high or low for this underlying, measured against its own past year?
Answer One: the At-the-money IV
What is the at-the-money IV, how is it measured, and when does the page refuse to give one?


The first answer is the at-the-money IV of the expiry the page is reading. It sits in the insight row as the chip ATM IV 11.84%, and the first tiles of The reading in the detail panel give it in full: ATM IV now 11.84%, Since the open −1.00 pts, and Today’s range, where the day’s readings have run from 11.83% to 13.08%. The tile since the open is the latest reading minus the first reading of the session, in IV points (one point is one percentage point of IV). It takes a direction colour only when the change is larger than 0.005 of a point; anything smaller cannot alter a figure printed to two decimals.
Why “at the money” Means the Forward Here
An option is at the money when its strike sits at the centre of the prices. That centre is not spot. It is the forward: where the option prices put the underlying at expiry, which is spot plus the cost of carrying it until then. At 6.5% a year and 30 days the two differ by about half of one per cent, which on NIFTY is more than two strikes. The page works the forward out from the Call and Put prices themselves (put–call parity), so it needs no futures price. On the picture the tile says “At the forward, 24539”: the IV 11.84% read at the forward 24539, while spot is 24512.35. The forward, not spot explains why this matters.
How the Figure Is Measured
- The page takes the one-minute snapshots of the day for this expiry only. A snapshot of another expiry is left out, so a change of expiry is never shown as a change of IV.
- It finds the forward, then reads the straddle (the Call plus the Put) at the two strikes either side of it. One IV reprices both legs of a strike, so it inverts the straddle and not the two legs separately.
- It blends the two strikes to the forward itself, in total variance (IV squared times time), so the line moves smoothly when the price crosses a strike instead of stepping.
Each price is the last traded price of the leg, not the midpoint of bid and ask, and the model is Black–Scholes in its forward form with a fixed 6.5% rate. A leg that barely moves with volatility is not used: a strike whose premium changes by less than ₹0.10 per vol point cannot show an IV, because one tick of ₹0.05 would then move the solved figure by half a vol point or more.
When the Page Gives No Number
The page never shows a zero for a reading it could not make. It names the cause in these exact words:
| Cause | What the page says |
|---|---|
| The expiry has passed | This series has settled, so its option prices no longer describe a live contract. |
| No time is left | The expiry has passed at this instant, so there is no time left to imply a volatility over. |
| No centre | No forward could be recovered from this ladder, so there is no centre to measure the volatility at. |
| Too few strikes | Too few strikes carried a price at this instant to place the forward on the ladder. |
| No prices | No strike on this ladder carried a price at this instant. |
| Prices that do not identify an IV | Strikes were priced but none of the quotes moved enough with volatility to identify one. |
When some minutes fail and others do not, the opened insight says so in one line: “N of M snapshots gave no reading” with the commonest cause. Those minutes are gaps in the line, never dips to zero.
Answer Two: the Priced Move in Points
How many index points is the market paying for, and how is the percentage turned into them?

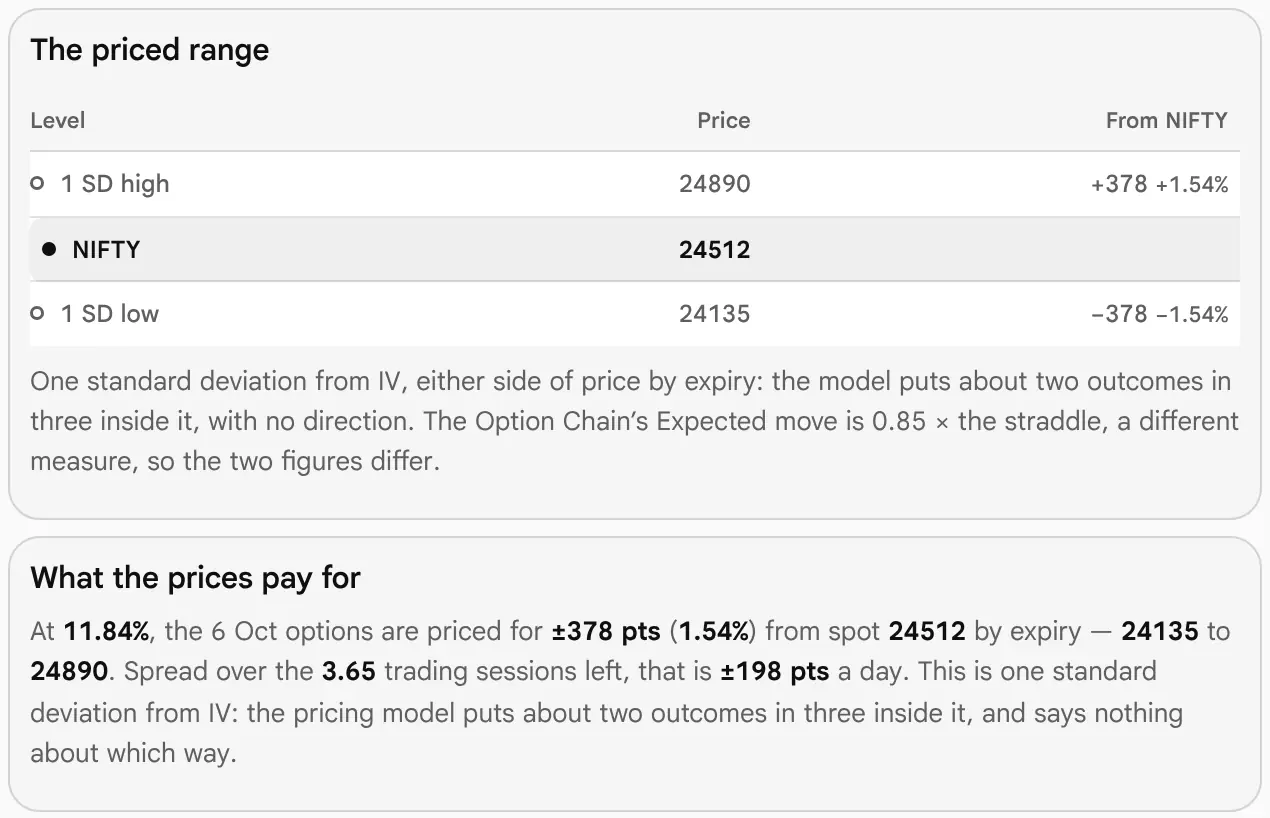
Implied volatility is a yearly figure, and almost nobody holds an option for a year. The conversion to the move that matters is one line:
24512.35 × 11.84% × √(6.174 ÷ 365) = ±378 ptsThe days left are calendar days from the time of the reading to the close of the option market on the expiry date. From 11:30 on Wednesday 30 September to 15:40 on Tuesday 6 October is 6 days, 4 hours and 10 minutes, which is the 6.174 in the working. (The note printed under this calculation in the detail panel reads “3:40 pm close on expiry (3:30 pm for expiries before 3 Aug 2026)”, which matches the figure. The 15:40 close itself is explained in What we have not verified.) The result, ±378 pts, is 1.54% of spot, and the range 24135 – 24890 is spot less and plus that move (the 1 SD low and the 1 SD high of the priced range). The range is centred on spot, not on the forward.
Why a Square Root
Volatility grows with the square root of time, not with time. Four times the time gives twice the move; nine times the time, three times. A month-out option is therefore not worth four weekly options, and the move to the 27 October expiry, about four times as far away as the 6 October one, is not four times larger. The Expiries view shows it side by side: the move to 13 October is 597 points against 378 to 6 October.
What One Standard Deviation Means
The result is one standard deviation, shown as “1 SD”. The pricing model puts about two outcomes in three inside the range and says nothing about which side. Three cautions belong with it.
- It is a property of the model, not a count of past days. It is what the option prices say, not what happened.
- It is symmetric, and the true distribution is not. It is a good guide near the money and a rougher one in the tails. A move of two standard deviations is not rare enough to ignore.
- It describes the move to expiry. For today, use the per-day figure (answer three).
The Straddle Beside It, and the Option Chain’s Expected Move
The Expiries view prints the price of the at-the-money straddle in its last column, ATM straddle, here ₹301.25, strike 24550 for the 6 Oct row: the Call plus the Put at the strike nearest the forward. One priced move is about 1.25 times the straddle (on the picture 378 against 1.25 × 301.25 = 376.56). The Option Chain and the Straddle page print an “Expected move” of 0.85 times the straddle, here 256.06, which is a narrower band; the chain’s tile reads “0.85 × straddle”. This page’s figure is worked from the IV instead, and the page says so: it is 1 SD, from IV. (The chain’s own “1 SD to expiry” tile, labelled “From ATM IV”, is this same figure.) Both are correct for what they say. They are different bands, so read the basis printed beside each number, not the word “move”. (We have not found a study behind the 0.85; it is the chain’s own convention.)
On the Last Session
When one session or less is left, the whole remaining move belongs to today. The sentence then says This is the last session before expiry, so all of it is today’s, the insight row words the figure as left today, and the calculation is titled Priced move left today (see the expiry-day picture). The move to expiry keeps its title and reads the same.
Answer Three: Per Day, and Against Actual Days
Is one day of this expiry priced above or below the days the underlying has really had?
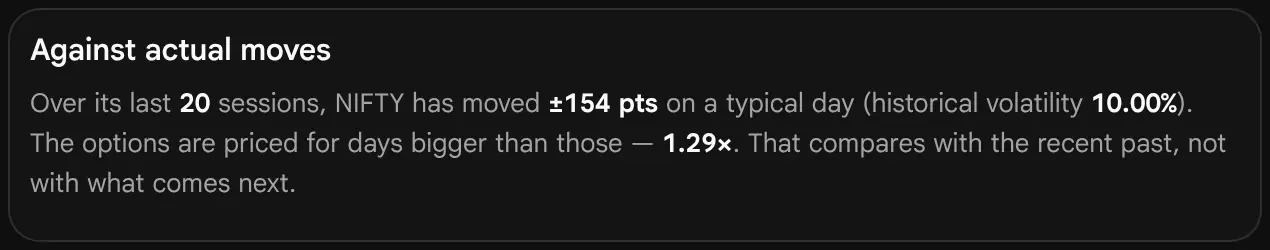
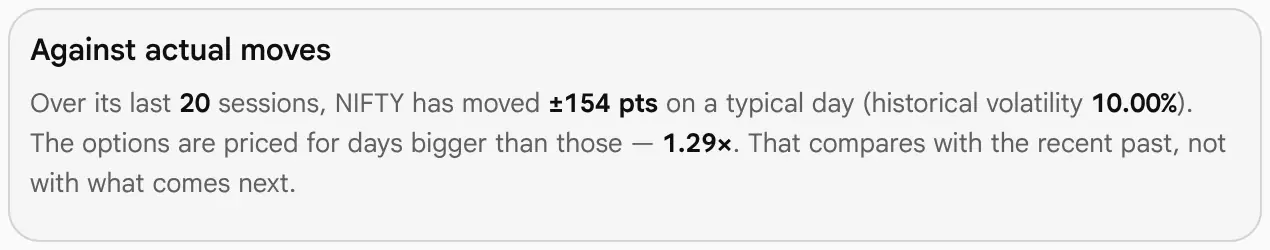
This answer is the question a trader brings first: are these options dear or cheap? It does not compare an IV with another IV. It compares one priced day, in points, with one actual day, in points.
The Priced Day
377.5 ÷ √3.649 = ±198 ptsWeekends and holidays carry none of the move: the market is shut on them.The sessions left are counted on the exchange calendar: the unspent part of today (11:30 to 15:40 is 0.649 of a session) plus every whole session up to and including the expiry. From Wednesday 30 September to Tuesday 6 October these are Thursday 1 October, Monday 5 October and Tuesday 6 October, so 3.649. Friday 2 October is a holiday in the app’s own calendar and the weekend is shut, so none of them is counted (not checked against an exchange calendar). The move per day is ±198 pts, which the insight row also prints beside the move to expiry: “±378 pts to 6 Oct (1.54%) · ±198 pts a day”.
The Actual Day
HV 10.00% ÷ √252 = 0.6300% a day → 24512.35 × 0.6300% = ±154 ptsClose to close, so overnight gaps count: an option is paid for those too.Historical volatility over 20 sessions is the figure every volatility tool quotes. Twenty sessions is one trading month, long enough to be steady: a standard deviation from 20 returns is uncertain by about 16 per cent, where five returns would be uncertain by about 35. The page converts it to points at today’s spot so that the two days are measured in one unit. It needs 21 daily closes; without them the cell says No daily closes to compare with (and Reading daily closes… while they are still being read).
The Word
198 ÷ 154 = 1.29A 20-session figure is itself uncertain by about ±16%, so smaller gaps are not called either way.| Ratio of priced day to actual day | What the page says |
|---|---|
| 1.2 or more | Priced for bigger days than recent ones |
| Between 0.83 and 1.2 | Priced for days like recent ones |
| 0.83 (one over 1.2) or less | Priced for smaller days than recent ones |
The ratio is worked from the whole numbers on screen, so you can redo it with a calculator: 198 divided by 154 is 1.29, at or above the 1.2 line, so the word is bigger. The page names a side only when the gap clears the uncertainty of a 20-session measurement. The sentence describes prices. It does not say what to do, and it compares with the recent past, not with what comes next.
The Previous Close, and Why It Is in Points
The Today section of the detail panel says the priced day has gone from ±204 pts at the previous close to ±198 pts, which is the same priced day worked out at the previous session’s last reading. It is the clock-free way to say whether options got dearer today. IV itself cannot say it: on a Monday it jumps several points above Friday’s close with nothing having happened, because IV counts the weekend’s calendar days and the market does not move on them. Points per session carry no such calendar. The whole of this is in Calendar days.

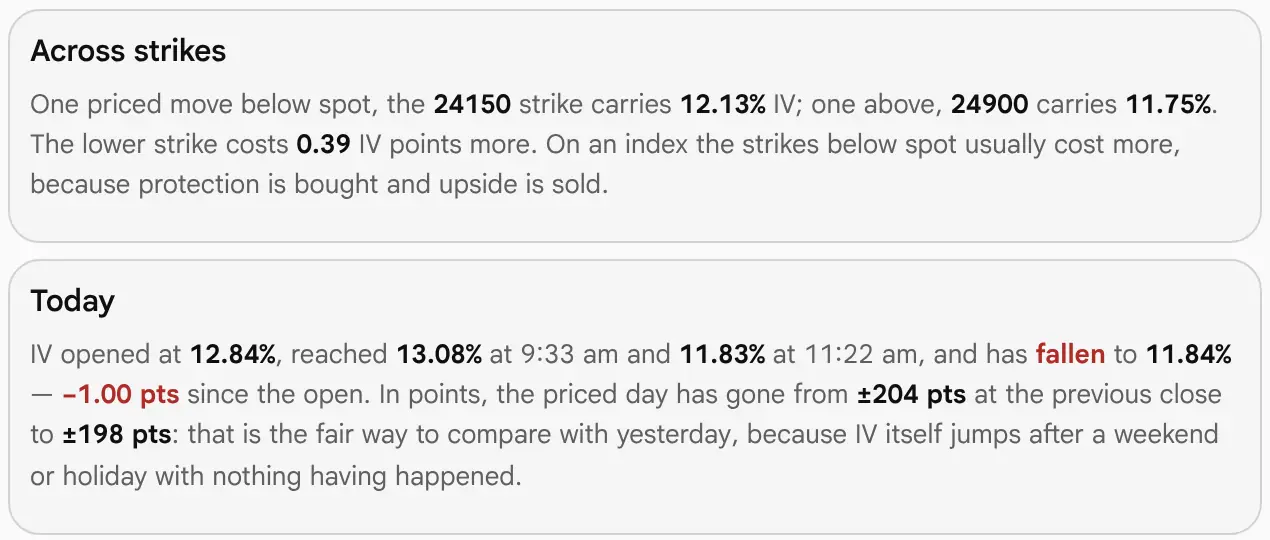
On the Last Session
With one session or less left, the figure is titled Priced move left today and is the whole of today’s remaining move. It then shrinks through the afternoon, and set against a whole actual day it will often read smaller. That is the arithmetic of a few hours left, not a cheap market.
Answer Four: Against Its Own Year
Is today’s level high or low for this underlying, measured against its own past year?
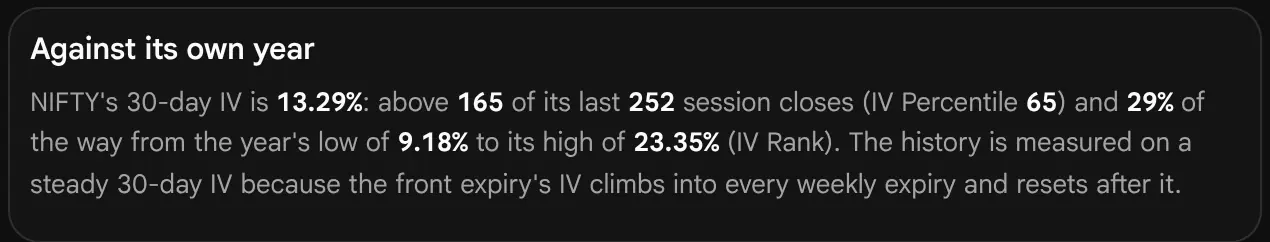
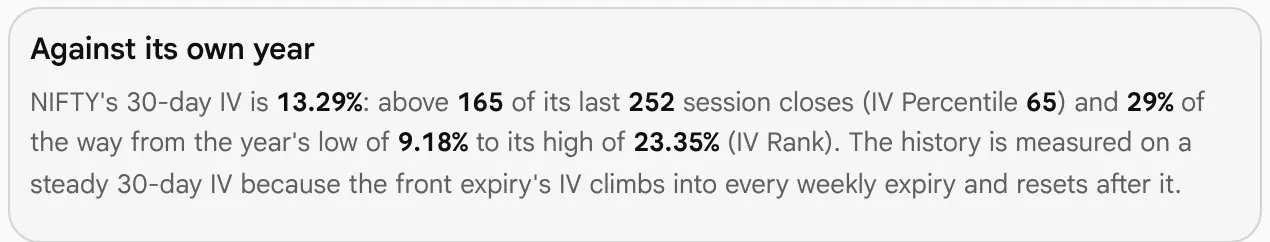
A level means little until it is set against its own history. The page does that with two numbers that traders know by name.
| Number | The rule | On the picture |
|---|---|---|
| IV Percentile (IVP) | The share of the last 252 closes of the 30-day IV that closed below today’s. Shown from 60 sessions of closes. | 165 of 252 below 13.29% = 65 |
| IV Rank | (today − year low) ÷ (year high − year low) × 100. Shown only with a full 252 sessions. | (13.29 − 9.18) ÷ (23.35 − 9.18) × 100 = 29 (the page works from the unrounded inputs) |
The Words
The verdict in the insight row reads High IV when the printed IV Percentile is 80 or more, Low IV at 20 or less, and Normal IV between (the detail panel prints the same rule under How the verdict is decided). The test is made on the whole number you see, so a printed 80 never reads Normal. IV Percentile leads because it uses every day of the year. IV Rank rests on only two days, the highest and the lowest close, so one spike can hold it down for a whole year.
Why the Year Uses a 30-day IV
The IV of a weekly expiry climbs through every week into expiry and resets after it. A year of those readings would rank the day of the week, not the volatility. So the year is measured on a steady 30-day IV, solved every session from NSE’s F&O closing prices. The rule for today’s figure:
- Leave out any expiry with fewer than 2 days left.
- Blend the nearest expiry on each side of 30 days, linearly in total variance (IV squared times time).
- If no expiry reaches 30 days, the furthest one stands in. If every expiry is past 30 days, the nearest one stands in.
- The furthest expiry must be at least 14 days away. Otherwise there is no 30-day IV.
On the picture the three expiries are “6 Oct 11.84% (6d), 13 Oct 12.82% (13d), 27 Oct 13.29% (27d) → 13.29%”. None reaches 30 days, so the furthest, 27 Oct, stands in and the 30-day IV is its own at-the-money IV, 13.29%. The BANKNIFTY picture lists one expiry, 27 October at 27 days, so it stands in too and the 30-day IV is its own 14.45%. A true blend needs one expiry on each side of 30 days (Expiries).
The Options Scanner ranks the same 30-day IV against the same file, so the two pages print one IV Rank.
How the Year of Closes Is Built
The year is a file of one 30-day IV per session for each NSE F&O underlying. Each value is solved from that session’s closing prices in NSE’s F&O bhavcopy, with the same solve the page runs on today’s prices. The rules:
- Three expiries after the session. Each session reads the underlying’s three nearest expiries that fall after the session date. An expiry that settles on that day is never used, because it has no time left. These are the same three expiries the page tracks once the day’s expiry has settled.
- Expiry days have a reading. Because the settling expiry is skipped, an expiry day (a NIFTY Tuesday, for example) still has an expiry at least 14 days away, and so a value. Earlier builds counted the settling expiry, and those days were empty.
- The same blend. The three expiries are blended to 30 days by the rules above.
- A contract that did not trade has no close, and it is left out.
On the live page the file now runs from 15 September 2025 to 16 October 2026, 270 sessions, and it includes the Sunday Budget session of 1 February 2026. IV Percentile and IV Rank use its last 252 sessions. The History card says how far the file runs (Closes to its last date). We did not rebuild the file ourselves (not verified). The year in this guide’s pictures is invented and ends earlier.
When the History Is Short

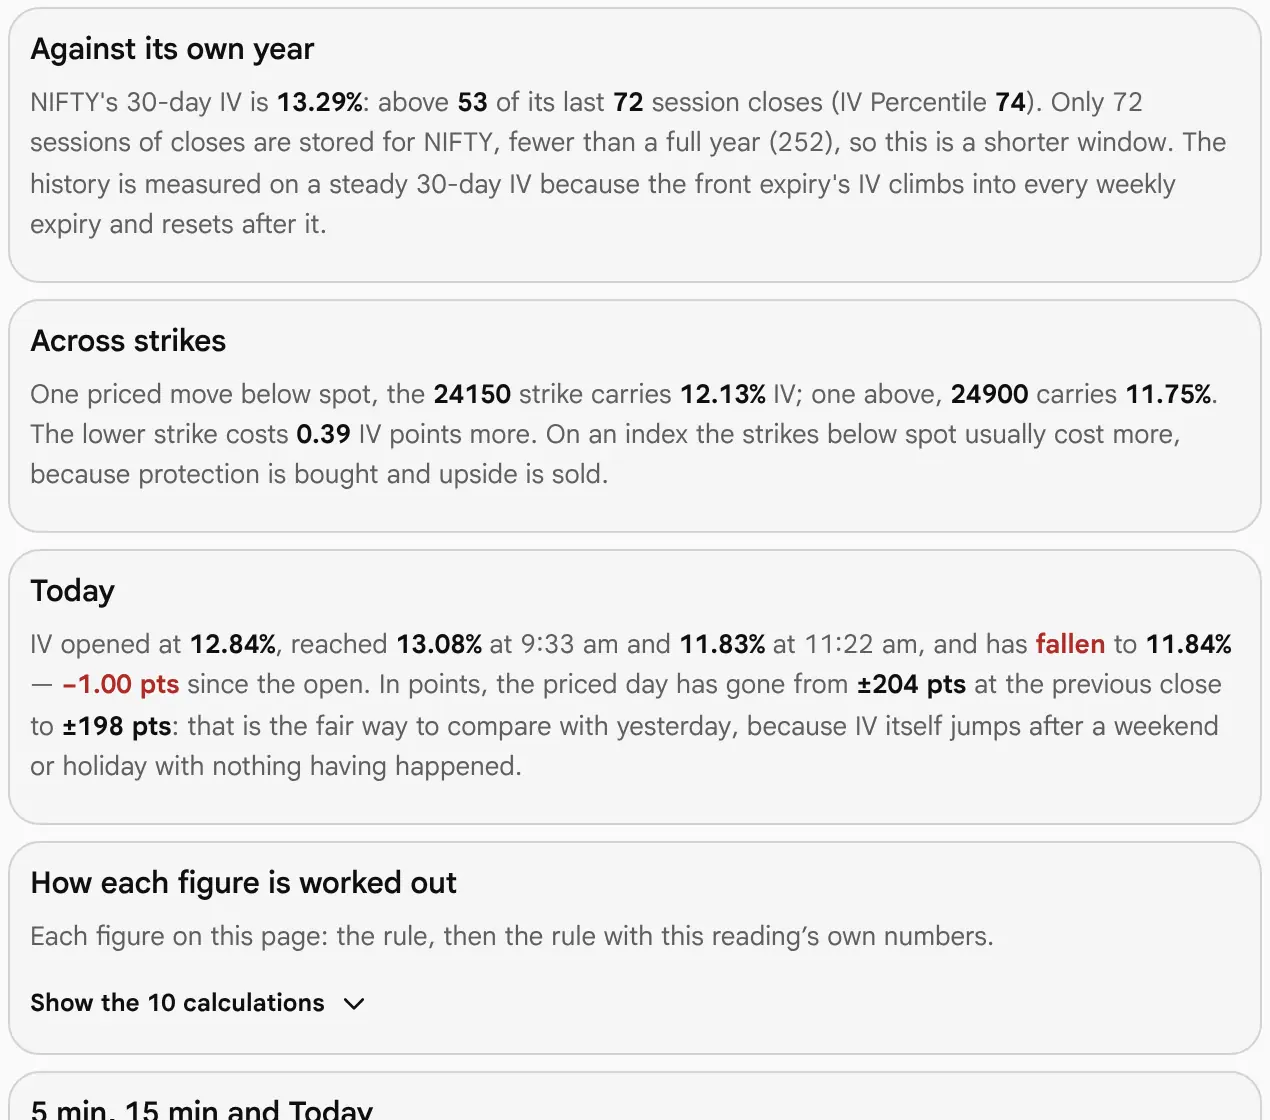
With fewer than 60 closes the page shows neither number. From 60 it shows the percentile, names the window (Only 72 sessions of closes are stored, fewer than a full year) and keeps the rank back until 252 sessions are stored, because a short window has almost certainly not seen a real spike. The History view then reads Needs a full 252 sessions under IV rank.


India VIX, for NIFTY Only
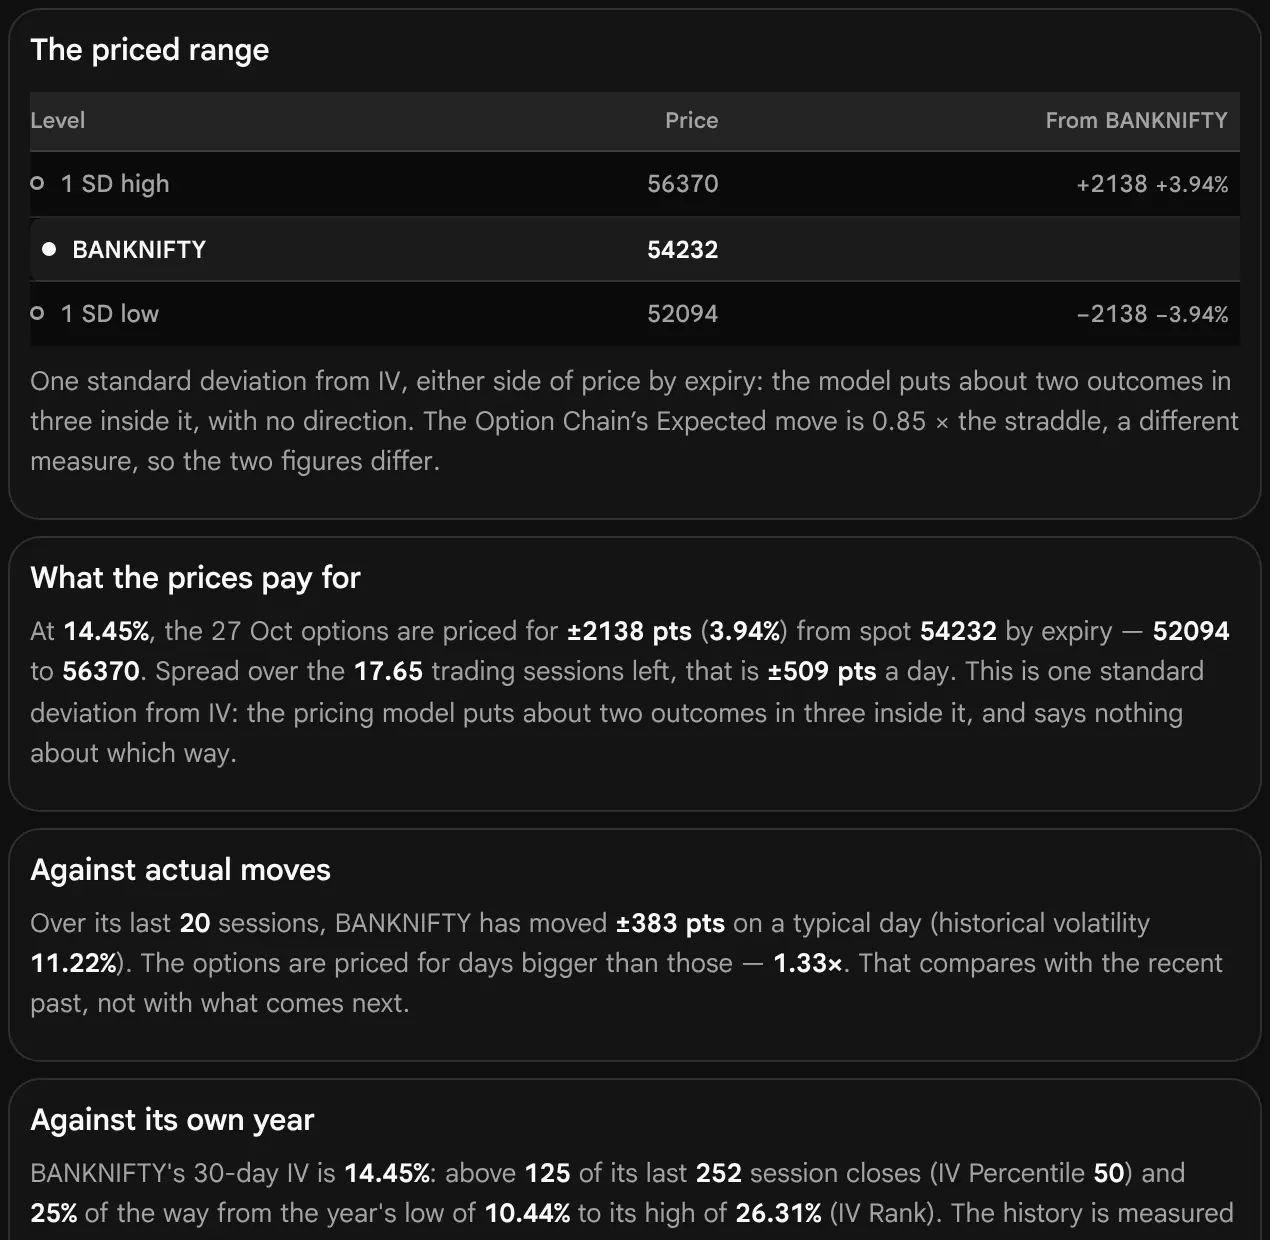
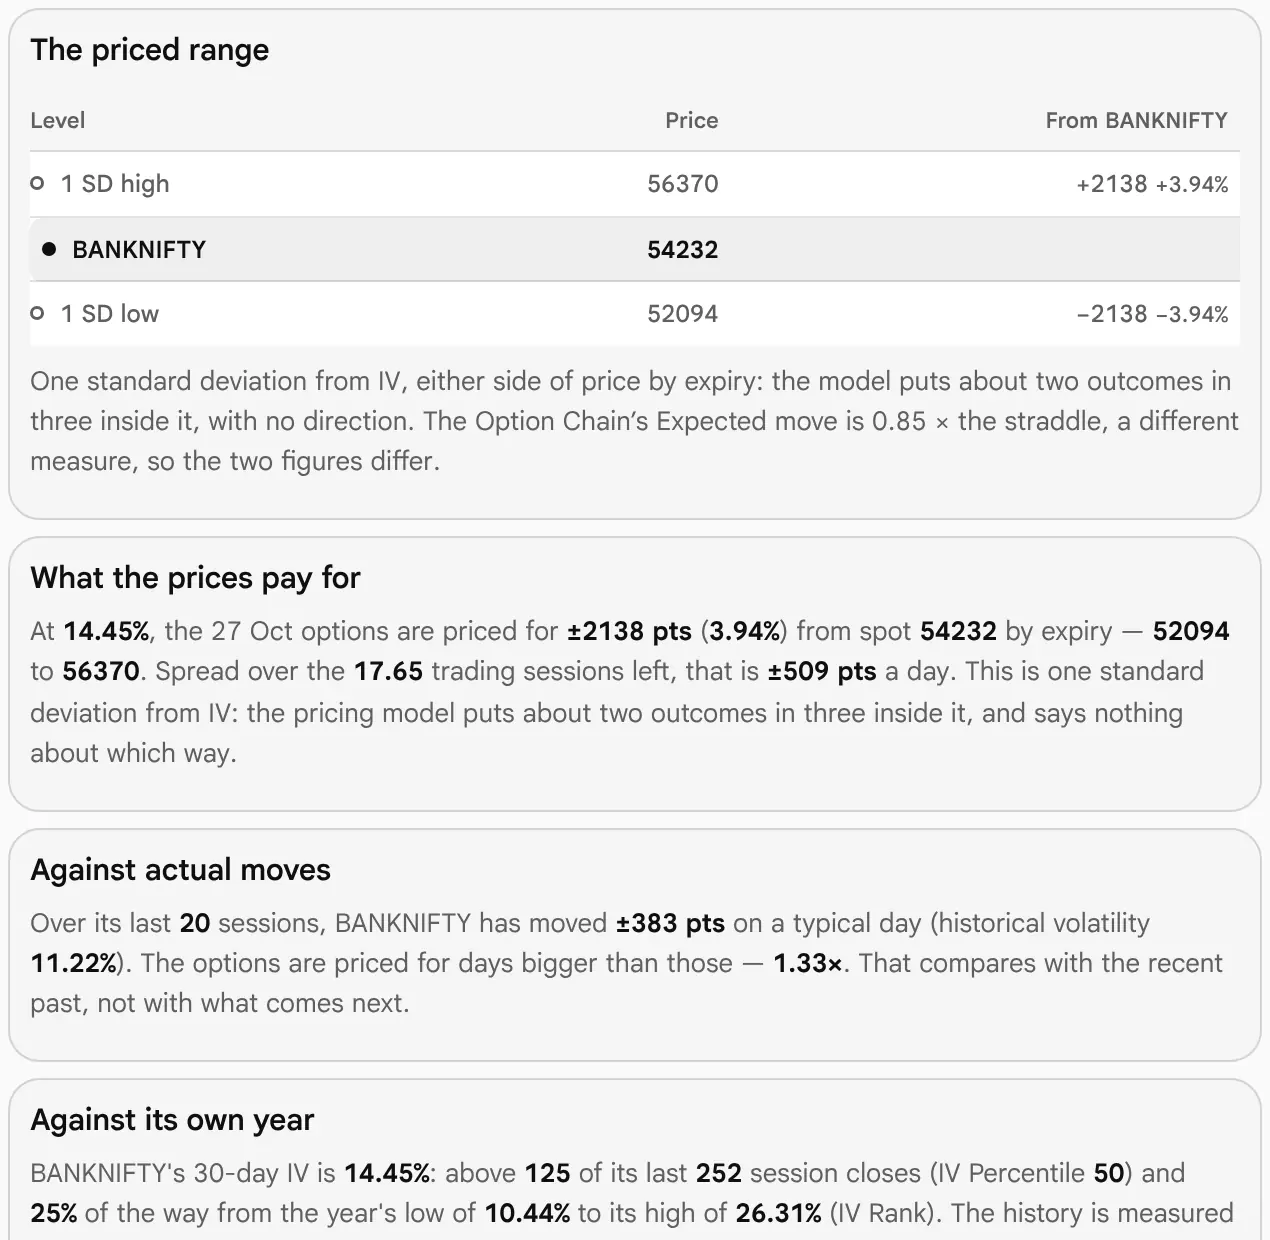
For NIFTY only, the detail panel’s calculations carry one more line, India VIX 13.41, +0.29 on the day, and the History view can draw it (Customise, History chart, India VIX). It is NSE’s own 30-day index, shown as a yardstick. It is built by a different method from the page’s at-the-money IV, from NIFTY’s near and next month options across all strikes, so, on the page’s own note, it usually reads a little above an at-the-money 30-day IV (not verified). The two are not the same number (why platforms differ).
The Insight Row
What does the thin row above the chart tell me, and what do its three small changes mean?


The row is built on the app’s shared insight card, with the content of this page. Reading it from the left:
- The verdict in a pill: Normal IV on the picture.
- The chip ATM IV 11.84%: the figure the three changes are measured on.
- 5m, 15m and Today: how far the at-the-money IV has travelled over the last 5 minutes, the last 15 minutes and today. They are the same three windows the Option Chain uses. Today is measured from the previous session’s close; when the archive holds no earlier session the key becomes Since 9:15 am and says where the day started instead.
- A one-line summary of the priced move: the move to expiry, the same move as a share of spot, and the move per day, as in “±378 pts to 6 Oct (1.54%) · ±198 pts a day”. On the last session it reads “±N pts left today” with the range. The note that this is one standard deviation, with no direction, is in the opened box and the detail panel.
- The time of the data, and at the end an arrow that opens the insight.
The Verdict Words
| Pill | When it appears |
|---|---|
| High IV, Normal IV, Low IV | From where the 30-day IV sits in its year: IV Percentile 80 or more, 20 or less, or between. The year decides first. |
| Above recent moves, Near recent moves, Below recent moves | Only when there is no year to use: the priced day against the actual day (ratio 1.2 or more, between, or one over that or less). |
| IV reading | Neither a year nor actual days could be used. |
| First reading, No reading, Series settled | One reading only so far; none yet; or the expiry has settled (the states). |


The pill is always in ordinary ink. It names a level, and the page does not colour a level of volatility: IV can rise in a falling market and in a rising one, so green or red would claim a direction the number does not carry. Only the three changes take a direction colour, and only when they clear a floor of 0.005 of a point.
A Change Is Not Zero When It Is Missing
If a window has no matching reading (the session is only a few minutes old, or the nearest snapshot is too far from the target), the page prints a dash and the reason, never “unchanged”. A 5-minute window will take a baseline up to about a minute and a half either side of five minutes earlier, and a 15-minute window two and a half. Beyond that it is reported as missing rather than quietly widened.
The Opened Box and Measured Over
What does the opened insight add, and what does Measured over choose?
The arrow at the end of the row opens it downwards. It holds, in this order:
- The verdict with the symbol and the expiry under it (“NIFTY · 6 Oct expiry”).
- Measured over: 5 min, 15 min or Day. It chooses which of the three changes in the row is set in bold. It never changes the verdict, which comes from the year.
- Four sentences. The priced move (“priced for a move of ±378 pts by expiry, one standard deviation from IV, with no direction”); the year (“The 30-day IV is above 65% of its last 252 daily closes”); the priced days against the actual days (“Options are priced for days 1.29× the size of NIFTY’s typical recent day”); and today’s range (“ranged from 11.83% to 13.08%”). Figures come first and are in bold. A sentence whose figure cannot be formed is left out, never printed as zero.
- The note. One short note at the right. It always says that IV counts calendar days; it adds how many snapshots gave no reading when some did not, and a note when more strikes started trading during the day or when snapshots of another expiry were left out.
- The time of the data, the number of one-minute readings today and the expiry, a small status label (Live updates while the card follows the newest reading, Saved reading when it does not; not tested), and the button Full detail and calculations. The label is not a promise of a continuous stream: the page works from the one-minute archive, so read the time of the data.
On a phone the box opens as a sheet over the page with a scrim, and a close button; Escape closes it on a keyboard and returns focus to the button that opened it.
The Changes, and the Shut Days
The three changes sit in the row: 5m, 15m and Today. With 15 min chosen the 15m change is in bold, here “11.84% at 11:30 am − 11.90% at 11:15 am = −0.06 pts” in the detail panel. Choose Day and the bold one is Today, whose baseline is the previous session’s close. After a holiday or a weekend part of that change is the calendar and not the market, and the note at the right of the box says so every time: IV counts calendar days to expiry, so it jumps after shut days with nothing having happened, and the priced move in points does not.
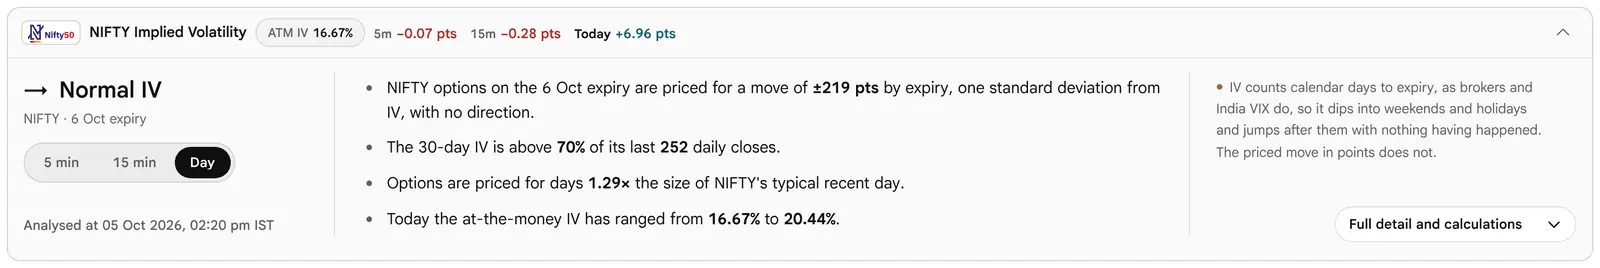
The date of the data is the date of the newest reading in the archive, not the clock of your device. Trust that time over any other label on the box.
The Detail Panel and Every Calculation
Where can I see every figure on the page worked out, step by step?


The button Full detail and calculations opens a side panel. Its job is to let you check every figure on the page. Its sections, in order:
- How the verdict is decided. Three steps: the year (IV Percentile with its rule, 80 or more reads High and 20 or less reads Low), the priced day against the actual day, and the result. The middle step decides only when the year is missing.
- The reading. Six tiles: ATM IV now (with the forward it was read at), since the open (with the opening time), today’s range (with the times of the high and the low), 1 SD to expiry, IV Percentile and IV Rank.
- The priced range. A short ladder: 1 SD high, the price, 1 SD low, each with its distance in points and per cent.
- Each answer in full. What the prices pay for, against actual moves, against its own year, across strikes, and today.
- How each figure is worked out, below.
- 5 min, 15 min and Today, with the two snapshots each change was taken between, for example “11.84% at 11:30 am − 11.91% at 11:25 am = −0.07 pts”.
- What this reading cannot see, and a short technical method: three steps of how the at-the-money IV is built.
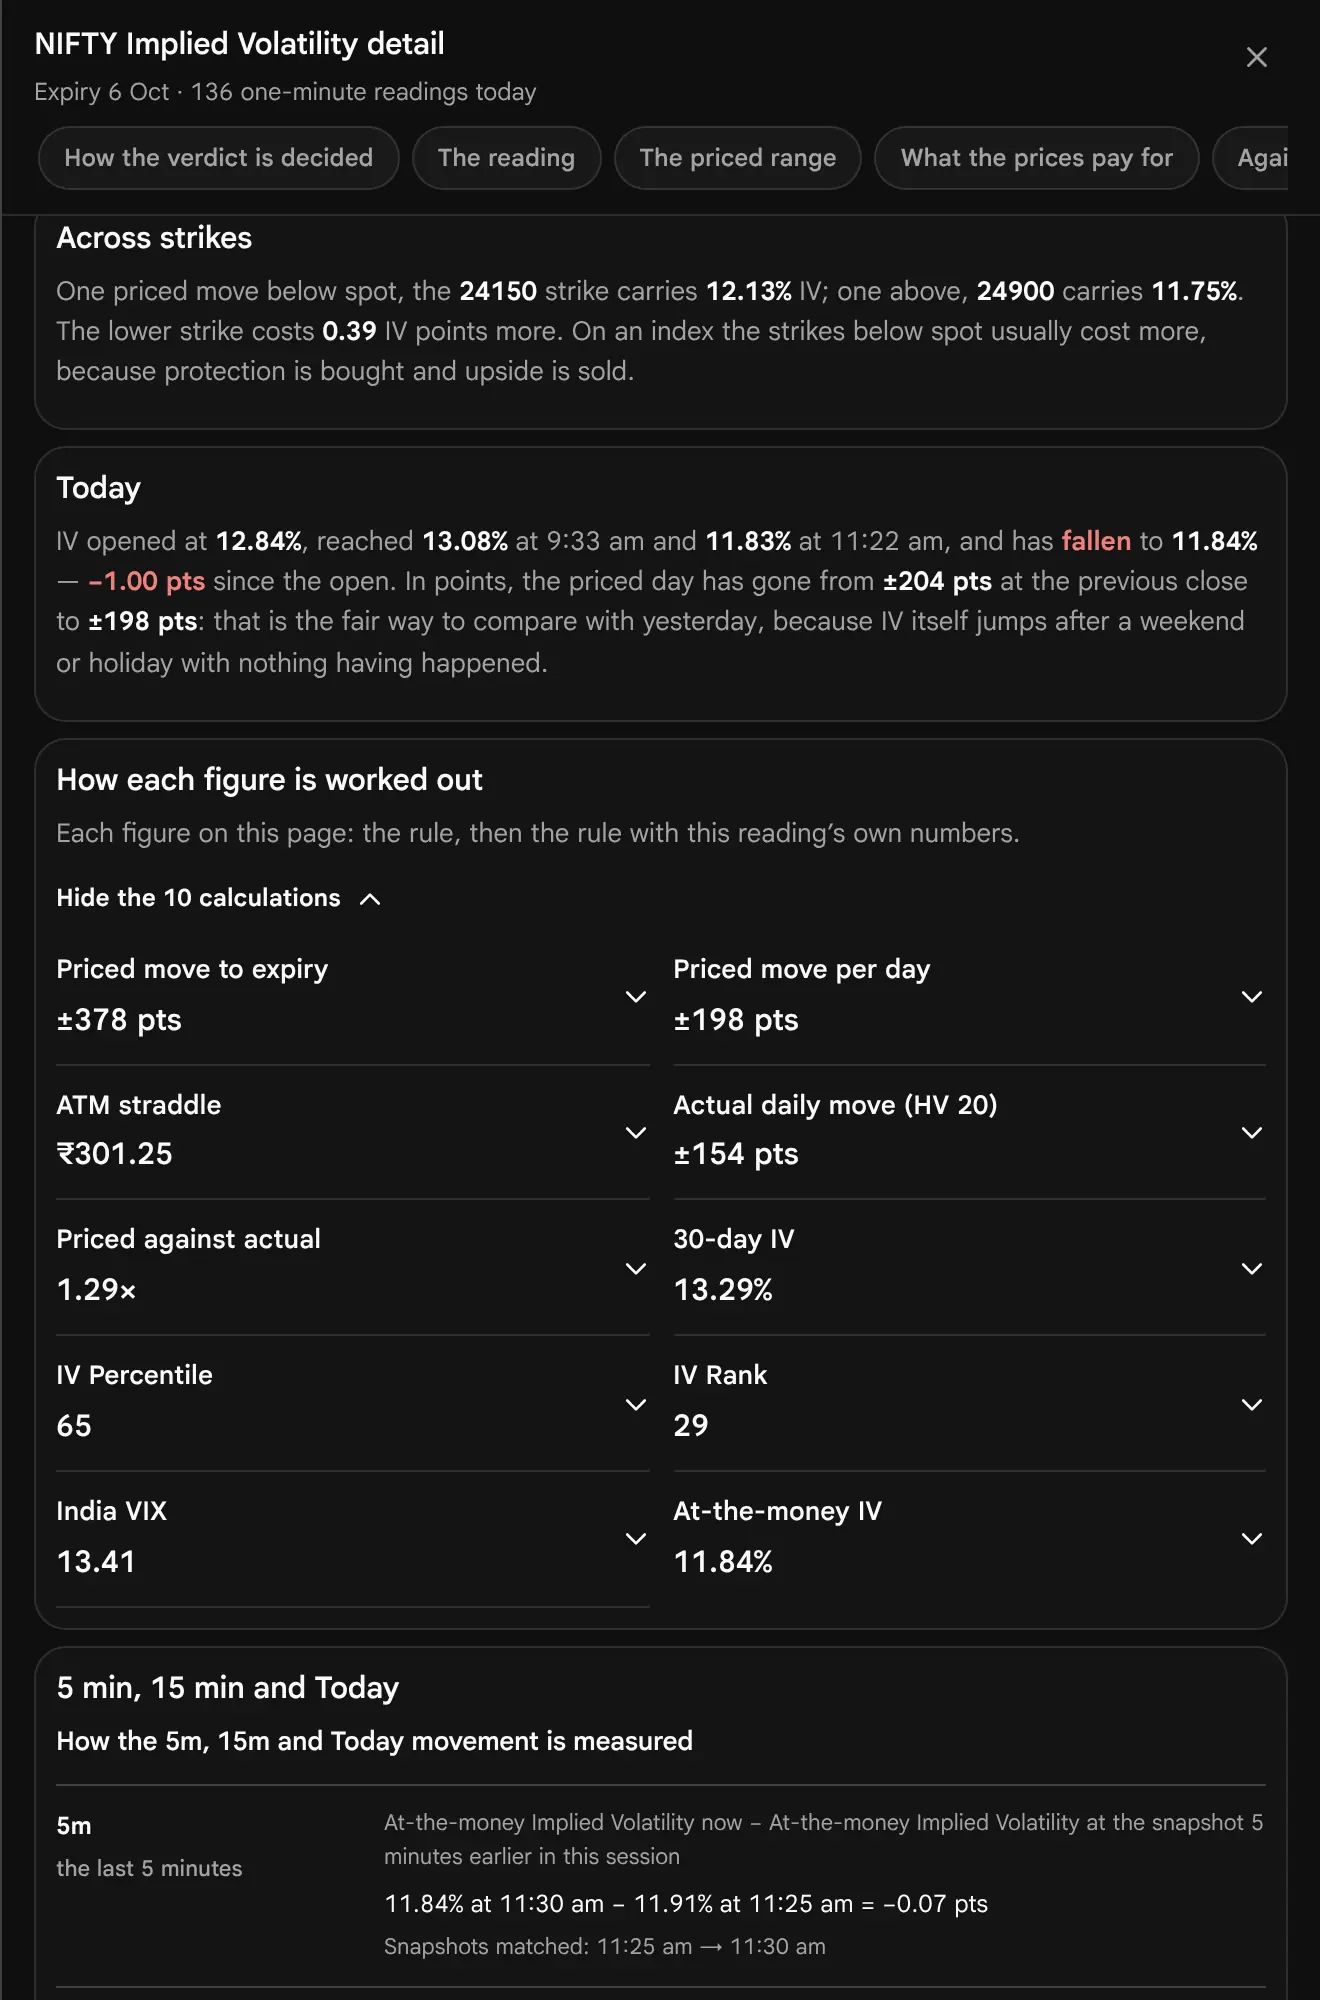
The Ten Calculations
| Calculation | Rule | On the picture |
|---|---|---|
| Priced move to expiry | spot × IV × √(days left ÷ 365) | 24512.35 × 11.84% × √(6.174 ÷ 365) = ±378 pts |
| Priced move per day | move to expiry ÷ √(trading sessions left) | 377.5 ÷ √3.649 = ±198 pts |
| ATM straddle | Call premium + Put premium at the strike nearest the forward | 24550 straddle = ₹301.25 |
| Actual daily move (HV 20) | standard deviation of the last 20 close-to-close returns × √252 | HV 10.00% ÷ √252 = 0.6300% a day → 24512.35 × 0.6300% = ±154 pts |
| Priced against actual | priced day ÷ actual day | 198 ÷ 154 = 1.29 |
| 30-day IV | the expiries around 30 days, blended; under 2 days left out; the furthest (at least 14 days) if none reaches 30 | 6 Oct 11.84% (6d), 13 Oct 12.82% (13d), 27 Oct 13.29% (27d) → 13.29% |
| IV Percentile | share of the last 252 sessions below today’s | 165 of 252 below 13.29% = 65 |
| IV Rank | (today − low) ÷ (high − low) × 100 | (13.29 − 9.18) ÷ (23.35 − 9.18) × 100 = 29 |
| India VIX (NIFTY only) | NSE’s 30-day index | 13.41, +0.29 on the day |
| At-the-money IV | read at the forward from the Call + Put at the two strikes around it | 11.84% at 24539, from 136 one-minute readings today |
Every working line is checked by the page’s own tests: each one redoes to the figure it prints. If you ever find a printed figure you cannot reproduce from its line, that is a fault worth reporting. A note under India VIX says it usually reads about a point above an at-the-money 30-day IV, because out-of-the-money Puts carry more IV; this is the page’s own statement and we have not checked it against NSE’s method (What we have not verified).
The question each topic answers
- How has the at-the-money IV moved through today, and against what price?
- The straddle is down. Was it time, did IV come off, or did the price move?
- Which strikes cost more in IV, and how has the curve moved since the open?
- Which expiry is paying for the most movement each day, and what is the 30-day IV?
- Is today’s IV high or low for the past year, and has it run above or below the moves the market actually made?
Intraday: the At-the-money IV Through Today
How has the at-the-money IV moved through today, and against what price?


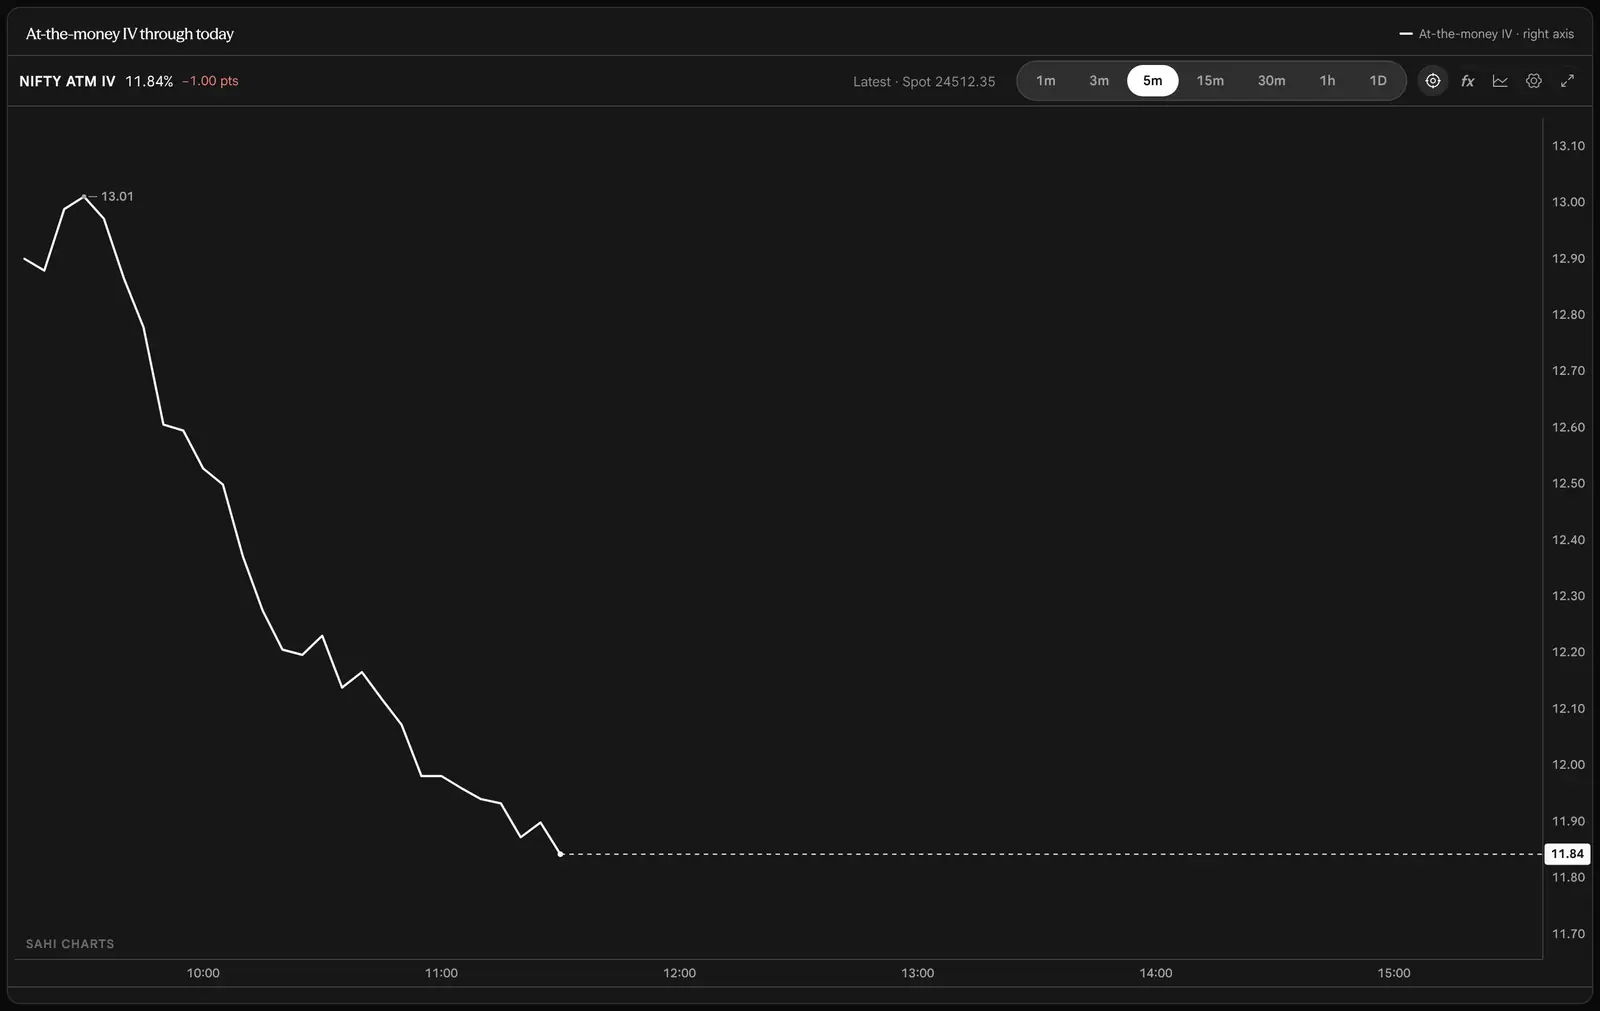
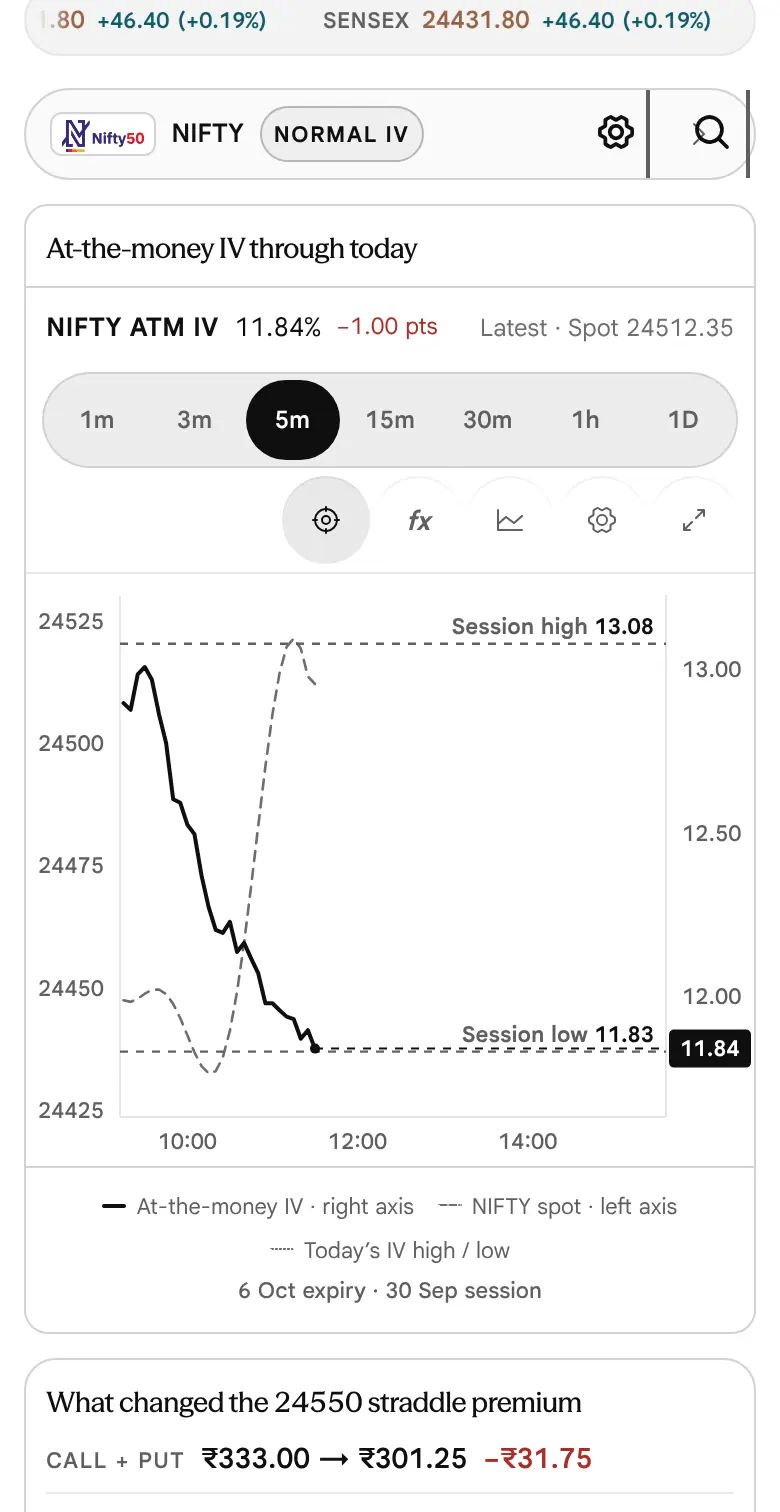
This is the view the page opens on the first time. The card is titled ATM IV today. It is built from the one-minute readings of the day, from the open to the latest, grouped into steps that you choose with the interval tabs (5 minutes at first). The chart is one line: the IV, in plain ink, on the right axis, in per cent to two decimals, with its latest value tagged on that axis. The spot of the underlying is dashed and uses the left axis, so you can see what the IV moved against. Two dashed rules mark the day’s highest and lowest IV, tagged Day high and Day low. The key sits in the head of the card (ATM IV, NIFTY spot, Day high / low), and nothing sits under the chart on a desktop. A phone adds the scope line under the plot, 6 Oct expiry · 30 Sep session; the detail panel counts the readings, 136 one-minute readings today.
How the Line Is Built
- One expiry and one session. Snapshots of another expiry, or of an earlier day, are left out. Without that rule the line would splice yesterday’s close in front of today’s open.
- Absent is not zero. A minute that gave no reading is a gap. The count of such minutes appears in the opened insight.
- At most 400 readings are drawn; if there were more, the oldest are thinned first, so the newest reading is never dropped.
- A reading needs two points to draw. With one reading the verdict says First reading (states).
The Chart’s Own Tools


The chart is kept simple, as on the PCR and Straddle pages. The row above it carries only three things: the interval as plain text tabs (1m, 3m, 5m, 15m, 30m, 1h, 1D), a crosshair switch and full screen. There are no indicators, no chart types, no chart settings and no drawing tools. The interval changes how many readings are drawn. It does not change the readings. The camera row under the chart zooms and moves along the time axis.

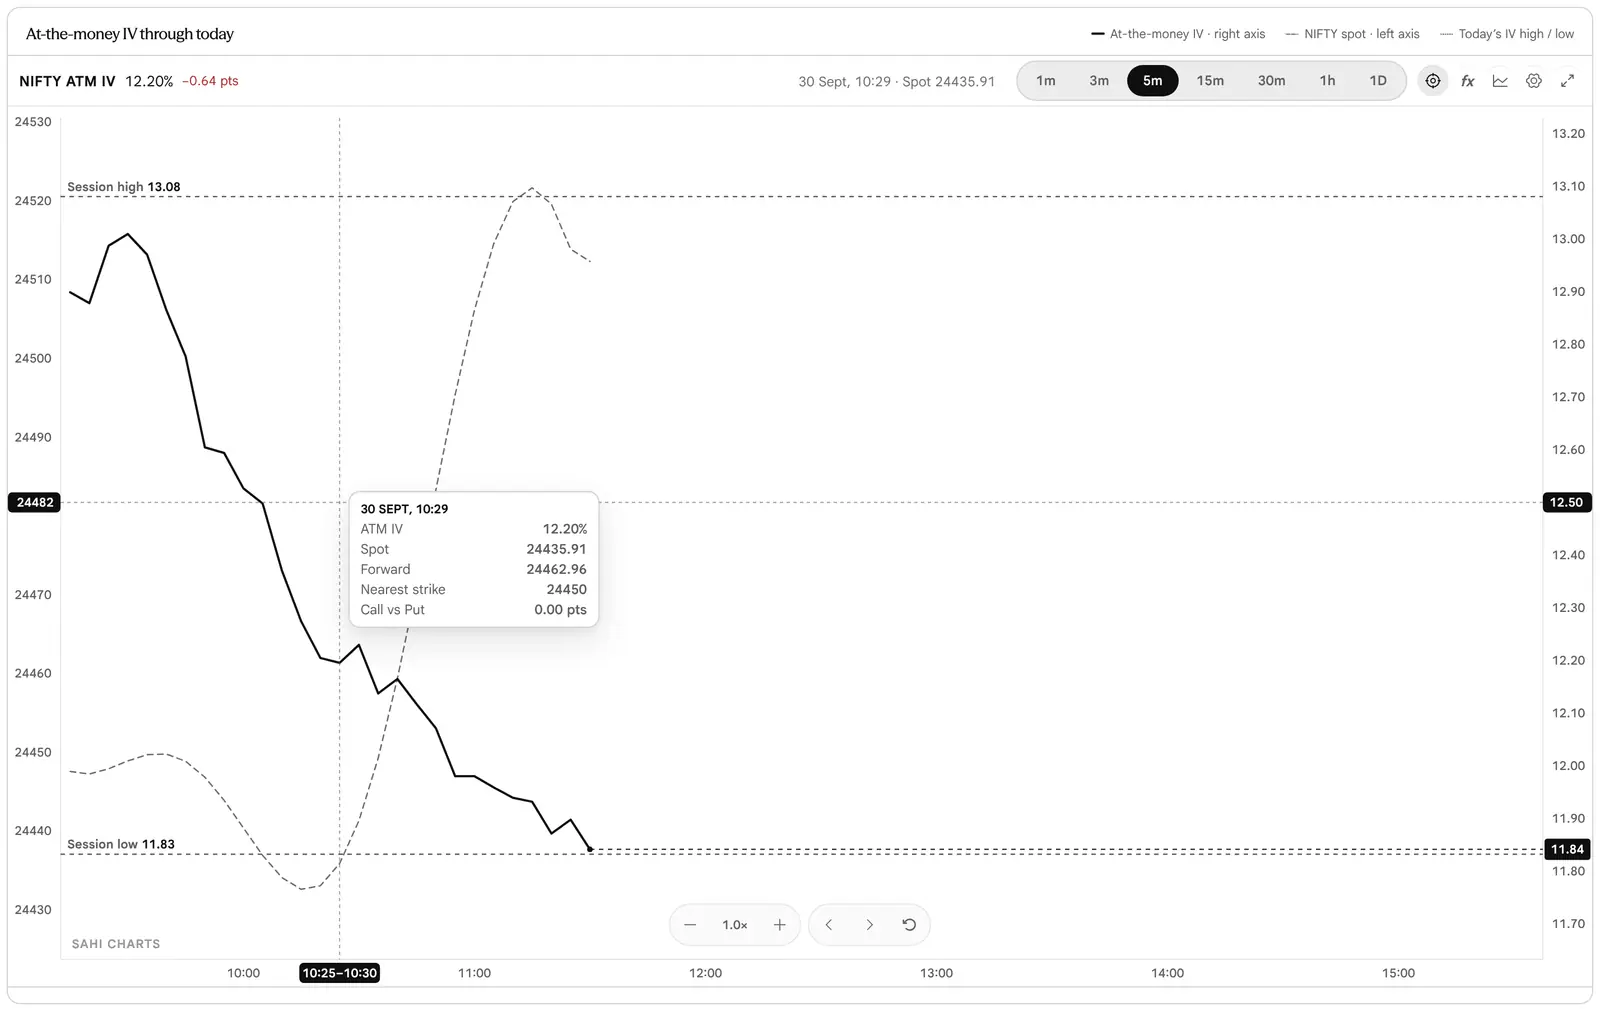
Reading It Without Fooling Yourself
- A falling IV line on a quiet day is often the calendar. IV is annualised over calendar days, so on the last days of a weekly expiry it can slide through the session with the market unchanged (Calendar days).
- A rising line is not bullish and a falling line is not bearish. It says options got dearer or cheaper, whichever way the price went.
- Check the left axis before you link the two lines. Spot may have moved only a few points over the day.
Where the Straddle’s Price Change Came From
The straddle is down. Was it time, did IV come off, or did the price move?
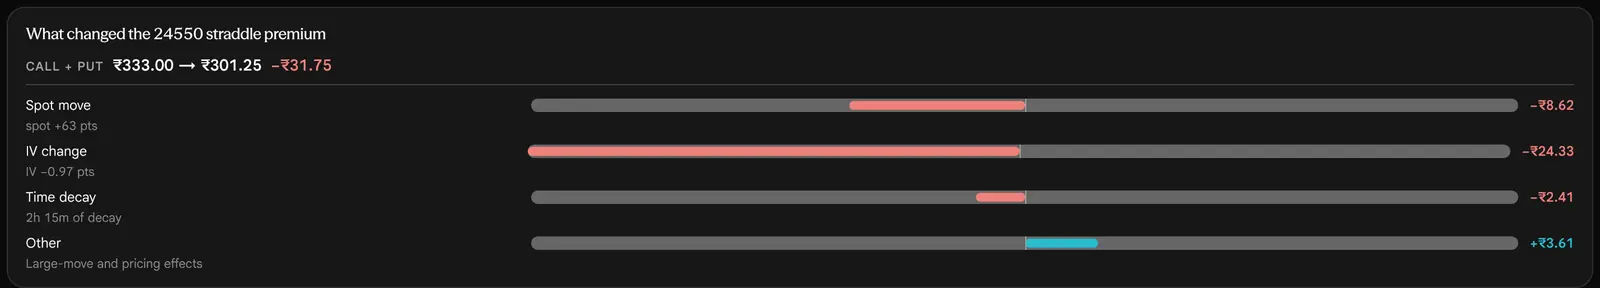
Under the Intraday chart, once there are two readings, a card answers the question sellers and buyers ask every afternoon: the straddle is down; was that time, or did IV come off? A premium chart alone cannot say. The card, titled What moved the 24550 straddle, starts from the at-the-money straddle at the strike nearest the forward, 24550, and compares its price at the day’s first reading and now: Call + Put ₹333.00 → ₹301.25, a change of −₹31.75.
| Row | What it measures | On the picture |
|---|---|---|
| Spot move | What the straddle changed because the underlying moved | −₹8.62, spot +63 pts |
| IV change | What it changed because IV changed | −₹24.33, IV −0.97 pts |
| Time decay | What it changed because time passed | −₹2.41, 2h 15m of decay |
| Other (a large move, or a stale price) | Whatever the first three do not explain | +₹3.61 |
The four parts add up to the change exactly (−8.62 − 24.33 − 2.41 + 3.61 = −31.75), because the last row is whatever is left. The Call and the Put at one strike are split separately and then added part by part. A straddle barely cares which way the price went, since its Delta is near zero, so what remains is mostly IV and time: the two things this page is about. When the unexplained part is more than a third of the total movement, the card adds a note that says the split is rough: the price moved far enough to change the straddle’s sensitivity, or one side’s price is stale. The split is first-order, worked from the model’s sensitivities at the start of the day, not an exact accounting.
Strikes: IV at Each Strike
Which strikes cost more in IV, and how has the curve moved since the open?
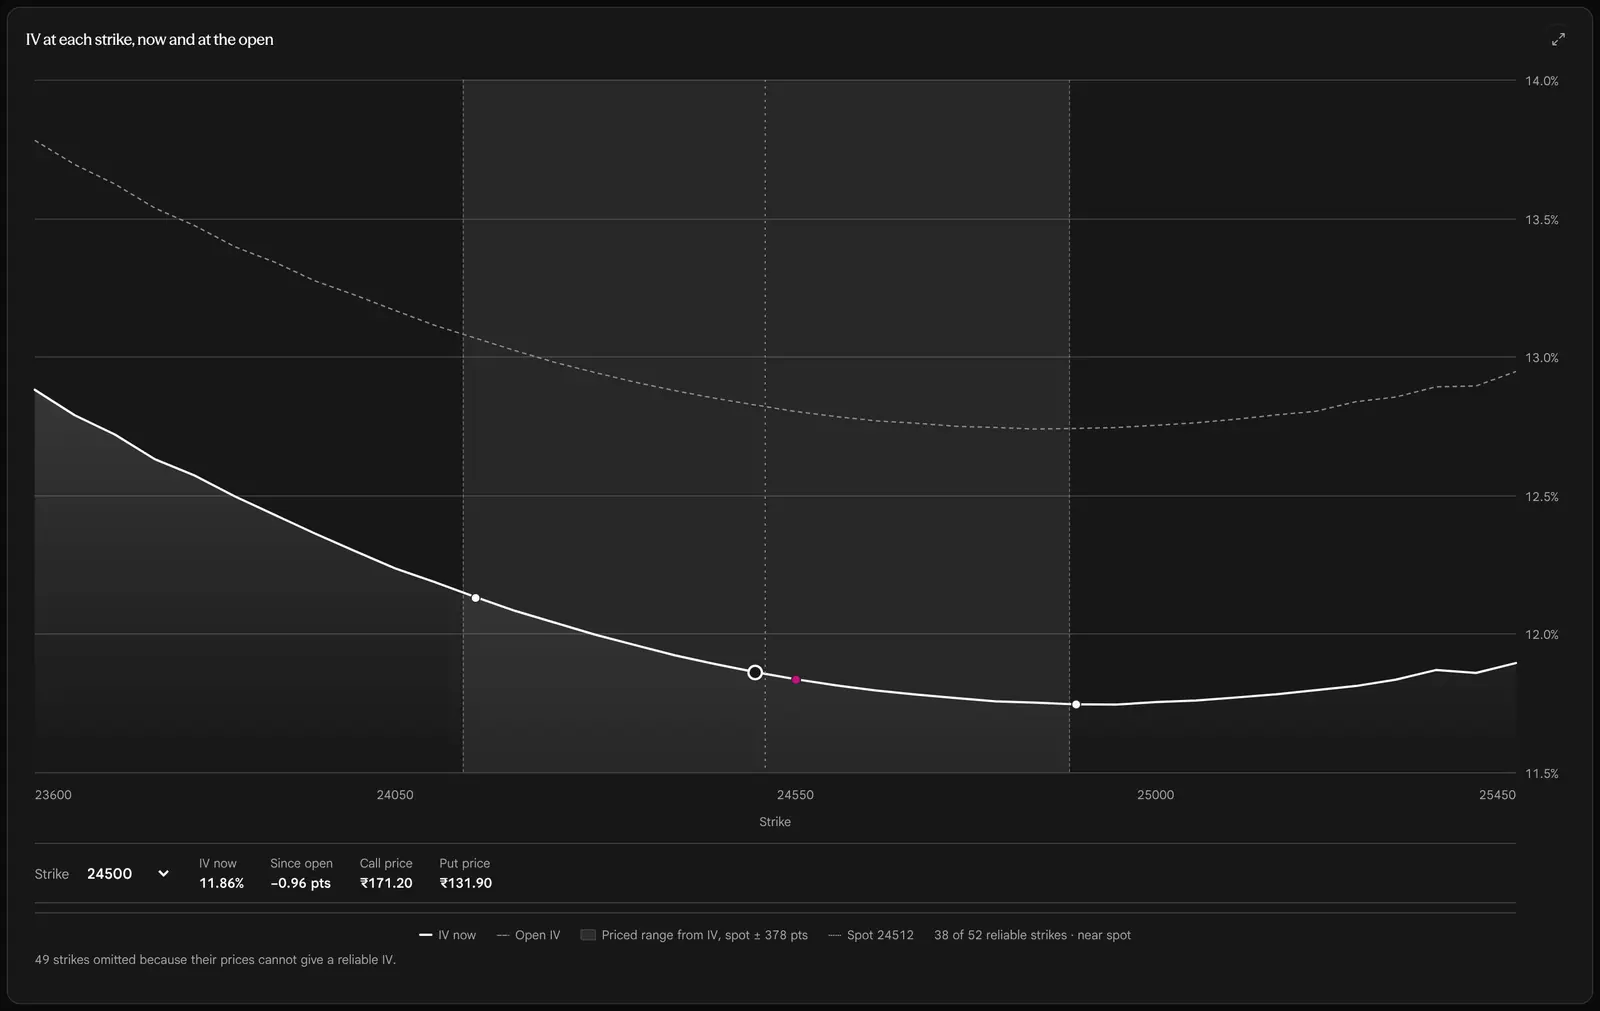
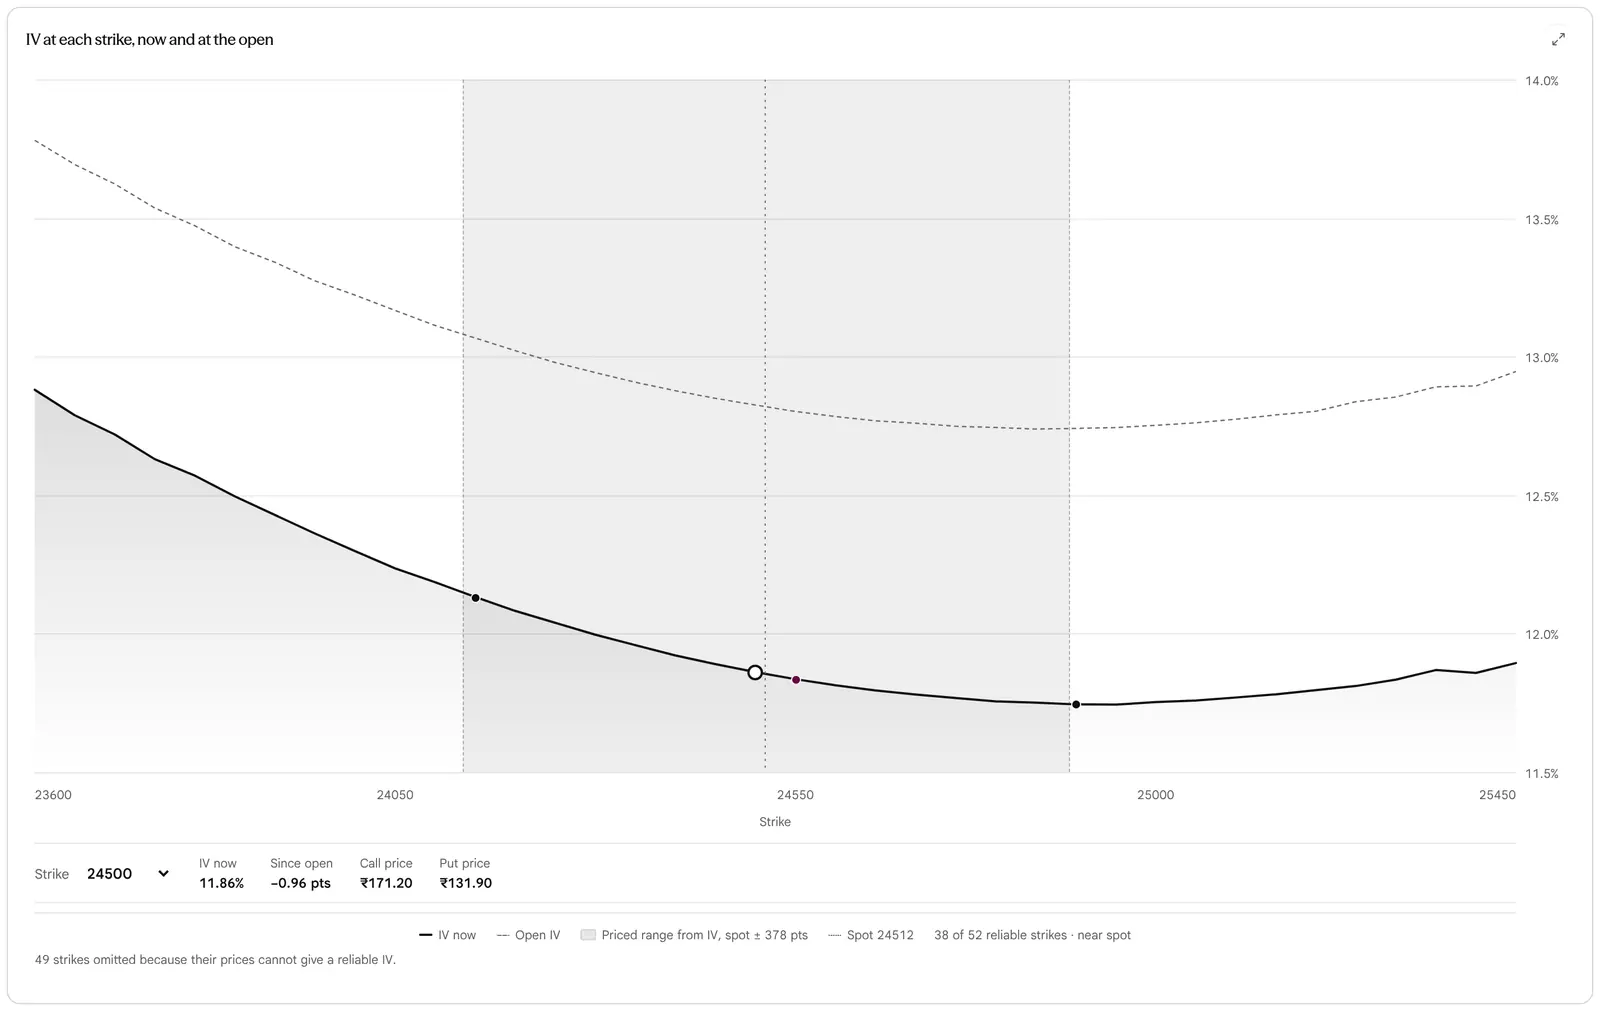
The card is titled IV by strike. Each strike has its own IV, and they are not equal. Plotted against the strike they form a curve, called the smile or the skew; the at-the-money figure is only one point on it. The page solves one IV per strike, from that strike’s own Call and Put, and a strike whose price does not identify an IV is a gap in the curve, not a zero. Three choices keep the curve readable:
- It opens zoomed. It draws 2.5 priced moves either side of spot, never fewer than 7 strikes. A day before a weekly expiry the far wings solve to very high figures on premiums of a few paise, and drawn whole they flatten the part anyone trades into a line along the floor. All strikes in Customise draws the whole solved ladder.
- The priced range is shaded. It is spot plus and minus one priced move (the second answer), so the curve reads against the move the market is paying for. The key under the curve says Expected range ±378 pts, and beside it a count such as 38 of 52 strikes shown. (The pictures show the earlier words, Priced range from IV, spot ± 378 pts.) A line under the key says how many strikes were left out: no reliable IV.
- The open curve is dashed beside today’s. Both are scaled together on round ticks.
The Pick-a-strike Readout and the Four Figures
Under the curve a readout follows the strike you pick (or the one nearest spot): IV now, Since open, Call price and Put price. Below the card, four figures sum the curve up.


- ATM IV is the same figure as the first answer, with the open beside it.
- Range low and range high (each with its strike, for example 24150 · range low) are the listed strikes nearest the forward minus and plus one priced move (24150 and 24900 on the picture), each with its own solved IV, its IV at the open and the change. They are measured at a distance in priced moves, not a fixed per cent, because 5 per cent is deep in the wings a day before a weekly expiry and barely off the money a month out. One priced move away is the same place on every expiry.
- Dearer side is the lower strike’s IV minus the higher strike’s (Low minus high strike): 12.13% less 11.75% is +0.39 pts. Under 0.3 of a point the page says Both sides priced about the same. At 0.3 or more it says Strikes below spot cost more or Strikes above spot cost more. On an index the lower side usually costs more, because protection is bought and upside is sold. That is a statement about prices, not a forecast of a fall.
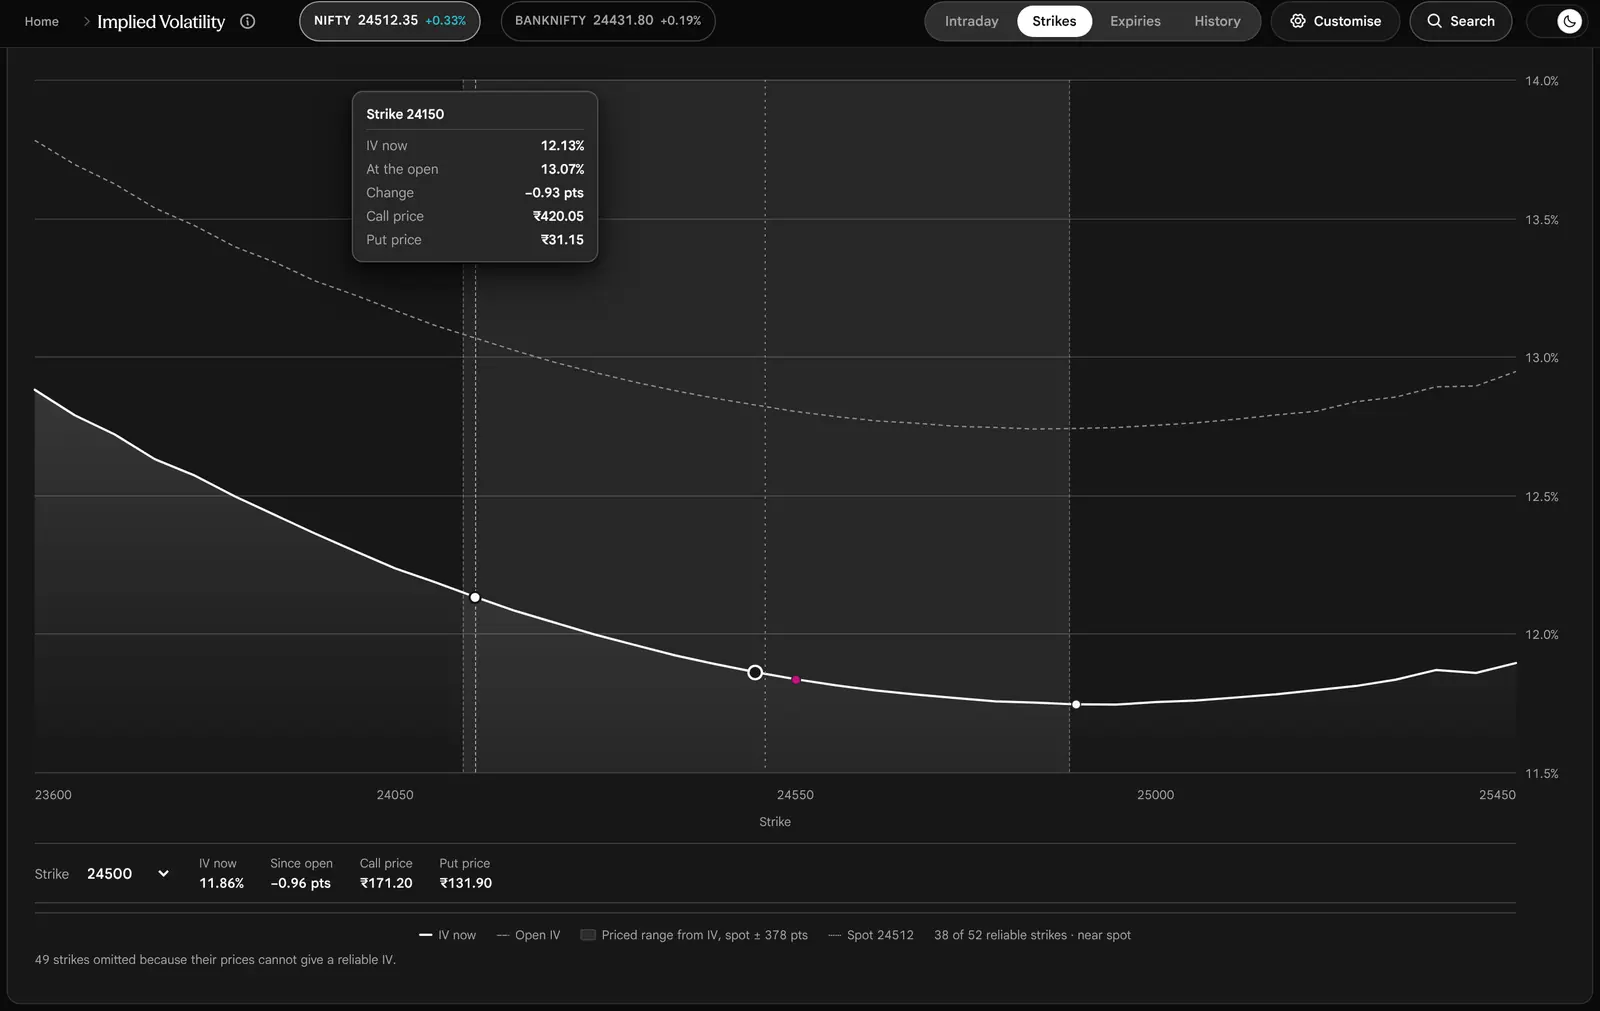
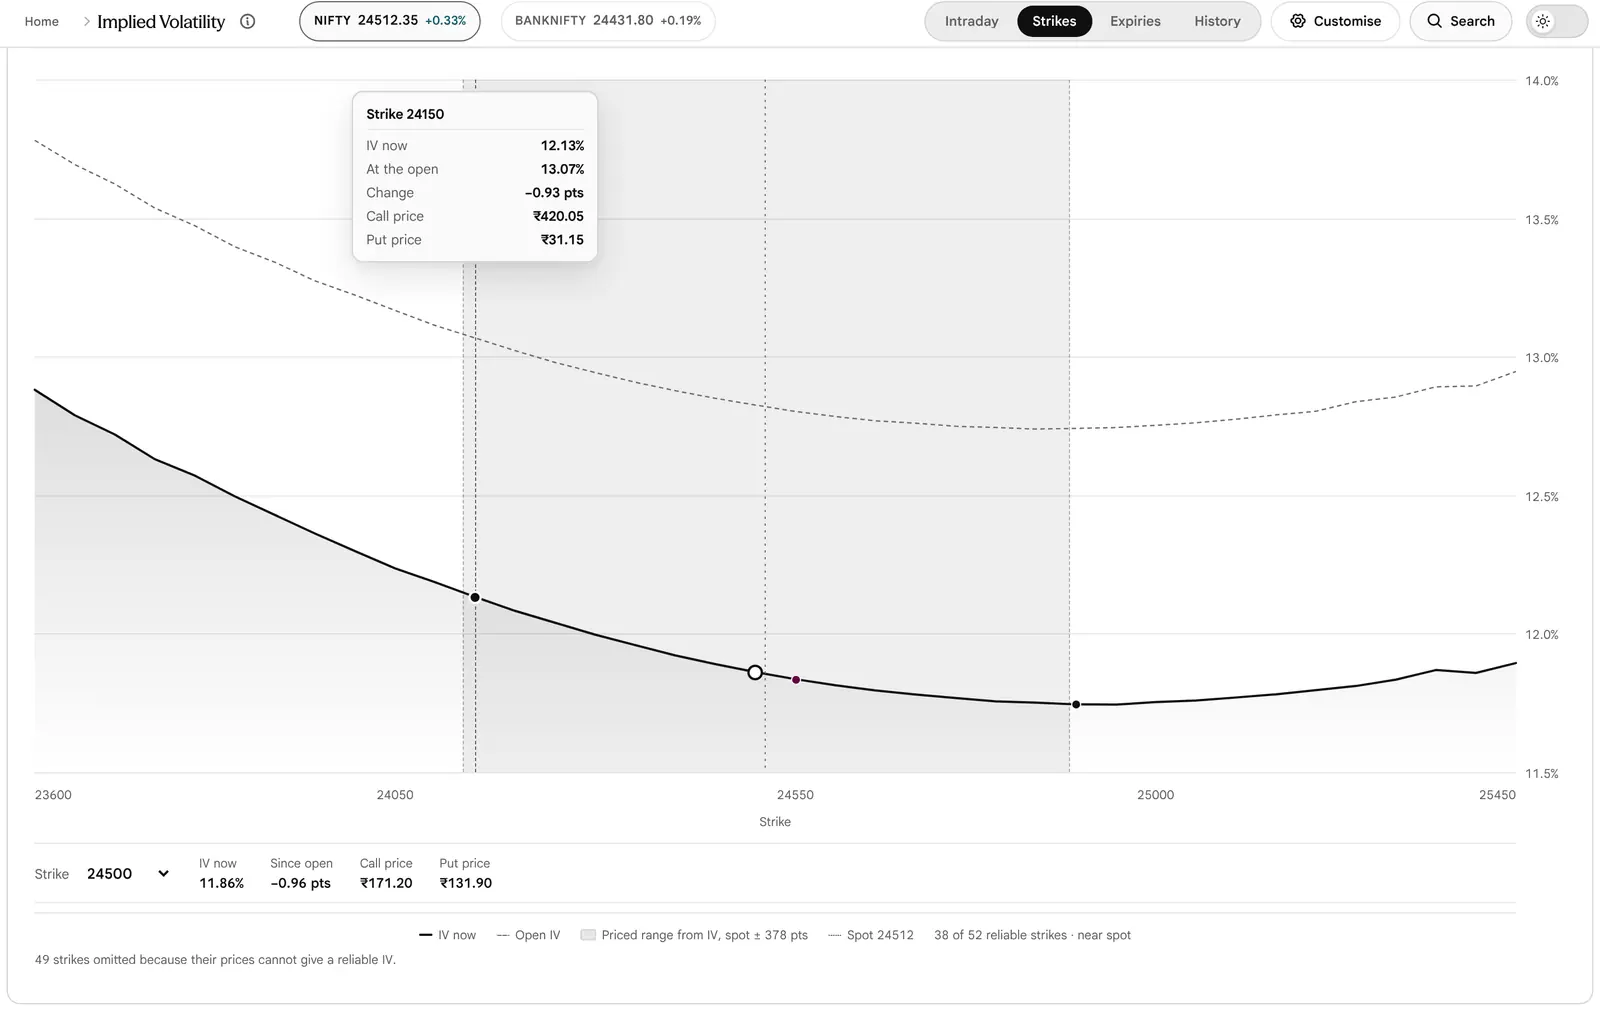
The same readout works on a touch screen and with a keyboard. The curve is one control (a slider with the label Explore implied volatility by strike): focus it with Tab, move with the Left, Right, Up and Down arrows, jump with Home and End, and press Escape to close the tooltip. The keyboard behaviour was read from the code and not run on every device (not tested).


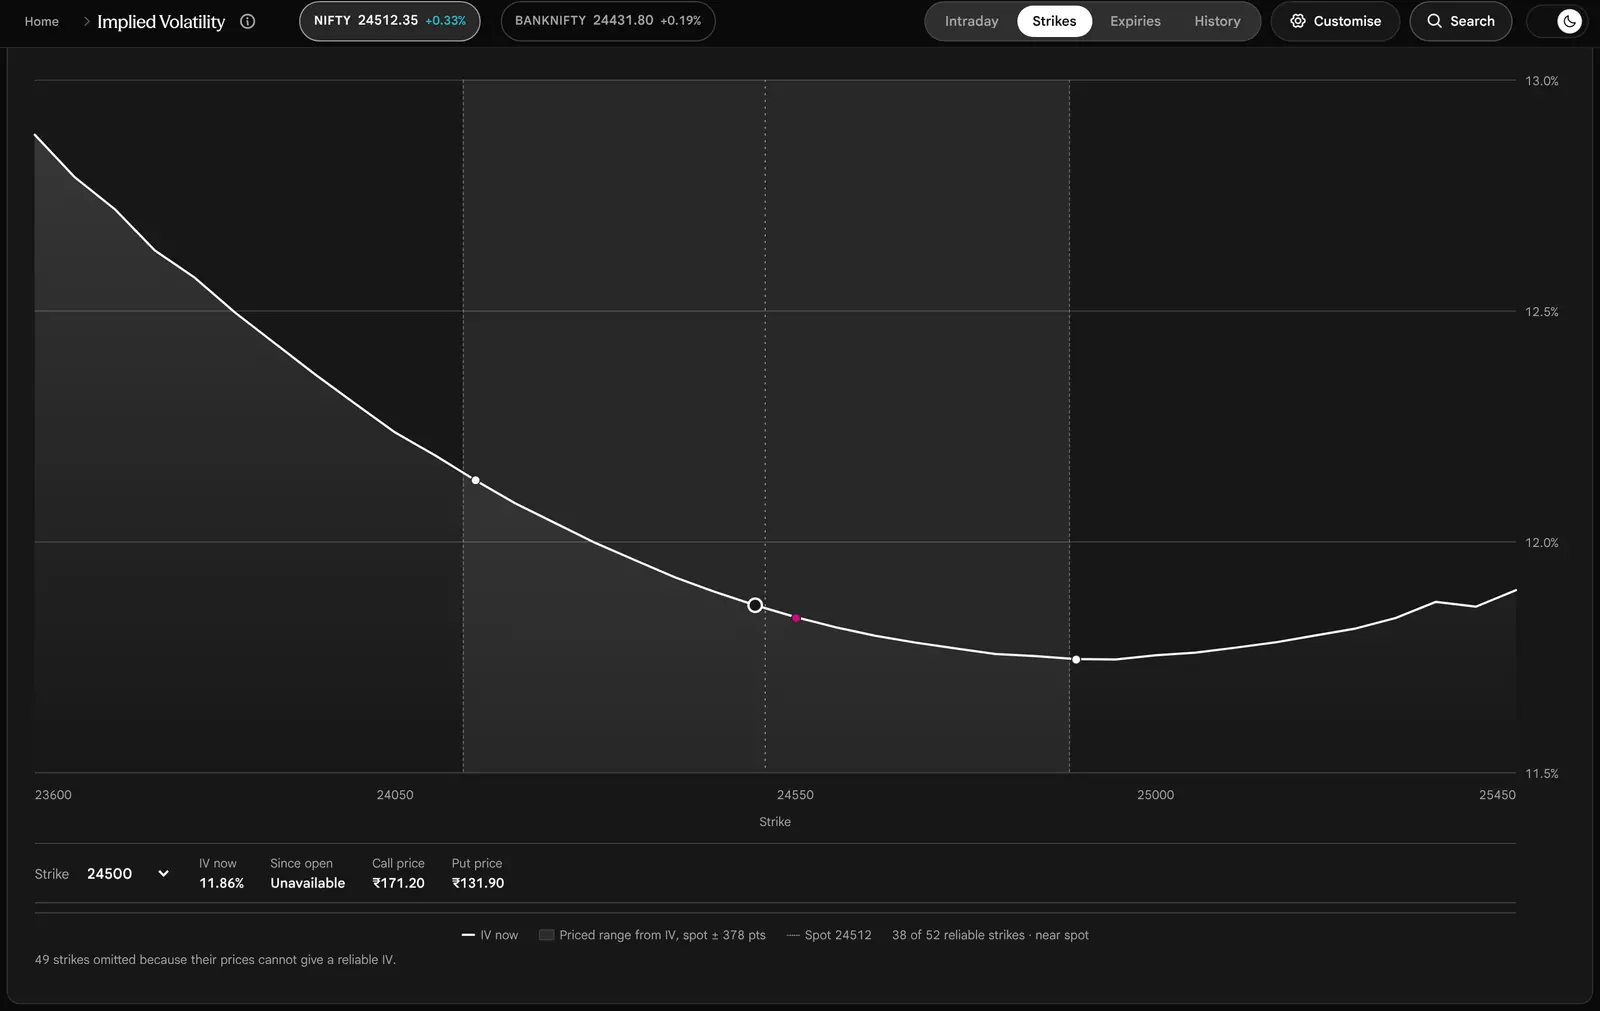
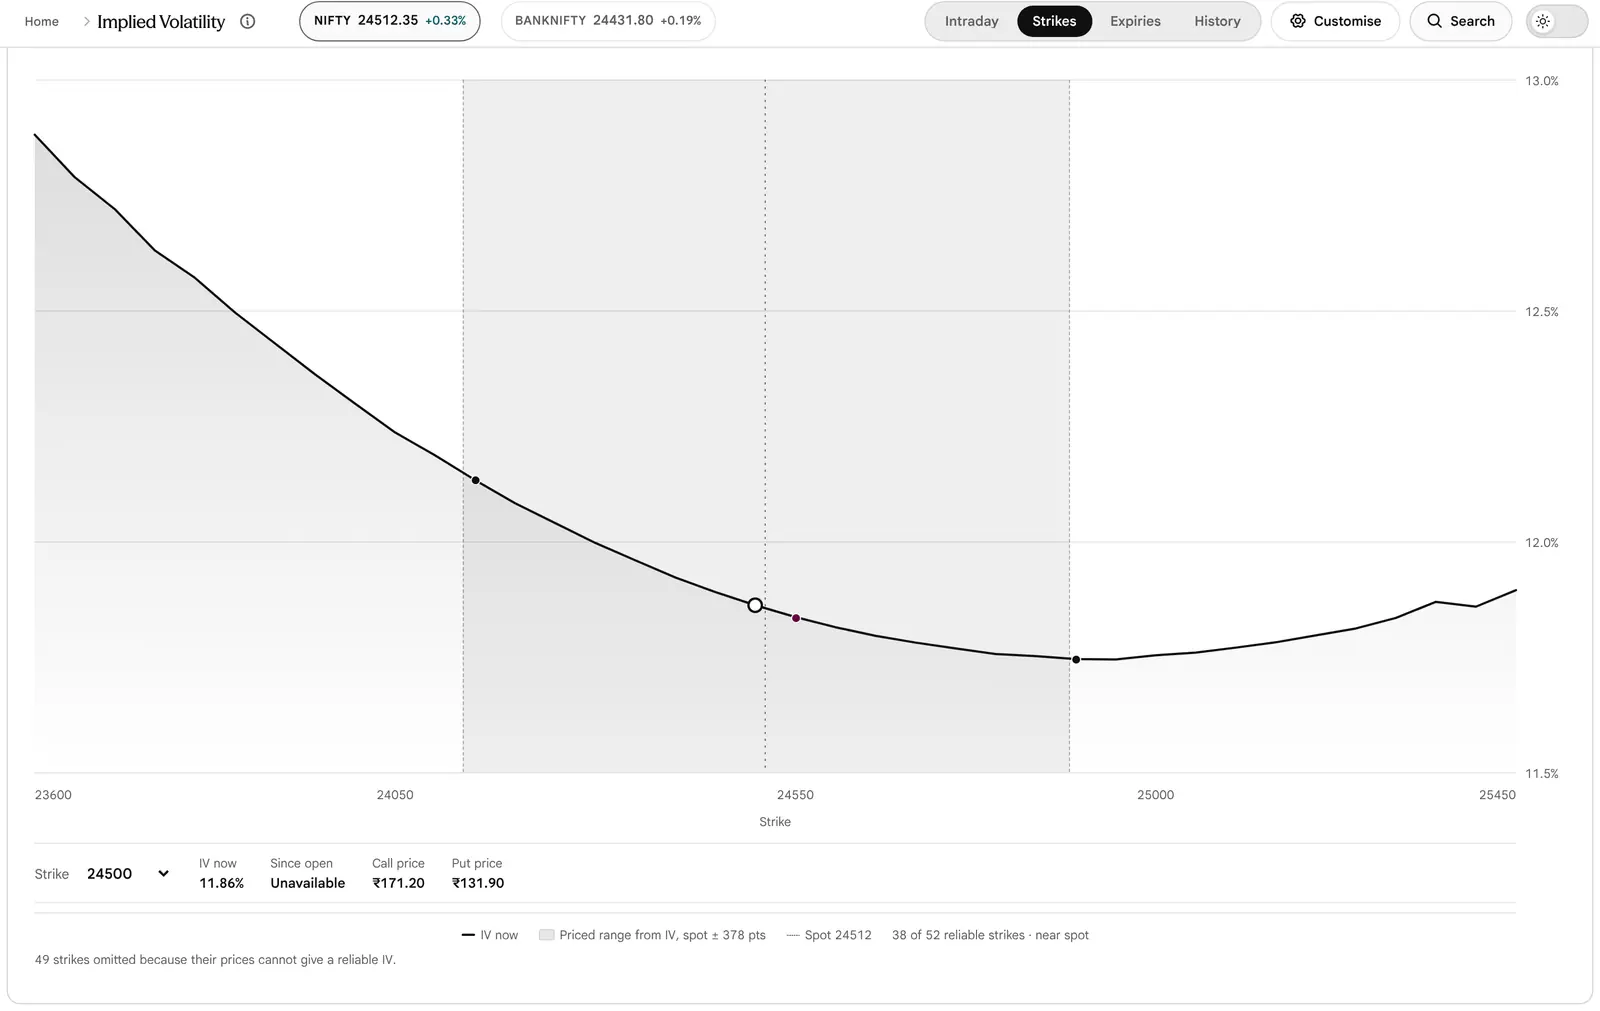
With the open curve switched off the view draws today’s curve alone (see Customise). If the latest snapshot carries no per-strike prices the card says No strike prices at this reading; if too few strikes show an IV it says Too few strikes carried a price that shows an IV to draw a curve.
Expiries: Every Live Expiry Side by Side
Which expiry is paying for the most movement each day, and what is the 30-day IV?

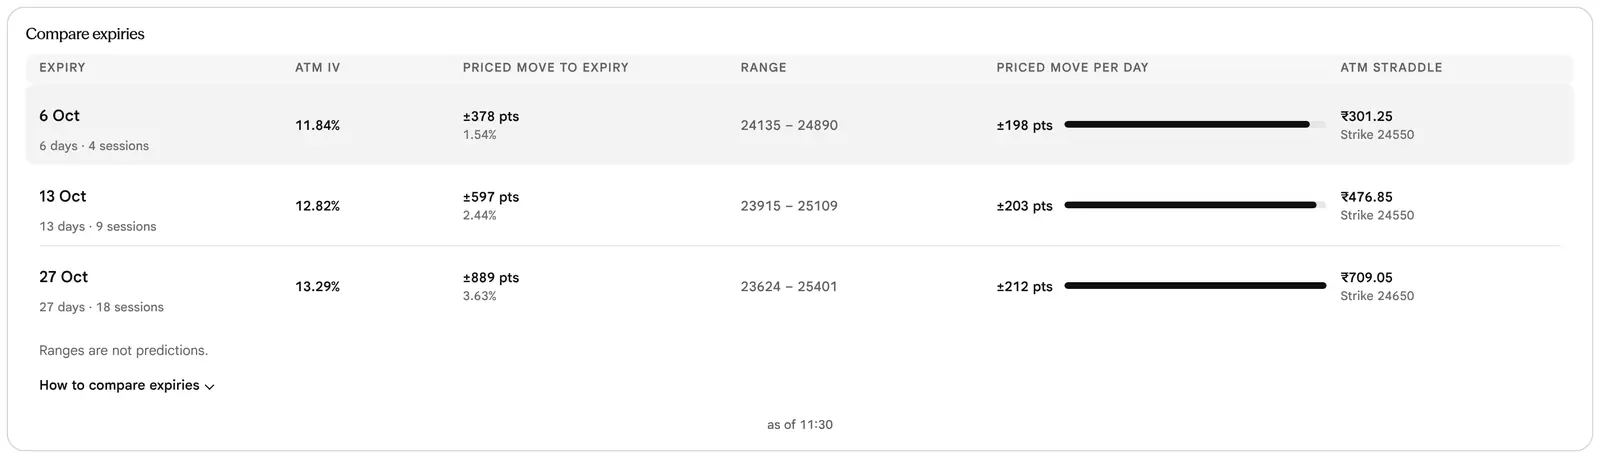
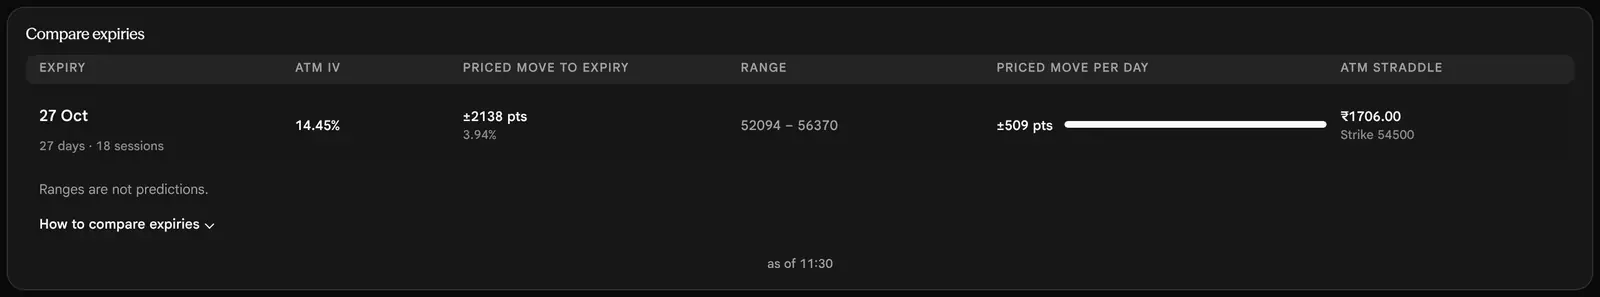
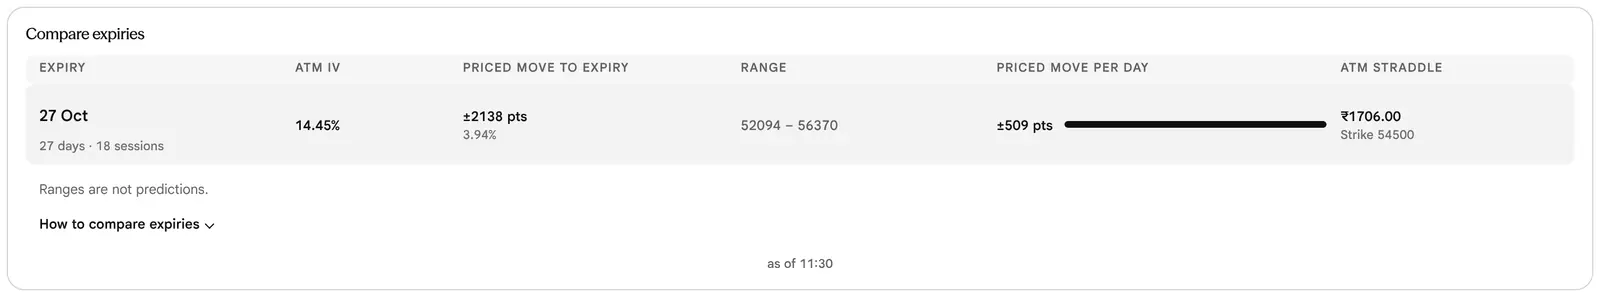
The card is titled Compare expiries. The view is a table, not a curve. The page reads at most 3 live expiries, and a few points drawn as a line would invite you to read a shape into them. Across, the rows answer the questions traders bring here:
| Column | What it says | 6 Oct row |
|---|---|---|
| Expiry | The date, the calendar days left (or Expires today) and the sessions left | 6 days · 4 sessions |
| ATM IV | The at-the-money IV of that expiry, solved the same way as the first answer | 11.84% |
| Move to expiry | One standard deviation, in points and per cent | ±378 pts 1.54% |
| Range | Spot less and plus that move | 24135 – 24890 |
| Move per day | The move divided by the square root of the sessions, with a bar scaled to the largest row (a length, so it takes no colour) | ±198 pts |
| ATM straddle | The Call plus Put price at the strike nearest the forward, and that strike | ₹301.25 24550 |
The row of the expiry you are reading is marked. It is solved from the same archived reading as the insight above it, not from a separate chain fetch a minute apart, so the two never disagree. The other rows are read when the page opens and then at most once a minute (60 seconds), and only when a new reading has arrived. The line under the table says when: As of 11:30. If the other expiries cannot be read, the card says The expiries could not be read just now. with a Try again button.
Compare the Move per Day Down the Rows
The IV column is not comparable row to row. It counts calendar days, and a nearest expiry with one or two days left is a small number to spread a move over, so its IV reads high for that reason alone. The per-day move has no such clock in it. On the picture the three IVs are 11.84%, 12.82% and 13.29%, yet the three days are priced at ±198, ±203 and ±212 points: the farther expiries pay for a little more movement a day, and the move to expiry grows with the square root of time (378, 597, 889).

The Foot: a Blend Only When One Exists
The foot says Ranges are not predictions. Under it, How to compare expiries opens a short note: why a near expiry reads high in IV, why the move per day is the fair comparison, and the 30-day IV: “The blend gives a 30-day IV of 13.29%, used for IV Rank and IV Percentile”. Where the expiries do not reach far enough, it says These expiries do not reach far enough to blend a 30-day IV. Note that the sentence says “blend” also when none of the rows reaches 30 days and the furthest row simply stands in, as it does here (13.29% is the 27 Oct row’s own IV). An expiry that gave no reading is named in a line such as No reading for 13 Oct: option prices did not provide a usable IV.
History: the Past Year of 30-day IV
Is today’s IV high or low for the past year, and has it run above or below the moves the market actually made?

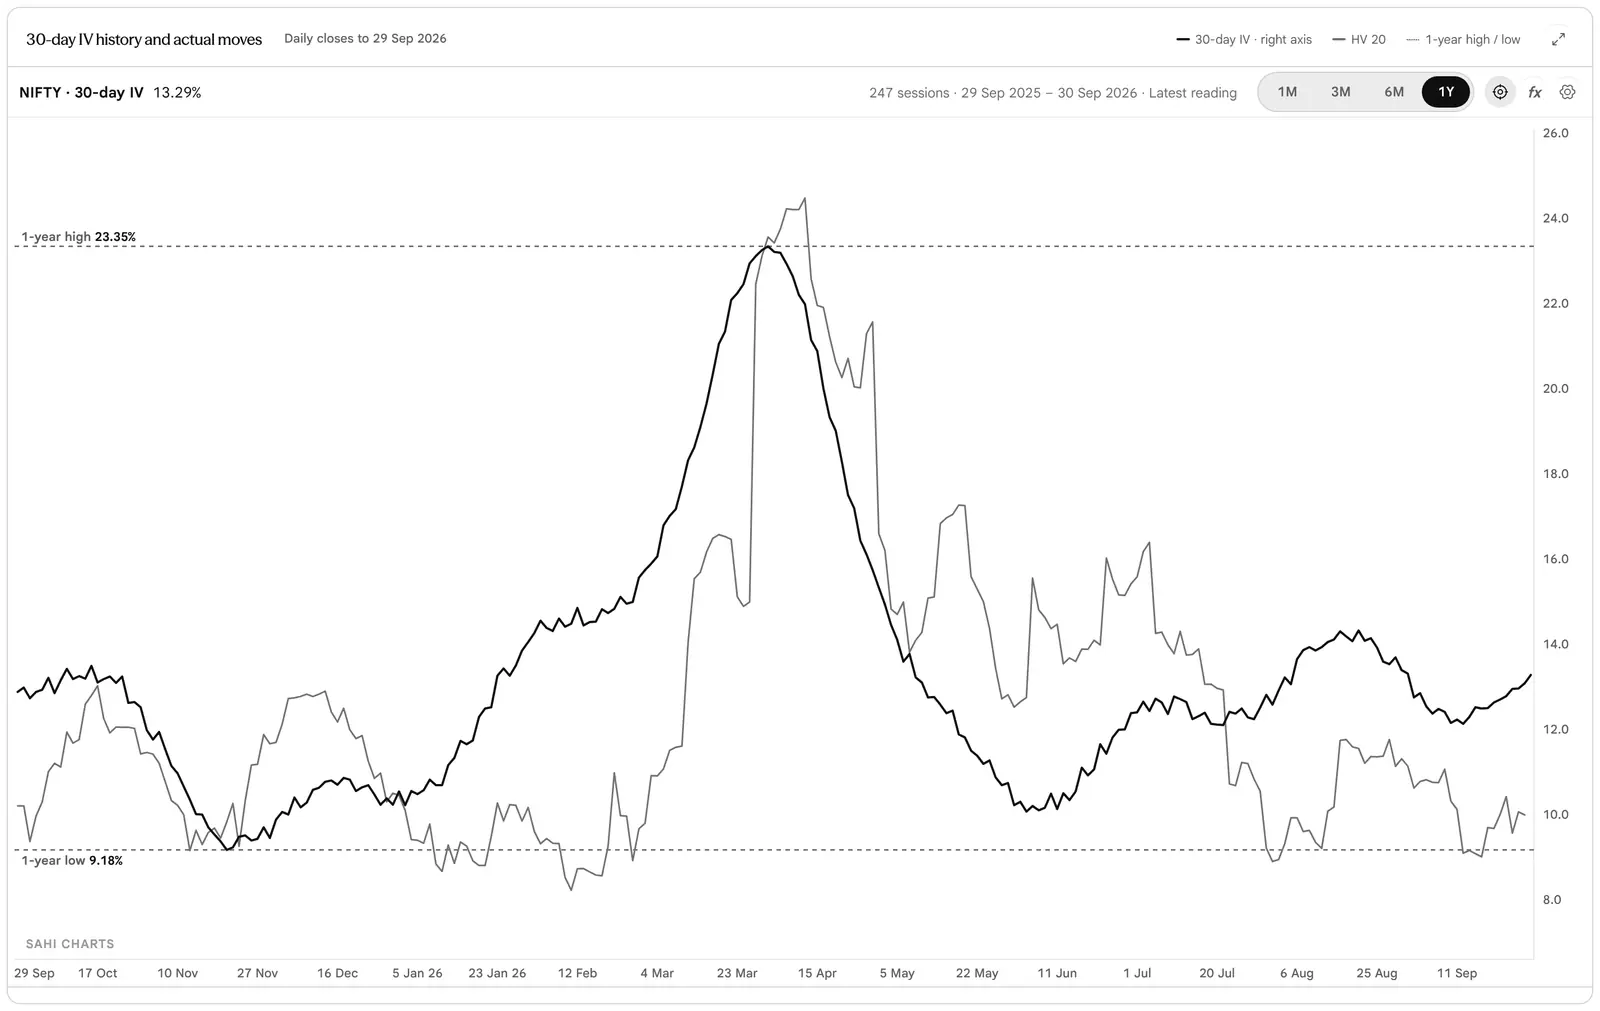
This is the year-long view of IV: is today’s IV high or low for this underlying, and has it been running above or below what the market actually did? The card is titled 30-day IV history, or 30-day IV and HV when the HV line is on. It draws, on one right-hand axis, the 30-day IV close of each session (white, with its latest value tagged on the axis), and HV 20, the underlying’s historical volatility over the last 20 sessions (grey): the moves the market actually made. The year’s highest and lowest closes are ruled across as dashed lines, tagged 1-year high and 1-year low: they are exactly the two ends IV Rank divides by, so the rank in the opened insight can be read off the chart. The last point is today’s live 30-day IV, when it can be worked out and is later than the file’s last close. The card head says how far the closes run: Closes to the file’s last date (the picture shows the earlier words, Daily closes to 29 Sep 2026). On the live page the closes now run to 16 October 2026. The chart head counts the sessions drawn. The key reads 30-day IV, HV 20 and 1-year high / low, with India VIX and the close when they are on.
The row above the chart is as simple as on Intraday: plain text tabs for the window (1M, 3M, 6M, 1Y, with 1Y at first), a crosshair switch and full screen. There are no indicators, chart types, chart settings or drawing tools.
The Four Figures
The four figures are named in sentence case on the page: IV percentile (65, Above 65% of the last 252 closes), IV rank (29, Where today sits in the year’s range), the 1-year high (23.35%, On 1 Apr) and the 1-year low (9.18%, On 20 Nov). They are the figures of the fourth answer, with the dates of the two extremes. (With a history shorter than a year the two extreme cells still carry the labels 1-year high and 1-year low; read the sessions count in the chart head.)


Reading Two Lines Together
Hover the chart to read a day: the tooltip gives the date (with · live on the last point), the 30-day IV, HV 20, IV minus HV and any other line that is on.
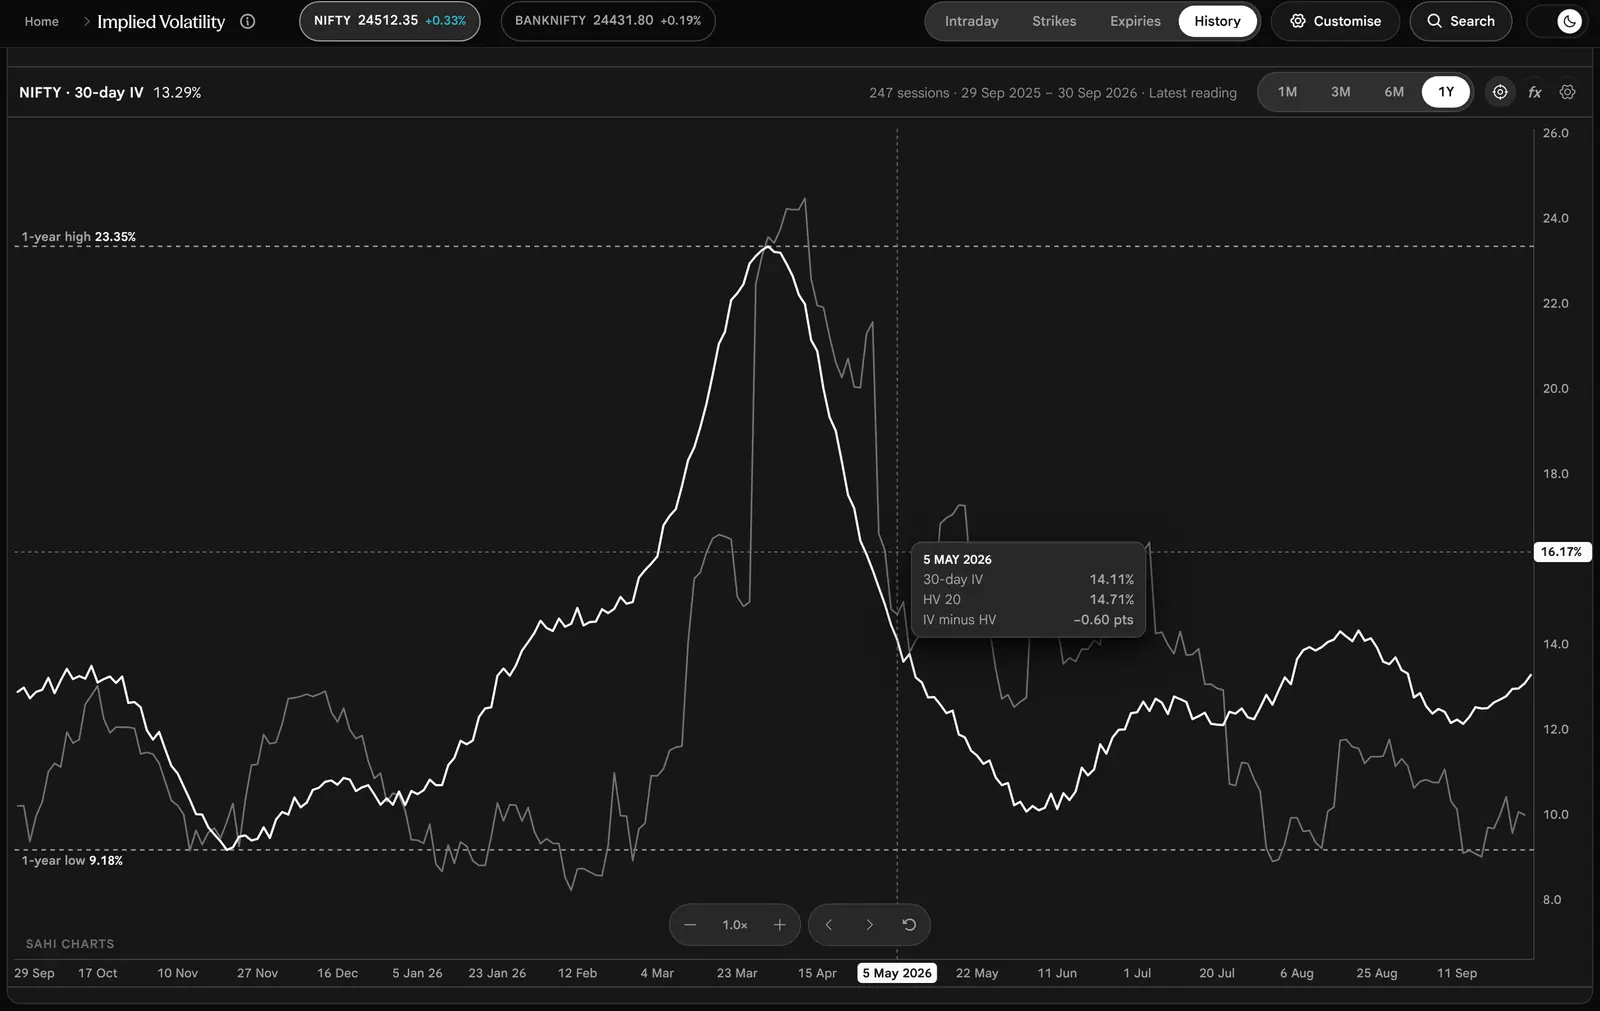

- IV above HV means the 30-day option prices ask for more movement than the last 20 sessions delivered. Option prices often carry a premium over the volatility that followed, so this is common; the picture shows the two lines crossing in both directions.
- IV below HV means the market has been moving more than option prices expected. It is worth noticing, not a signal.
- One window is not a verdict. HV 20 describes the past month; the 30-day IV describes the next. Neither says which way price goes.
India VIX and the Close

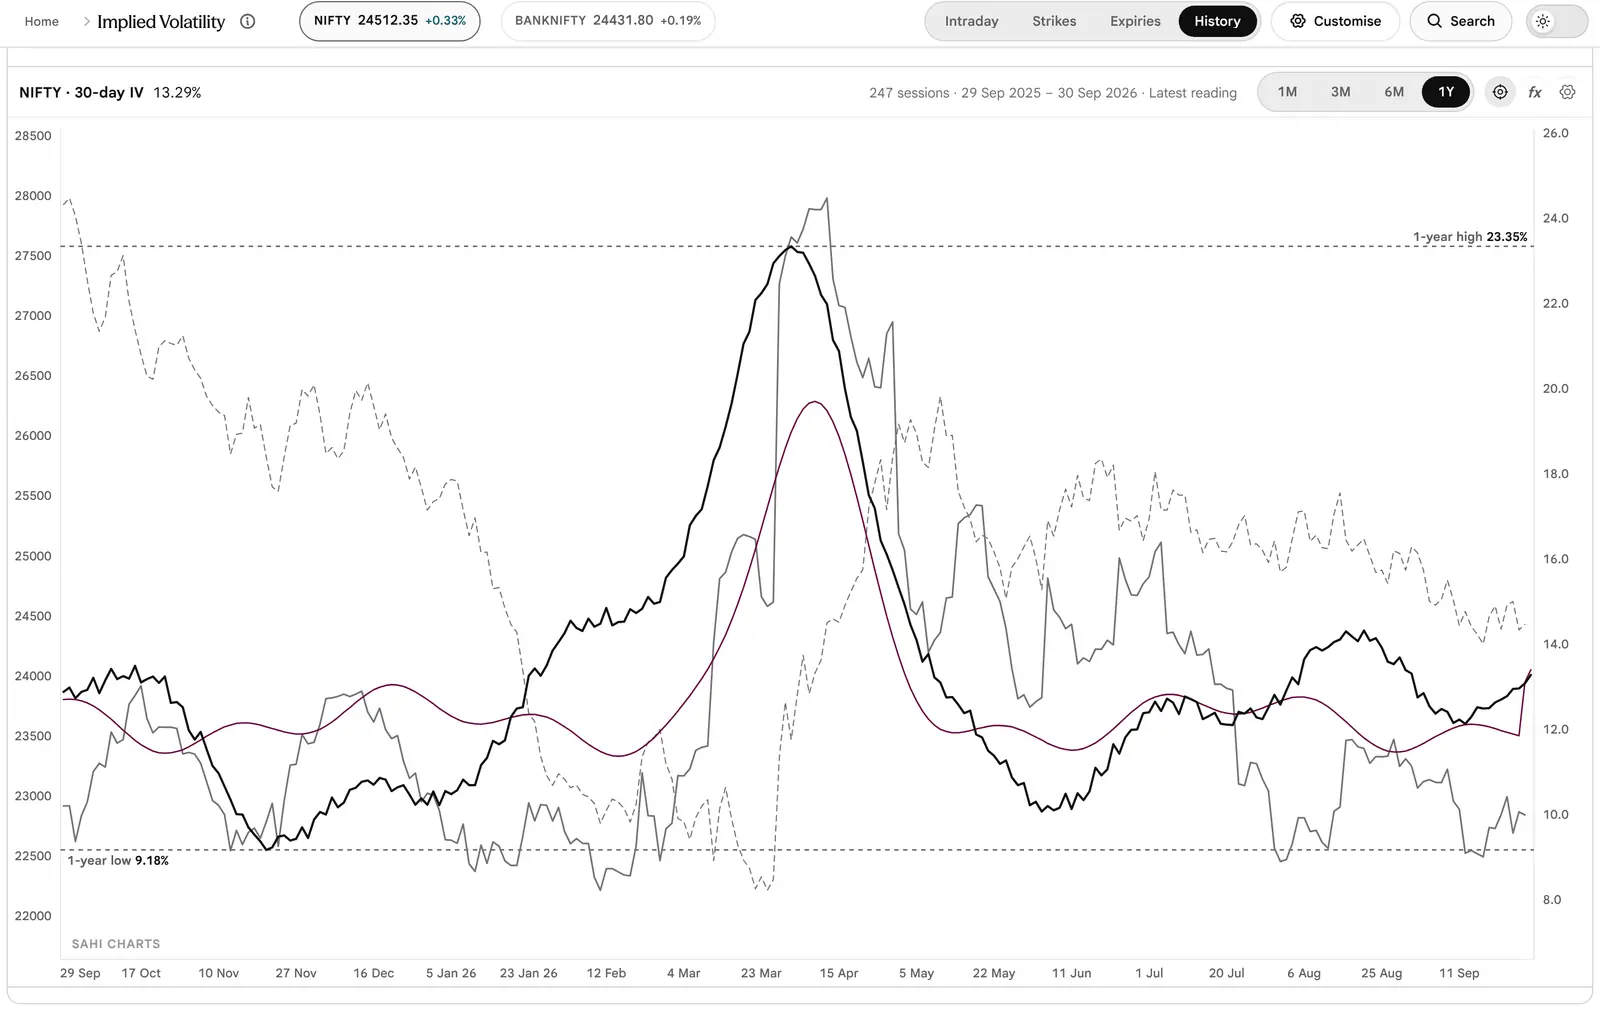
India VIX is offered for NIFTY only, since it is NIFTY’s index; the switch does not appear for any other underlying (Customise). The close, on its own left axis, lets you see how the volatility moved against the price over the year.
When There Is No Year
The year of closes comes from one file. For an underlying that is not in it (a new listing, or a BSE index such as SENSEX or BANKEX, whose history is not collected yet) the card says so in a plain sentence in place of the chart, and the fourth answer says No year of IV closes for the symbol. A failed read says The year of IV closes could not be read just now (states).
Customise: Every Switch and Its Default
What can I change in how the page reads, what are the defaults, and what is remembered?
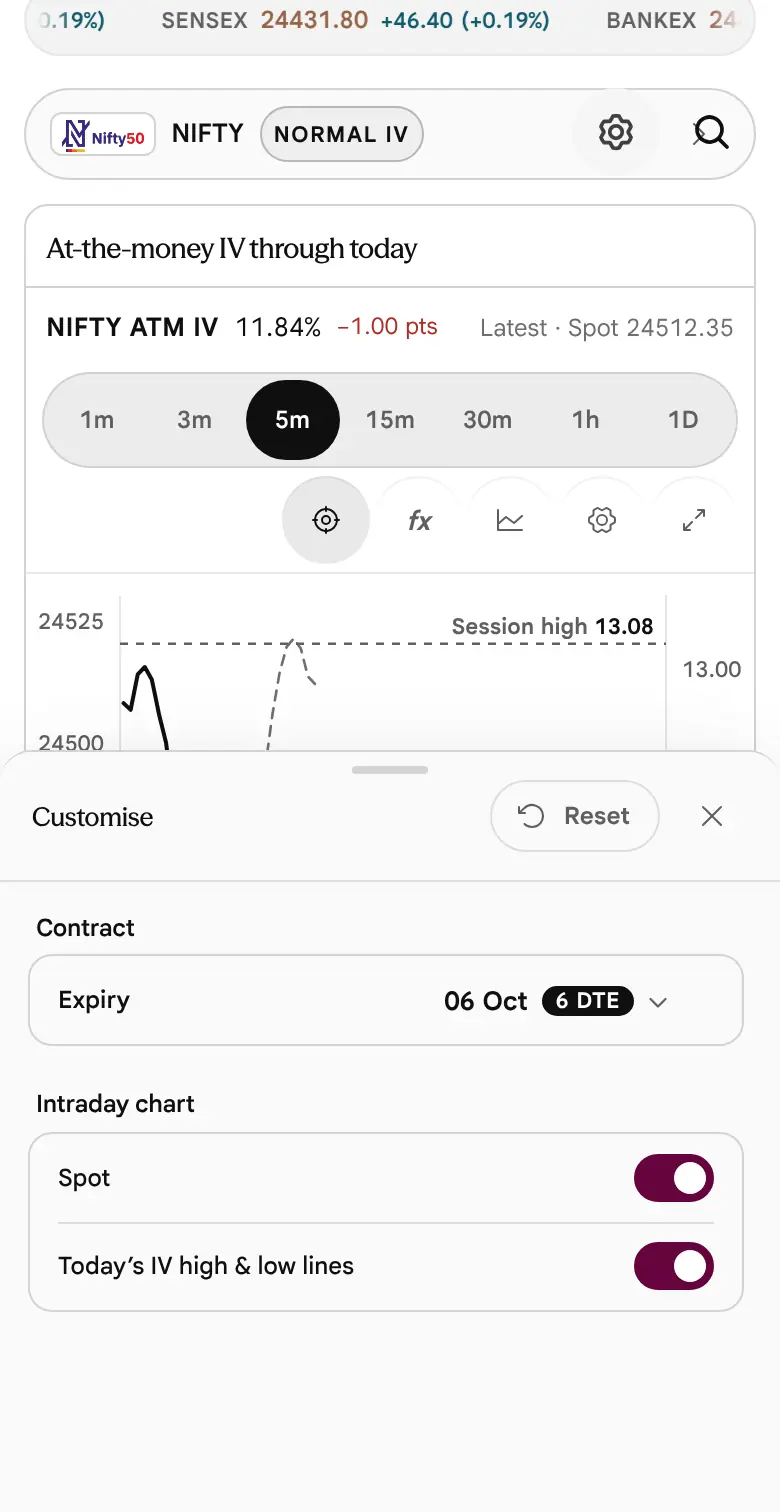
The Customise button in the page bar (a gear and the word) opens a panel under it. It is the same panel shell as the Option Chain’s. Every change applies at once, so the only buttons are Reset and a close button. Escape closes it and returns focus to the button. The panel holds one Contract section and one section for the view you are on: a view shows only the switches that change what it draws.
The Contract Row
The Expiry selector is the site’s one expiry control. It sets the expiry the insight, the Intraday view and the Strikes view read. On the History view the chart reads a 30-day blend of every expiry, so the expiry does not change it. On the Expiries view the page has nothing else to set, so the expiry selector stands in the page bar where Customise was.


The Switches
| View | Switch (exact words) | Default | What it does |
|---|---|---|---|
| Intraday | Spot | On | Draws the underlying’s spot, dashed, on its own left axis |
| Day high & low | On | Rules the day’s highest and lowest IV across the plot | |
| Strikes | Open IV | On | Draws the curve as it stood at the first reading, dashed |
| All strikes | Off | Draws every solved strike instead of 2.5 priced moves either side of spot | |
| History | HV 20 | On | The grey line of actual moves beside the 30-day IV |
| India VIX | Off | NSE’s index as a second line; offered for NIFTY only | |
| Close | Off | The underlying’s daily close, dashed, on a left axis |
The IV line itself is always drawn. Every other line is a switch, with the default shown in the table. Customise holds no chart settings, indicators or chart types: the charts have none. The symbol in the labels follows the underlying you are reading (for BANKNIFTY the labels say BANKNIFTY).


What Is Remembered
- The switches are kept in this browser, field by field (key
ivCustomise:v1), so a stale or hand-edited entry cannot break the page. Reset returns them to the defaults above. - The view you left is remembered the same way (
ivView:v1), so the page reopens on it. - The expiry is not a preference. It is the contract being read, so Reset leaves it alone and the page does not store it.
- No chart window or rewind is ever stored. Reopening tomorrow on yesterday’s instant would chart a stale moment with nothing to say it was not current.
Nothing is sent to a server. In a private window or with site data blocked, a change lasts for the visit only.
Every State the Page Can Be In
What does the page say when it has no number, and what does each state mean?
The page keeps four things apart that are easy to confuse: still reading, nothing to show, could not read and the first reading of a new session. While data is still being read the page says so, and a figure that could not be measured is named, never drawn as zero.


This is what the page shows when the day’s minute archive is empty: the app seeds one reading from the current chain. (While the archive is still being read, the page shows Reading today’s option prices instead.) The verdict pill reads First reading, and each change says why it is empty, for example “This is the session's first reading, so the 5-minute window has no baseline yet.” The answers still work, because they need the chain, the daily closes and the year, and not the archive. The chart needs two readings to draw a line.
| State | The words on the page | What it means |
|---|---|---|
| Error | Implied Volatility is unavailable, then the message the app passes on | The page could not get what it needs. Reload; if the message persists, the data for this underlying is not there. |
| Loading | Reading today’s option prices, then Waiting for NIFTY readings on the 6 Oct expiry… | The day’s archive is still being read. Not captured in this guide (see What we have not verified). |
| Nothing yet | No readings yet, with the cause under it; or This expiry has settled | No snapshot exists for this symbol and expiry, or the expiry is over. |
| First reading | Verdict First reading; changes show a dash and the reason | Only one reading has been collected for the session. |
| A figure that cannot be placed | Not measurable at this reading; No strike that far from spot; No reading at the open | The cause is the stated one; the figure is left out, not zero. |
| Strikes: no prices | No strike prices at this reading; Too few strikes carried a price that shows an IV to draw a curve | The snapshot has no per-strike prices, or too few solve. |
| Expiries | Reading each expiry…; No live expiry to read; The expiries could not be read just now, with a Try again button | Still loading; none live; or a failed read. Press Try again, or wait for the next reading. |
| The year | Reading the past year…; The year of IV closes could not be read just now; There is no year of IV closes for X in NSE’s F&O file | Loading; the file failed; or the underlying is not in it. |
| No daily closes | No daily closes to compare with (Reading daily closes… while loading) | Fewer than 21 closes: the actual day cannot be measured. |
| Short history | Last N sessions stored, not a full year; IV Rank: Needs a full 252 sessions | Fewer than 252 sessions of closes. |



The fourth answer and the verdict also change when the year is missing: see the verdict words. And on a settled expiry no reading is possible at all: the page says This expiry has settled and quotes This series has settled, so its option prices no longer describe a live contract.
Calendar Days: Mondays, Holidays and Expiry Day
Why does IV jump on a Monday and race up on expiry day when nothing has happened?
A Taxi Fare Spread Over the Wrong Number of Days
Suppose a taxi charges for two working days but the contract is written over five calendar days, because a holiday and a weekend sit in the middle. Quoted per calendar day, the daily rate looks low. After the weekend, one working day over one calendar day, the same fare looks high. The taxi did not get dearer. The denominator changed.
Implied volatility has exactly this problem. It is a yearly figure counted in calendar days, which, as the page’s own note says, is how brokers and India VIX count them. The market, however, moves only on trading days.
The page’s IV is the volatility that, spread over the calendar days to expiry (to the 15:40 close), gives the option’s price. What the market really charges is a move over the sessions left. Put the two together and the same per-session price gives a different IV on different days:
Thursday 1 Oct, 15:40, to the 6 Oct expiry: 2 sessions over 5 days: √(0.00794 ÷ 0.01370) = 0.76
Monday 5 Oct, 14:20, to the 6 Oct expiry: 1.21 sessions over 1.06 days: √(0.00479 ÷ 0.00289) = 1.29
The factor multiplies the same session-clock volatility. 0.76 and 1.29 are worked by hand here from the dates of the pictures; the page does not print them.Monday After a Holiday Weekend
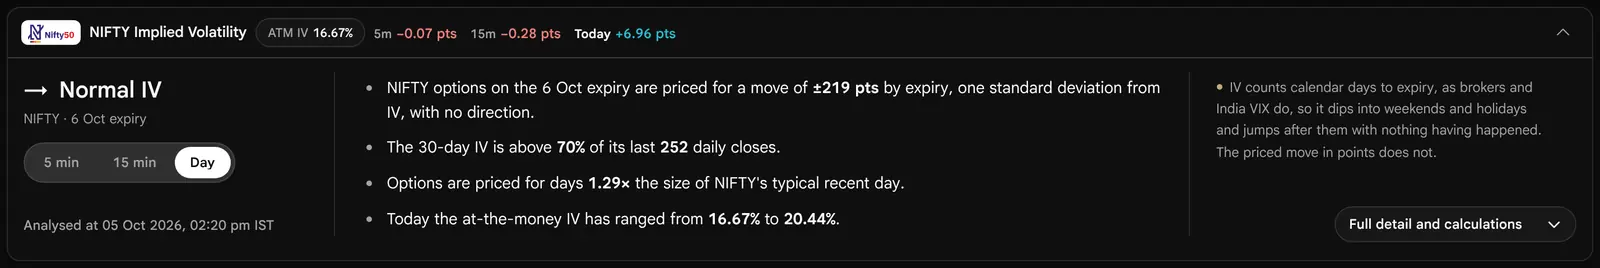
The next picture is the real page on an illustrative Monday, 5 October at 14:20. Friday 2 October (Mahatma Gandhi Jayanti) is a holiday in the app’s own calendar, so the previous session was Thursday 1 October and three days (Friday, Saturday, Sunday) were shut.
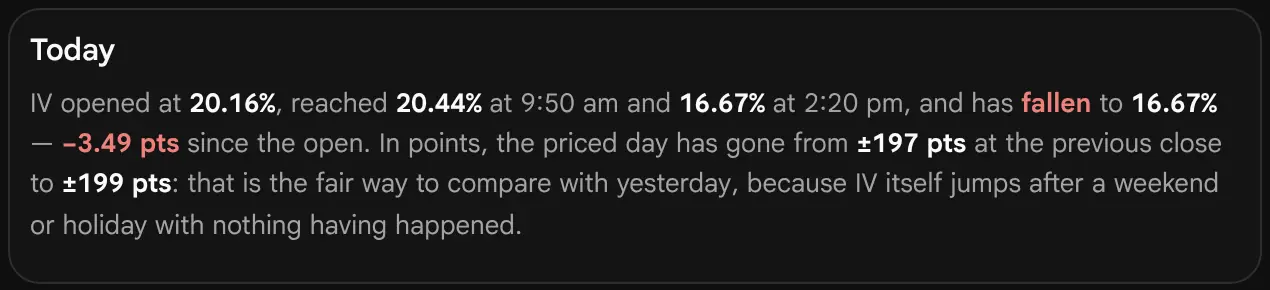

The insight row says ATM IV is up +6.96 pts against Thursday’s close, from 9.71% to 16.67%. The Today section says the day being priced is about the same: from ±197 pts at the previous close to ±199 pts. Nothing happened. The factor of 0.76 at Thursday’s close and 1.29 on Monday afternoon explains it: 9.71 ÷ 0.76 is about 12.76 and 16.67 ÷ 1.29 about 12.95 on a session clock, within 0.2 of a point of each other (worked from the unrounded factors). This is why the page leads with points per session, and why the opened insight always carries the note about calendar days.

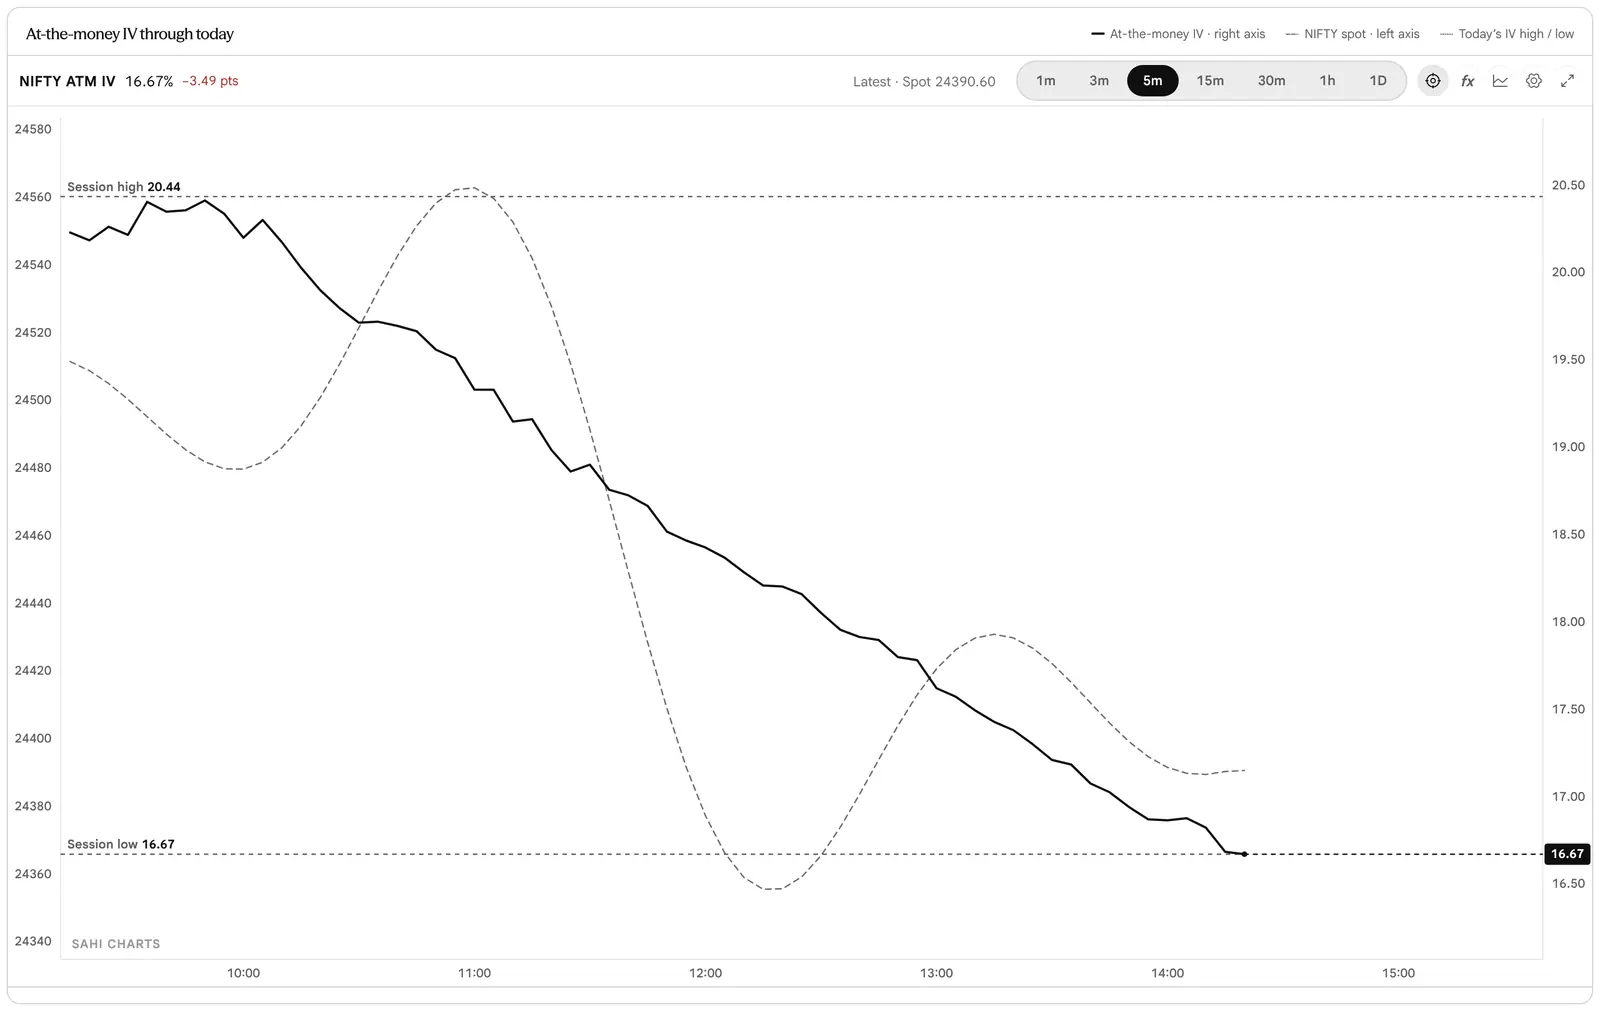
The same effect makes IV dip into every weekend and recover after it, which is why a long weekend shows a sag in the IV line. It is a convention of the calculation, not a change in the market.
Expiry Day
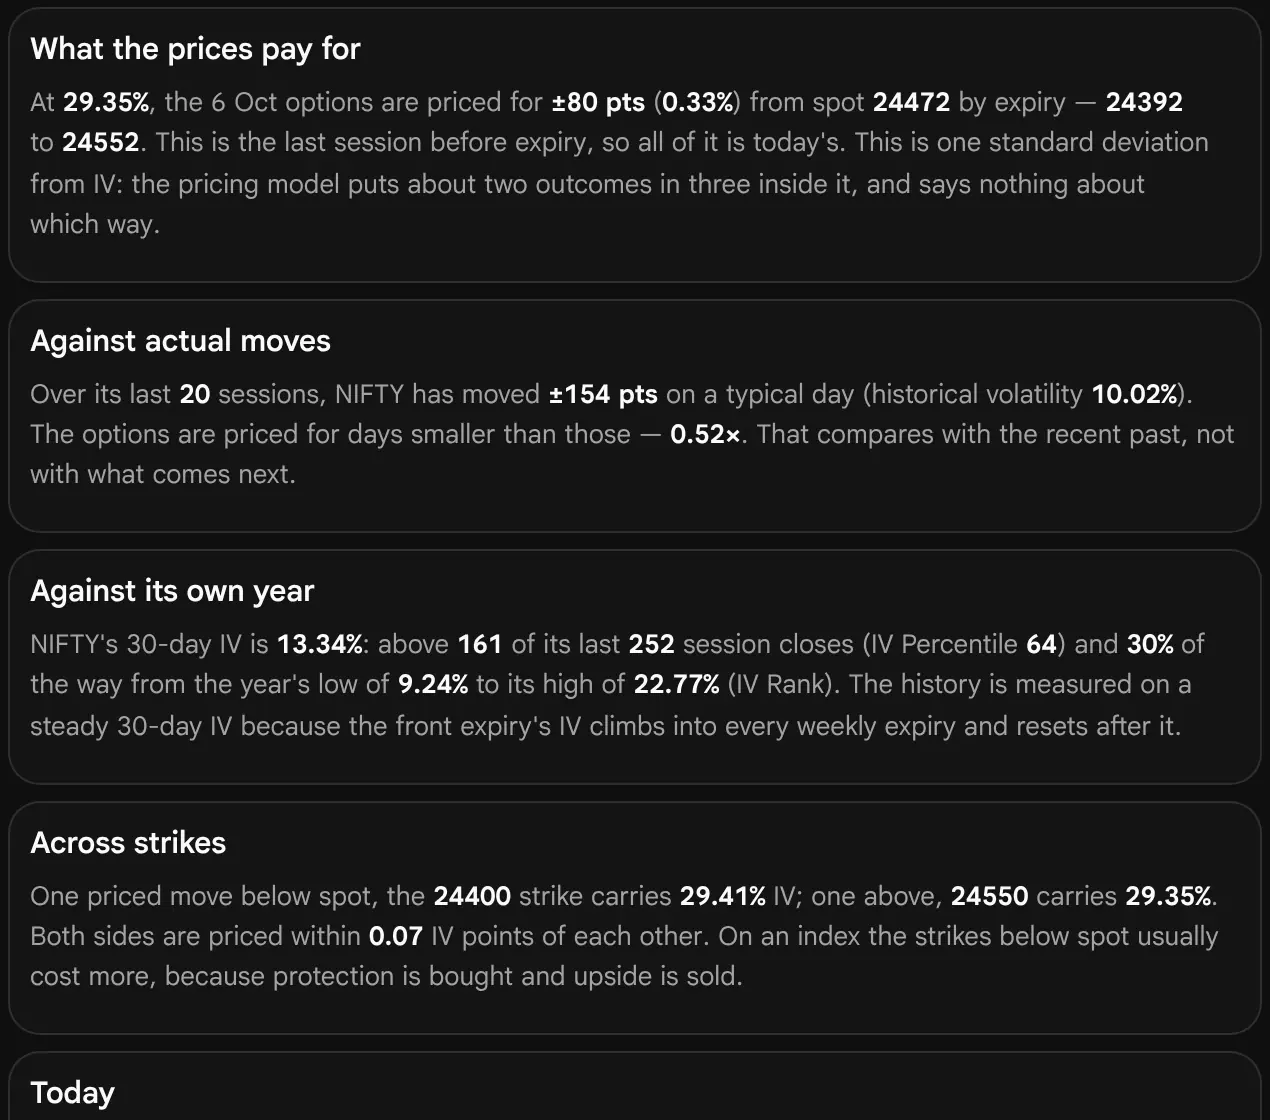
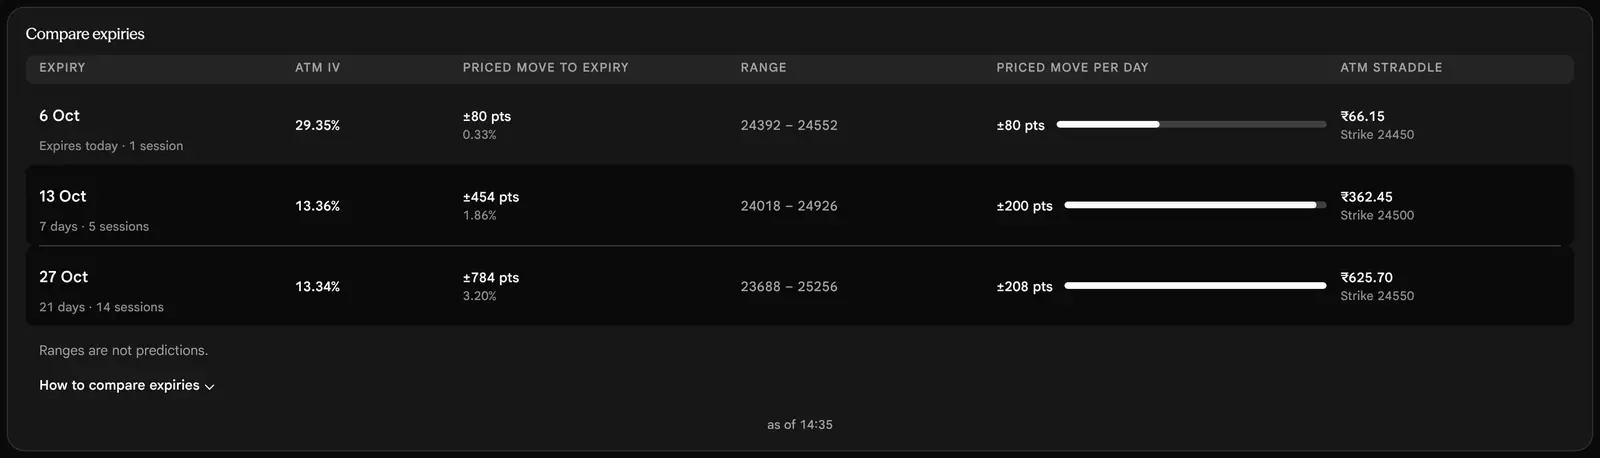
With 65 minutes left to the close, IV reads 29.35%. That looks extreme and means very little: about one ten-thousandth of a year is left, so every rupee of premium is a large figure when written as a yearly percentage. The useful figures are in points: the move left today is ±80 pts, and the page says the options are priced for days 0.52× the size of recent ones, because a remaining part of a day is set against a whole actual day of ±154. Read it as arithmetic: late on expiry day the number is still computable, but one tick can move it by a large fraction of a point, so it should not be read as though it were precise. The page adds no separate warning for this; it says the move is all of today’s and nothing more.
After the close on expiry day the expiring series has settled, so the page leaves it and moves to the next expiry. On Monday 19 October 2026, for example, once the market had closed, the page showed the 27 October expiry (expiry dates not checked against an exchange circular). The 30-day IV and the year are not affected: the year never reads an expiry on the day it settles (how the year is built).
| Situation | What happens to IV | What does not change |
|---|---|---|
| Into a weekend or holiday | Dips: the calendar days counted rise faster than the sessions | The priced move per day |
| The first session after | Can jump by several points | The priced move per day |
| Through the last week of a weekly expiry | Climbs into expiry, then resets after it | The 30-day IV the year is measured on |
| The last hours of expiry day | Can read very large and noisy | The move left today, in points |
The Forward, Not Spot; and the Call and Put Check
Why is the centre the forward and not spot, and why should a Call and a Put show the same IV?
The Centre Is the Forward
“At the money” sounds as if it means “at the current price”. For option pricing it does not. The centre of the distribution an option is priced against is the forward, which sits above spot by the cost of carrying a position to expiry. On the first picture the detail panel read the IV at 24539 while spot was 24512.35, about 27 points higher, and the straddle used the 24550 strike, the one nearest the forward, where the strike nearest spot is 24500. Reading “ATM IV” at the strike nearest spot reads the smile at a point systematically off its centre, and picks up a slice of the curve’s slope with it. The gap grows with time to expiry: at 6.5% a year and 30 days it is more than two strikes on NIFTY.
The page recovers the forward from the option prices themselves, with the Call and Put prices of the strikes nearest spot, so it needs no futures quote. The Option Chain page works differently: it prefers the forward implied by the vendor’s own IV and falls back to this method, so its IV column and this page’s ATM IV can differ slightly for that reason.
Why It Is Interpolated
The forward almost never lands on a listed strike. If the page read the nearest strike, the figure would step each time the forward crossed the midpoint between two strikes, by the slope of the smile over one strike interval. In a chart updated every minute that step looks like a real move, and it recurs all session. So the reading is interpolated between the strikes either side of the forward, in total variance, which makes it continuous.
One IV per Strike, From the Straddle
Put–call parity is not a model. It says a Call minus a Put at one strike equals the discounted gap between the forward and the strike, so if the centre is right one volatility reprices both legs. The page therefore solves one IV per strike by inverting the Call plus Put together. The straddle’s price barely depends on the forward at the money, so it is first-order immune to the very error that would split the two legs apart. Averaging two separately solved IVs is a different operation and a worse one: away from the money, an error in the centre turns a flat surface into a false skew that looks entirely plausible.
The Call and Put Gap Is a Data Check
The tooltip’s line Call vs Put and the detail panel’s sentence “at 24550 the Call alone solves 0.00 pts from the Put alone” report the difference between the IV of the Call alone and the Put alone at the strike nearest the forward. Near zero means the centre is right. A larger gap is a measurement of how far off the centre is, to first order, or of a stale quote. Some readers treat it as a directional signal. It is not one. There is a second cause as well: at any strike one leg is in the money and mostly intrinsic value, trades in a wider spread and barely moves with volatility, so inverting its price is numerically unstable and a stale quote on it can make a large and fictional gap. The page lists the gap as a check and never as a signal.
Why Two Platforms Show Different Numbers
Why does another platform show a different IV for the same option, and is either wrong?
The same option, at the same moment, will show different implied volatilities on different services, and none of them is necessarily wrong. IV is not observed. It is solved for, and the answer depends on the inputs chosen. This is what this page fixes:
| Input | What this page does | Where others differ |
|---|---|---|
| Interest rate | 6.5% a year, held flat | Exchanges and vendors use other rates; a different rate on the same price gives a different IV |
| Centre | The forward worked out from Call and Put prices (put–call parity) | Spot; a futures price; or a vendor’s IV-implied forward (the Option Chain’s choice) |
| Price | The last traded price of each leg | The midpoint of bid and ask, which reflects the current book but can be wide |
| Legs | One IV per strike from the Call plus Put; the Call against Put gap kept as a check | Separate Call and Put figures, or their average |
| Clock | Calendar days to the 15:40 close on expiry (15:30 before 3 August 2026); sessions for the per-day figures | Another close, trading days, or whole days |
Last traded price can be minutes old on a thin strike; that is the price of a rule that never uses a quote nobody has traded at. The practical consequence: comparing an IV across platforms means little unless both state their method, whereas comparing a figure against itself over time, from one consistent method, means a good deal. That is the comparison this page is built for.
India VIX Is a Different Figure
For NIFTY the detail panel prints India VIX among its calculations, and the History view can draw it. NSE builds the index from NIFTY’s near and next month options across every strike to a steady 30 days. Because out-of-the-money Puts carry more IV than the at-the-money strike, it usually reads a little above an at-the-money 30-day IV (the page’s own note says about a point). On the picture VIX is 13.41 and the 30-day IV 13.29%, only 0.12 apart: the invented market does not follow the page’s remark about a point. Treat it as a yardstick for whether the page’s NIFTY reading is in the right place, not as the same number. We have not checked the index method against NSE’s own document (What we have not verified).
The question each topic answers
- In what order do I read the page on an ordinary day, on expiry day and over a week?
- What does a full reading look like on real screens of the page, and what would I not conclude from it?
- What do readers get wrong about IV, and what should I check before I act on a reading?
- Which page do I open for which question about volatility and price?
- How do I read the page, and this guide, on a phone?
Routines: an Ordinary Day, Expiry Day and a Weekly Check
In what order do I read the page on an ordinary day, on expiry day and over a week?
A routine is an order of questions, so that the same reading is made the same way each time and a change in the answer means a change in the market, not in your habit. These three use only what the page prints.
An Ordinary Day (about three minutes)
- Check the time in the insight row. If it is not today’s, every figure is as of that time.
- The move in points (the first sentence of the opened insight), then the priced day against the actual day (the third sentence).
- The year (the second sentence and the verdict word): IV Percentile, IV Rank in the detail panel, and whether the window is a full year.
- The change since yesterday in points per session (the Today section of the detail panel), not in IV points after a weekend or holiday.
- One view to answer the next question: Strikes for which side costs more, Expiries for which expiry pays most per day, Intraday for how the day has moved.
Expiry Day
- Ignore the large IV figure and read the move left today in points (the detail panel calls it Priced move left today).
- Read the straddle price in the Expiries view; it shrinks through the afternoon, and the straddle split on Intraday says how much of that is time.
- Look at the Strikes view with the open curve on: expiry-day curves can be steep, and the gap between the two curves is the day’s repricing.
- Remember the limit. In the last hours one tick can move the solved IV by a large fraction of a point. The figure is computable and no longer precise.
A Weekly Check for a Position You Hold
- Open the Expiries view and compare the per-day column down the rows, not the IV column.
- Open History: where is the 30-day IV in its year, and above or below HV 20?
- Note the IV Percentile and the move per day, and compare them with last week’s note. The page stores no history of your readings; a note on paper does it.
- Write down what the numbers say and what they do not. They never say which way the price goes.
Before a known event (results, a policy decision), the Expiries view marks, for a stock, the first expiry on or after the results date. IV tends to be bid up ahead of a scheduled event and to fall once it has passed, whichever way the price went; an option held through such an event can lose value even when the direction was right. That is a general feature of option pricing, not a measurement the page makes.
Three Worked Readings
What does a full reading look like on real screens of the page, and what would I not conclude from it?
Each example reads the page in the routine’s order and ends with what the reading does not say. The market is illustrative. The figures are the ones the pictures print.
1. An Ordinary Wednesday, 11:30
Illustrative- ±378 ptsto 6 Oct, 24135 – 24890
- ±198 ptsa day, against ±154 actual
- IVP 65IV Rank 29, Normal for its year
- ±204 ptsthe priced day at the previous close
Reading. The 6 October options pay for about 378 points to expiry and 198 a day. A typical day over the last 20 sessions was 154, so the priced day is 1.29 times the actual day: bigger than recent days. The 30-day IV is above 65 per cent of its year, which the page calls normal. Within the day, ATM IV is down 1.00 point since the open, and the straddle split puts most of the straddle’s fall on IV (−₹24.33 of −₹31.75). Not concluded: that options are cheap to buy or dear to sell, or that the price will move 378 points. The page measures prices.
2. A Monday After a Holiday Weekend, 14:20
Illustrative- 16.67%ATM IV, +6.96 pts Today
- ±199 ptsa day, previous close ±197
- 3 shut daysbetween the two readings
Reading. A glance at IV alone says options became much dearer overnight. The Today section says one session is priced at almost exactly the size it was on Thursday’s close, 199 points against 197. The calendar lifted the percentage (Calendar days). Not concluded: that a rise in IV on a Monday is a rise in fear. Compare in points.
3. Expiry Day, 14:35
Illustrative- 29.35%ATM IV
- ±80 ptsmove left today
- ₹66.1524450 straddle
- Expires today6 Oct row
Reading. The IV figure is the largest on the screen and the least useful. Read the points: the 24450 straddle costs ₹66.15 and the move left is about 80 points either side of spot. The ratio of 0.52× compares part of a day with a whole one and is not a bargain signal. Not concluded: that the high IV is a sign of stress.
Mistakes and Traps
What do readers get wrong about IV, and what should I check before I act on a reading?
- Calling a level high or low on its own. “IV is 16” means nothing without a comparison: recent days, its own year, or today’s range.
- Reading IV as direction. A rising IV is not bullish or bearish. It can rise in a falling market and in a rising one, because both are movement.
- Comparing IV across days after a break. A Monday’s IV against a Friday’s is a calendar comparison. Use points per session.
- Comparing the IV column down the Expiries rows. Compare the per-day column.
- Treating 1 SD as a limit. About one outcome in three lands outside it, and the distribution is not symmetric.
- Trusting a rank built on a short history. IV Rank needs 252 sessions and rests on two days. A single spike can hold it low for a year. IV Percentile uses every day.
- Reading the Call against Put gap as a signal. It is a data check on the centre.
- Treating 29% on expiry day as stress. It is largely the clock. Read the move left, in points.
- Comparing one platform’s IV with another’s. Rates, centres and prices differ (why).
- Expecting the year to be NSE data. The pictures’ year is invented; on the live page it is NSE’s closing prices through the file’s last date, followed by today’s own reading.
- Forgetting events. IV tends to be bid up ahead of a scheduled event and to fall after it. A correct view of direction can still lose value in the option.
- Acting on a stale reading. Look at the time of the data in the insight row first.
Before You Act on a Reading
- Is the time of the data today’s, and the expiry the one I trade?
- Have I compared in points, not only in per cent?
- Which comparison am I using: recent days, the year, or the day’s range?
- Is the history a full year (252 sessions)?
- Could the calendar (a weekend, a holiday, the last hours) explain the move?
- Is there an event inside this expiry?
- Do I know the most I can lose in the position, apart from anything this page says?
This guide describes a tool. It is education, not advice. The risk disclosure in the footer of Sahi guide pages says that 9 out of 10 individual traders in equity Futures and Options incurred net losses. Selling options can lose more than the money put up, and nothing on this page limits that.
Which Tool When
Which page do I open for which question about volatility and price?
| My question | Open | Why |
|---|---|---|
| How many points is the market paying for, and is it dear? | Implied Volatility | This page: the move in points, against actual days and its year |
| What is the IV of this one strike, and its Greeks? | Option Chain | The IV column and the Greeks for every strike |
| What does the at-the-money straddle cost, and what is its expected move? | Straddle | The straddle’s price through the day and its expected move (0.85 times the straddle, “from the straddle”: a narrower band than this page’s 1 SD, “from IV”) |
| Which underlyings have a high IV Rank today? | Options Scanner | Ranks the same 30-day IV against the same file, across underlyings |
| What would my position be worth if IV changed? | Strategy Builder | Its What if controls move IV and show the effect on a position |
| Where are positions stacked, and how did Open Interest change? | Open Interest | Open Interest; this page does not use it |
| Are Puts or Calls heavier overall? | PCR | The ratio of Put to Call Open Interest, with its crossovers |
| Where does hedging pressure sit by strike? | GEX Levels | Gamma exposure strike by strike, with its assumptions stated |
The guides for each tool are linked in Read next at the foot of this page.
Reading It on a Phone
How do I read the page, and this guide, on a phone?
At 768 pixels and below the page has a phone layout of its own. In short: the insight row sits on top, and the Intraday and History charts fill the rest of the screen. What changes:
- The views stay a capsule across the top (or fold into a menu that shows the name of the view when the bar is too narrow).
- The insight row is a closed row with the symbol and the verdict (in sentence case, for example Normal IV). It opens as a sheet over the page, and the four answers are in the sheet.
- Intraday and History fill the screen. The chart takes all the room under the insight row. The key moves to its own line under the card title. The four History figures and the straddle split follow below; scroll down for them.
- Tabs and tools share one row. The interval tabs (1m to 1D on Intraday, 1M to 1Y on History) sit on the left, and the crosshair and full screen on the right. The head above shows only the figure and its change; the time and spot are in the tooltip when you touch the chart.
- The Intraday card keeps its scope line under the plot (6 Oct expiry · 30 Sep session), which a desktop leaves out.
- Customise opens from the settings button in the top bar as a sheet from the bottom; the button in the page bar is hidden at this width.
- Strikes and Expiries scroll as before. The percentage scale of the smile sits in a gutter at the right.




Reading this guide on a phone. A wide picture scrolls sideways inside its frame, with a line that says so and an Enlarge button that opens it full size. Tables scroll sideways too. Rotating the phone gives the pictures more room. The phone pictures were taken at 390 pixels, one common phone width; other widths were not captured. The chart tools and the sheet behaviour were read from the code and the pictures, not tried on a physical phone (not tested).
What the Page Does Not Do
What does the page not do, and where does a reading stop being worth much?
- It does not forecast. It never says which way price will go, how much it will move, or whether options are a good buy. The priced move is what the prices pay for. The sentence about recent days compares with the past.
- It reads one underlying and one expiry at a time in its insight, Intraday and Strikes. The Expiries view reads up to 3 expiries; History reads a 30-day blend of all of them.
- It depends on the day’s archive. Without it, the page shows one reading and says so. A minute with no snapshot is a minute with no reading.
- It does not solve every strike. A strike whose price barely moves with volatility (deep in the money, or a few paise) is left out, not guessed.
- It is least precise in the last hours before expiry, when one tick can move the solved IV by a large fraction of a point. It adds no separate warning.
- A settled expiry gets no reading. The page refuses rather than show a number that looks like a good one.
- The year has limits. It is a file of daily closes that ends at its last date (16 October 2026 at the time of writing), followed only by today’s own reading; SENSEX and BANKEX are not in it; a new listing has a short history, named as such.
- It does not compute margin, costs or a position’s profit and loss. It does not place orders.
- It keeps no history of your readings. Only the Customise switches and the last view are stored, in this browser.
- It is a pricing-model reading. Black–Scholes in forward form at a fixed 6.5% rate. Another model, rate or price gives another IV, which is why platforms differ.
What We Have Not Verified
Which statements in this guide could we not confirm, and what should I check myself?
Everything in this guide about how the page behaves was read from the page’s own program code or taken from a picture of the page. The items below are the ones we could not confirm. Where the guide touches one of them it links here instead of stating it as fact. For the exchange rules we tried the exchanges’ own pages and could not open them, so we have left the rules out rather than repeat them from memory.
| What | What we do not know | What you can do |
|---|---|---|
| The loading state | The page shows Reading today’s option prices while the day’s archive is being read. In our captures the page fell back to its First reading state instead of staying in the loading state, so we have no picture of the loading state, and it is described here from the code. | Reload the live page and watch the first seconds. |
| The results-date line on a stock | The line Includes results on 16 Oct and the badge on the Expiries row come from a temporary source of company dates. No picture in this guide is of a stock, and we have not confirmed how accurate or how current the dates are. | Check the company’s own announcement of its results date. |
| The close used for time to expiry: 15:40 | The page counts time to expiry to 15:40 on the expiry date from 3 August 2026 and to 15:30 before. The app’s own code comment ties the 15:40 close to SEBI’s Closing Auction Session, effective 3 August 2026, but we could not open any circular or exchange page to confirm the time. The note printed under the priced-move calculation in the detail panel says the same: 3:40 pm close on expiry, and 3:30 pm for expiries before 3 Aug 2026. | Read the latest NSE circular on market timings and the expiry-day settlement price. |
| The 6.5% rate | The page uses 6.5% a year in every solve; the code comment says it is anchored to the repo rate that Indian desks price with. We have not confirmed what exchanges, brokers or other vendors use. | If your broker’s IV differs, ask what rate and centre it uses. |
| India VIX and the “about a point above” remark | The page’s own notes say NSE builds India VIX from NIFTY’s near and next month options across all strikes and that it usually reads about a point above an at-the-money 30-day IV. We could not open NSE’s methodology to confirm either statement. | Read NSE’s India VIX methodology document. |
| Where the year of 30-day IV comes from | The file’s header says it is solved from NSE F&O closing prices (bhavcopy), reading the three expiries after each session. The file on the live page runs from 15 September 2025 to 16 October 2026 (270 sessions) and includes the Sunday Budget session of 1 February 2026. We read these facts from the file and the build script; we did not rebuild the file or check its values against NSE. The year in the pictures is invented. | Compare the page’s IV Rank with the Options Scanner’s for the same symbol: they use the same file. |
| The 0.85 times the straddle expected move | The Option Chain and the Straddle page print an Expected move of 0.85 times the straddle (the figure is based on the straddle). We have found no study behind the factor; it is a product convention. This page’s figure is based on the IV, is labelled from IV, and is about 1.25 times the straddle by arithmetic. The Option Chain also prints it, as 1 SD to expiry, From ATM IV. | Treat both as bands, not limits. |
| A new high or low in the year | With a full year, a reading above every close prints IV Rank 100 (below every close, 0); in a shorter window the History view says Outside the year’s range under IV Rank. This was read from the code and not reproduced in a picture. | If the page reads differently, trust the page and tell us. |
| Keyboard, touch and phone behaviour | The slider on the smile (arrow keys, Home, End, Escape), Escape on the insight and Customise, the chart camera, and the phone sheets were read from the code. The phone pictures were taken at 390 pixels; no physical phone was used and the detail panel was not captured on a phone. | If a control does not respond as described, use the pointer or touch instead. |
| The straddle split is first-order | The four parts are worked from the model’s sensitivities at the start of the day and add up exactly because the last part is the remainder. The page itself calls the split rough when the remainder is over a third. We have not measured how close it comes on real days. | Read the remainder row first. |
| Exchange holidays and expiry dates in the pictures | The pictures use Friday 2 October 2026 (Mahatma Gandhi Jayanti) and Tuesday 20 October 2026 (Dussehra) as holidays and Tuesdays as weekly expiries. The holidays are read from the app’s own list (src/lib/marketSession.ts), which its authors cross-checked against NSE’s calendars in September 2026; we did not check them again against an exchange circular, and expiry weekdays and lot sizes change by circular. | Read the exchange holiday list and the contract specification for your underlying. |
| General statements about options markets | A few sentences describe markets in general and are not measured by the page: that IV tends to be bid up ahead of a scheduled event and to fall after it; that on an index the strikes below spot usually cost more; that IV is often above the volatility that followed; and what other platforms use for rate, centre, price and clock. They are the page’s own explanations or common knowledge, and we have not tested them. | Treat them as background, and check your own platform’s method. |
| The Live updates label | The opened insight carries a label that reads Live updates or Saved reading, set by whether the card follows the newest reading. We read this from the code and did not test how often the newest reading changes on the live page. | Read the time of the data, not the label. |
| Pictures taken before the page changed | On 19 October 2026 the page changed in ways several pictures do not show. The chart titles are shorter (ATM IV today, IV by strike, Compare expiries, 30-day IV history) and so are the keys (ATM IV, NIFTY spot, Day high / low, 30-day IV). The Expiries columns read Move to expiry and Move per day. The History figures and the four Strikes figures have new names in sentence case. The insight row’s priced-move line is shorter. The Intraday and History charts are simple: plain interval tabs, the crosshair and full screen, with no indicators, chart type or chart settings. On a phone those two charts fill the screen. These pictures were taken before that change and have not been retaken, so they still show the earlier page: The page as it opens: the bar, the insight row and the Intraday chart, The History figures with 72 sessions, The insight row, closed, The Intraday view, The chart tools, Hovering a point, Both extra lines off, The split of the straddle’s change, The Strikes view, The four figures below the curve, Hovering the curve, All strikes, The open curve switched off, The Expiries view, The same table on expiry day, 14:35, BANKNIFTY with one monthly expiry: the furthest stands in, The History view, The four figures under the year chart, Hovering a day, India VIX and the NIFTY close switched on, Customise on the Intraday view, Customise on the Strikes view, The first reading of a session, The Intraday chart the same afternoon, On a phone: the top of the page, Scrolling down to the chart, The insight opened as a sheet, Customise as a bottom sheet. The text describes the page as it is now. | Trust the text where it differs from a picture, and read the labels on the page itself. |
| The terminal widget | Inside a terminal widget the page puts its content in its own scroller under the bar. We did not capture it. | Open the page in the terminal and check. |
If you find any of these settled by an official source, the guide can be updated: each one has a place in Sources.
Glossary
What does each word mean?
- Underlying
- The index or share an option is written on, for example NIFTY. Its price is called spot.
- The price of one option, in rupees per unit. The chain prints it as the last traded price. It is the number from which implied volatility is worked out.
- Call, Put
- A Call gives its holder the right to buy the underlying at the strike; a Put gives the right to sell it. A Call gains when the price rises above the strike, a Put when it falls below. (Some screens and the exchange use the codes CE and PE for the same two.)
- Strike
- The price at which the holder of a Call may buy, or the holder of a Put may sell, the underlying.
- Expiry
- The date on which an option ends. The page counts time to the close of the option market on that date (15:40 from 3 August 2026).
- At the money (ATM)
- An option whose strike is at, or nearest to, where the underlying stands. On this page the centre is the forward, not spot.
- Time value
- The part of an option’s premium above what it would be worth if it ended now. It is what is paid for the movement that may happen before expiry, and it is the part implied volatility prices.
- Implied volatility (IV)
- The size of move an option’s price is paying for, written as a yearly percentage. It is worked out from the price, not forecast. Higher IV means dearer options. It says how big a move is priced, never which way.
- Vol point, IV point
- One percentage point of implied volatility: 12.00% to 13.00% is one vol point. A change in IV is written in points ("−1.00 pts").
- ATM IV
- The implied volatility at the forward, taken from the Call plus Put (the straddle) at the two strikes either side of it and interpolated between them, so it does not jump when the price crosses a strike.
- Forward
- Where the option prices put the underlying at expiry: spot plus the cost of carrying it until then. The page reads it from the traded Call and Put prices, using put–call parity, at a fixed yearly rate of 6.5%.
- Put–call parity
- A relationship that holds whatever the model: a Call minus a Put at one strike equals the discounted gap between the forward and the strike. It means one volatility reprices both legs of a strike.
- Straddle
- The Call and the Put of one strike taken together. Its price is the Call premium plus the Put premium.
- Standard deviation (1 SD)
- A yardstick for the size of a move. The priced move to expiry is one standard deviation: the pricing model puts about two outcomes in three inside it. It says nothing about which side.
- Priced move
- The move the at-the-money IV pays for, in points: spot × IV × √(days left ÷ 365). One standard deviation. Printed to expiry and per day.
- Session
- One trading day. Weekends and exchange holidays are not sessions: the market is shut and the page counts no movement on them.
- Priced move per day
- The priced move to expiry divided by the square root of the sessions left: what one session is priced for. On the last session it is the whole move left today.
- Historical volatility (HV 20), actual day
- How big the underlying’s days have actually been: the standard deviation of the last 20 close-to-close moves, scaled to a year. The page converts it to points for one day and calls it the actual day.
- Priced against actual
- The priced day divided by the actual day, from the whole points the page prints. At 1.2 or more the page says bigger; at one over that or less, smaller; between, about the same.
- IV Percentile (IVP)
- The share of the last 252 closes of the 30-day IV that closed below today’s. Shown once 60 sessions of closes exist.
- IV Rank
- Where today’s 30-day IV sits between the year’s lowest and highest close, from 0 to 100. It waits for a full 252 sessions, and rests on two days only.
- 30-day IV
- A steady reading blended from the expiries around 30 days, so the year is not ranked on the weekly sawtooth of the front expiry.
- Calendar days
- IV counts every day to expiry, weekends and holidays included, as brokers and India VIX do. The market only moves on sessions. That is why the IV of a front expiry dips into a weekend and jumps after it.
- Smile, skew
- Options at different strikes of one expiry carry different IVs. Drawn against the strike, the pattern is the smile. On an index the strikes below spot usually cost more.
- India VIX
- NSE’s 30-day volatility index on NIFTY. The page shows it beside NIFTY’s own figures as a yardstick. It is a different method from the page’s ATM IV, so the two are not the same number.
- Vega
- The rupees an option’s premium moves for one vol point. An option with almost no vega cannot show an IV: its price hardly moves with volatility, so the page does not solve it.
- Time decay (Theta)
- The premium an option loses as time passes with nothing else changing.
- Open Interest
- The number of option contracts open at a strike. This page does not use it: the IV is worked out from traded premiums.
- Last traded price (LTP)
- The price of the latest trade in a contract. The page solves IV from the last traded price of each leg, not from the bid–ask midpoint. On a thin strike it can be minutes old.
Questions Readers Ask
What do readers ask most?
What is implied volatility?
The size of move an option’s traded price is paying for, written as a yearly percentage. Higher IV means dearer options. It says how big a move is priced, never which way. It is solved from the price, not forecast.
How do I know whether IV is high or low?
Compare it with something. The page uses the underlying’s recent days (the priced day against the actual day) and its own past year (IV Percentile and IV Rank on a 30-day IV). At 80 or more it says high for its year, at 20 or less low.
How many points is the market pricing?
Spot times IV times the square root of the calendar days to expiry over 365. That is one standard deviation. Divide by the square root of the trading sessions left for one day. The page prints both, with the range.
Are options cheap or dear right now?
One fair test is the underlying’s own recent days: the priced day against the typical day of the last 20 sessions, in points. The page names a side only when the priced day is at least 1.2 times the actual day, or at most one over that (0.83), because a 20-session figure is itself uncertain by about 16 per cent. It describes prices, not what to do.
Why does IV jump on Mondays and into expiry day?
IV counts calendar days to expiry, as India VIX and brokers do, but the market moves only on sessions. After a weekend or holiday the same priced day is spread over fewer calendar days, so the percentage rises with nothing having happened. The move per day, in points, carries no calendar.
Why does the page use a 30-day IV for the year?
The IV of a weekly expiry climbs into each expiry and resets after it. A year of those would rank the day of the week. The 30-day blend removes that sawtooth, and it is the figure the Options Scanner ranks, so both pages print one IV Rank.
What is the difference between IV Percentile and IV Rank?
Percentile is the share of the last 252 closes below today’s level and uses every day. Rank is the position between the year’s lowest and highest close and rests on those two days. Percentile appears from 60 sessions; Rank waits for 252.
Why do the Call and the Put show the same IV here?
Because with the right centre they must. Put–call parity is not a model: one volatility reprices both legs of a strike. A gap between them measures an off-centre calculation or a stale quote, so the page lists it as a data check and never as a signal.
Why does my broker show a different IV?
Rate, centre, price and clock differ. This page uses 6.5%, the forward, the last traded price, one IV per strike from the straddle, and calendar days to the 15:40 close. Compare a figure with itself over time, from one method.
How is this different from India VIX?
India VIX is NSE’s 30-day index built from NIFTY’s near and next month options across every strike. The page shows it for NIFTY beside its own figures as a yardstick, not as the same number.
Is this live?
Not as a continuous stream. The chain pages re-fetch about every 5 seconds while the market is open. This page works from the one-minute archive of the day and prints the time of its newest reading in the insight row. This page does not use Open Interest.
Sources
Where does each statement in this guide come from?
The guide rests on the program code of the Implied Volatility page and on pictures of the page itself. The constants below are quoted in the text from one list (scripts/guides/implied-volatility-parts/limits.mjs); each row names the file the value comes from. No official exchange or regulator document is cited as proof of an exchange rule: the rules we could not confirm are in What we have not verified.
Where Each Part Comes From
| Part of the guide | Source files |
|---|---|
| The page, its four views and the order of the parts | src/features/implied-volatility/ImpliedVolatilityPage.tsx |
| The four answers: priced move, actual days, the year | ivAnswer.ts; src/lib/atmIv.ts (expectedMoveFromIv); src/lib/realizedVol.ts; src/lib/ivHistory.ts; src/features/options-scanner/ivTerm.ts, ivTermBlend.ts |
| The insight row, the opened box and the detail panel | IvInsightCard.tsx; ivInsight.ts; src/lib/insightMovement.ts |
| Intraday view and the straddle split | IvChart.tsx; src/lib/sahiChart/ChartPaneShell.tsx (minimal); IvPremiumSplit.tsx; src/lib/ivSeries.ts; src/lib/premiumAttribution.ts |
| Strikes view | IvSmilePlot.tsx; IvPlotChrome.tsx; src/lib/atmIv.ts (solveSmile) |
| Expiries view | IvExpiryTable.tsx; ivExpiries.ts |
| History view and the year of closes | IvYearChart.tsx; src/lib/dailyBars.ts; src/lib/indiaVix.ts; public/iv-term-history.json; scripts/build-iv-term-history.ts |
| Customise and its defaults | IvCustomizePanel.tsx; ivCustomiseSettings.ts |
| The solve: forward, straddle, interpolation, 6.5%, 15:40 | src/lib/atmIv.ts; src/lib/optionPricing.ts; src/services/analytics.ts (fractionalYearsToExpiry, parityImpliedForward); src/lib/marketSession.ts (the close; filterLiveExpiries, the move to the next expiry after it) |
| The phone layout | implied-volatility-phone.css; ImpliedVolatilityPage.tsx (the fold) |
| Refresh timing | src/hooks/useOptionChain.ts; ImpliedVolatilityPage.tsx (EXPIRY_REFRESH_MS) |
| The pictures | scripts/guides/shot-implied-volatility.cjs; implied-volatility-mock.cjs; implied-volatility-parts/figures.json |
The Numbers the Guide Quotes
| Number | What it is | Source file |
|---|---|---|
| 6.5 | Fixed yearly interest rate in every solve | src/lib/optionPricing.ts |
| 15:40 | Close of the option market used to count time to expiry, from 3 August 2026 (15:30 before) (not verified) | src/lib/marketSession.ts |
| 365 | Calendar days in the year for time to expiry (days left divided by 365) | src/services/analytics.ts |
| 20 | Sessions of daily closes behind the actual day (HV 20) | src/features/implied-volatility/ivAnswer.ts |
| 252 | Trading sessions used to turn a yearly figure into a daily one | src/lib/realizedVol.ts |
| 20 | Per cent either way inside which the priced day and the actual day are called about the same (ratio 1.2) | src/features/implied-volatility/ivAnswer.ts |
| 80 | Printed IV Percentile at or above which IV is called high for its year | src/features/implied-volatility/ivAnswer.ts |
| 20 | Printed IV Percentile at or below which IV is called low for its year | src/features/implied-volatility/ivAnswer.ts |
| 252 | Sessions that make a full year of closes | src/features/implied-volatility/ivAnswer.ts |
| 60 | Sessions of closes needed before an IV Percentile is shown | src/lib/ivHistory.ts |
| 252 | Sessions of closes needed before an IV Rank is shown | src/lib/ivHistory.ts |
| 30 | Days of the steady 30-day IV | src/features/options-scanner/ivTermBlend.ts |
| 2 | Expiries with fewer days left than this are left out of the 30-day blend | src/features/options-scanner/ivTermBlend.ts |
| 14 | The furthest expiry must be at least this many days away for a 30-day IV to be read | src/features/options-scanner/ivTermBlend.ts |
| 0.3 | Strike sides closer than this many IV points are called priced about the same | src/features/implied-volatility/ivInsight.ts |
| 0.005 | A change in IV smaller than this many points has no direction colour | src/features/implied-volatility/ivInsight.ts |
| 2.5 | Priced moves either side of spot that the Strikes view draws before All strikes is switched on | src/features/implied-volatility/IvSmilePlot.tsx |
| 7 | The Strikes view never draws fewer strikes than this | src/features/implied-volatility/IvSmilePlot.tsx |
| 3 | Live expiries the Expiries view reads | src/features/implied-volatility/ImpliedVolatilityPage.tsx |
| 60 | The Expiries view re-reads its chains at most this often (seconds), and only when a new reading has arrived | src/features/implied-volatility/ImpliedVolatilityPage.tsx |
| 400 | Most readings drawn on the Intraday chart (the oldest are thinned first) | src/lib/ivSeries.ts |
| 0.1 | Rupees of premium per volatility point below which a strike is not solved | src/lib/atmIv.ts |
| 400 | Calendar days of daily closes asked for (the year of actual moves) | src/lib/dailyBars.ts |
| 5 | Option chain re-fetched this often while the market is open (on the chain pages) | src/hooks/useOptionChain.ts |
| 768 | Screen width in pixels at and below which the phone layout applies | src/features/implied-volatility/implied-volatility-phone.css |
| ivView:v1 | Browser storage key of the view the page reopens on | src/features/implied-volatility/ImpliedVolatilityPage.tsx |
| ivCustomise:v1 | Browser storage key of the Customise switches | src/features/implied-volatility/ivCustomiseSettings.ts |
Exchange Facts Looked For
We searched for the exchanges’ and regulator’s own statements on the close of the derivatives market from 3 August 2026, the settlement price on expiry day, and the construction of India VIX. The exchanges’ own pages did not open from our tools, so none of these is cited here as verified.
The Pictures
Each picture is a capture of the real page on an invented market, taken with the page clock frozen at the moment named in the caption. They are regenerated with node scripts/guides/shot-implied-volatility.cjs, and the figures in the text are checked against figures.json, which that script writes, every time the guide is built.
Test Your Knowledge
Check the mechanics before you take them to a live chain.
1. On a Monday after a holiday weekend, ATM IV is up 6.96 points since Thursday’s close, while the priced move per day is up 2 points. What is the likeliest reason for the difference?
2. The priced move to expiry reads ±378 pts. What does it say?
3. Why should you compare the Move per day column, not the ATM IV column, down the rows of the Expiries view?
4. A single sharp spike set the year’s high. Which of the two numbers is held down by it?
5. The year of 30-day IV is missing for an underlying. What does the verdict pill do?
6. The Call alone and the Put alone at one strike solve to different IVs. What does the page make of it?
7. None of the live expiries is 30 or more days away. How does the page get a 30-day IV?
8. Only 72 sessions of closes are stored for an underlying. What does the page show for the year?
About the Sahi Implied Volatility
Implied volatility (IV) is the size of move option prices are paying for, written as a yearly percentage. On its own a figure like 16% is hard to use, so this page turns it into points: the move the options price by expiry, the same move for one day, and how that compares with the days the underlying has actually had.
It also places the reading in its own past year, with IV Percentile and IV Rank on a steady 30-day IV solved from NSE's F&O closing prices, and shows IV at every strike, across every live expiry, and through today one reading a minute. Every figure is solved from traded premiums, and every one is worked through in the page's calculations.
At a glance
- Data
- The option chains of the underlying you select, and the one-minute readings collected for the day; worked out on the page
- Updates
- The Expiries view re-reads other expiries about every minute (60 seconds) when a new reading has arrived; the chain pages re-fetch about every 5 seconds in market hours. Open Interest is not used here
- Coverage
- The underlyings the app lists; the year of 30-day IV exists for NSE F&O underlyings (not SENSEX or BANKEX), and India VIX is shown for NIFTY only
- Orders
- Analysis only. The page places no order
- Kept
- The Customise switches and the last view stay in this browser; nothing is sent to a server
- Pictures
- Real captures of the page on an invented NIFTY and BANKNIFTY, with the page clock frozen at the moment named in each caption. Some were taken before the page changed on 19 October 2026 and are marked
See it on today's numbers
Everything above is method. These articles apply it to a live book — implied volatility among the rest — and are rebuilt as the snapshot data refreshes. Where a symbol's option book is too thin to support a reading, the article says so rather than asserting a level.
Frequently asked questions
What is implied volatility?
The size of move an option's traded price is paying for, once strike, time to expiry and the underlying's level are accounted for, written as a yearly percentage. Higher IV means dearer options. It says how big a move is priced, never which way — IV can rise in a falling market and in a rising one.
How do I know whether IV is high or low?
Compare it with the same underlying's own past year. IV Percentile is the share of the last 252 sessions whose IV closed below today's; IV Rank is where today sits between the year's lowest and highest close. At 80 or more this page calls IV high for its year, at 20 or less low. The year is measured on a steady 30-day IV, because the front weekly expiry's IV climbs into every expiry day and would rank the day of the week instead of the volatility.
How many points is the market pricing?
Multiply the underlying's level by the IV and by the square root of the calendar days to expiry over 365. That is one standard deviation: the pricing model puts about two outcomes in three inside it, and it says nothing about which side. Divide it by the square root of the trading sessions left and you have the move priced for one day. The page prints both, with the range they span.
Are options cheap or expensive right now?
One fair test is the underlying's own recent days. The page sets the move priced for one day beside the underlying's typical day over its last 20 sessions (its historical volatility, from daily closes), both in points. Priced for bigger days than the market has been having reads as dear; smaller, as cheap. It only names a side when the gap is over 20%, because a 20-session figure is itself uncertain by about 16%.
Why does IV jump on Mondays and into expiry day?
IV counts calendar days to expiry, as India VIX and brokers do, but the market only moves on trading days. Friday's price spreads two sessions over four calendar days; Monday's spreads one over one — so Monday's IV reads several points higher with nothing having happened. The move priced per day, in points, carries no calendar, which is why the page also compares today with the previous close that way.
How is this different from India VIX?
India VIX is NSE's 30-day index built from NIFTY's near and next month options across every strike. Out-of-the-money PUTs carry more volatility than the at-the-money strike, so VIX usually reads about a point above an at-the-money 30-day IV. The page shows it beside NIFTY's own figures as a yardstick, not as the same number.
Why do the CALL and the PUT show the same IV here?
Because with the correct centre they should. Put-call parity is an arbitrage relationship, not a model, and it means one volatility reprices both legs of a strike. Where two figures disagree at one strike, the gap measures stale quotes or an off-centre calculation, so this page lists it among its calculations as a data check rather than as a signal.
Read next
Explore more Sahi tools
Every tool runs on the same market data and keeps whichever instrument you have selected, so you can move between them without re-picking the symbol.
Option Chain
Scan and build
Every Sahi guide
Each guide pairs with a live tool. The options FAQ collects every question from all of them in one place.